Buying a Manufactured Home in California: How the Regions Differ
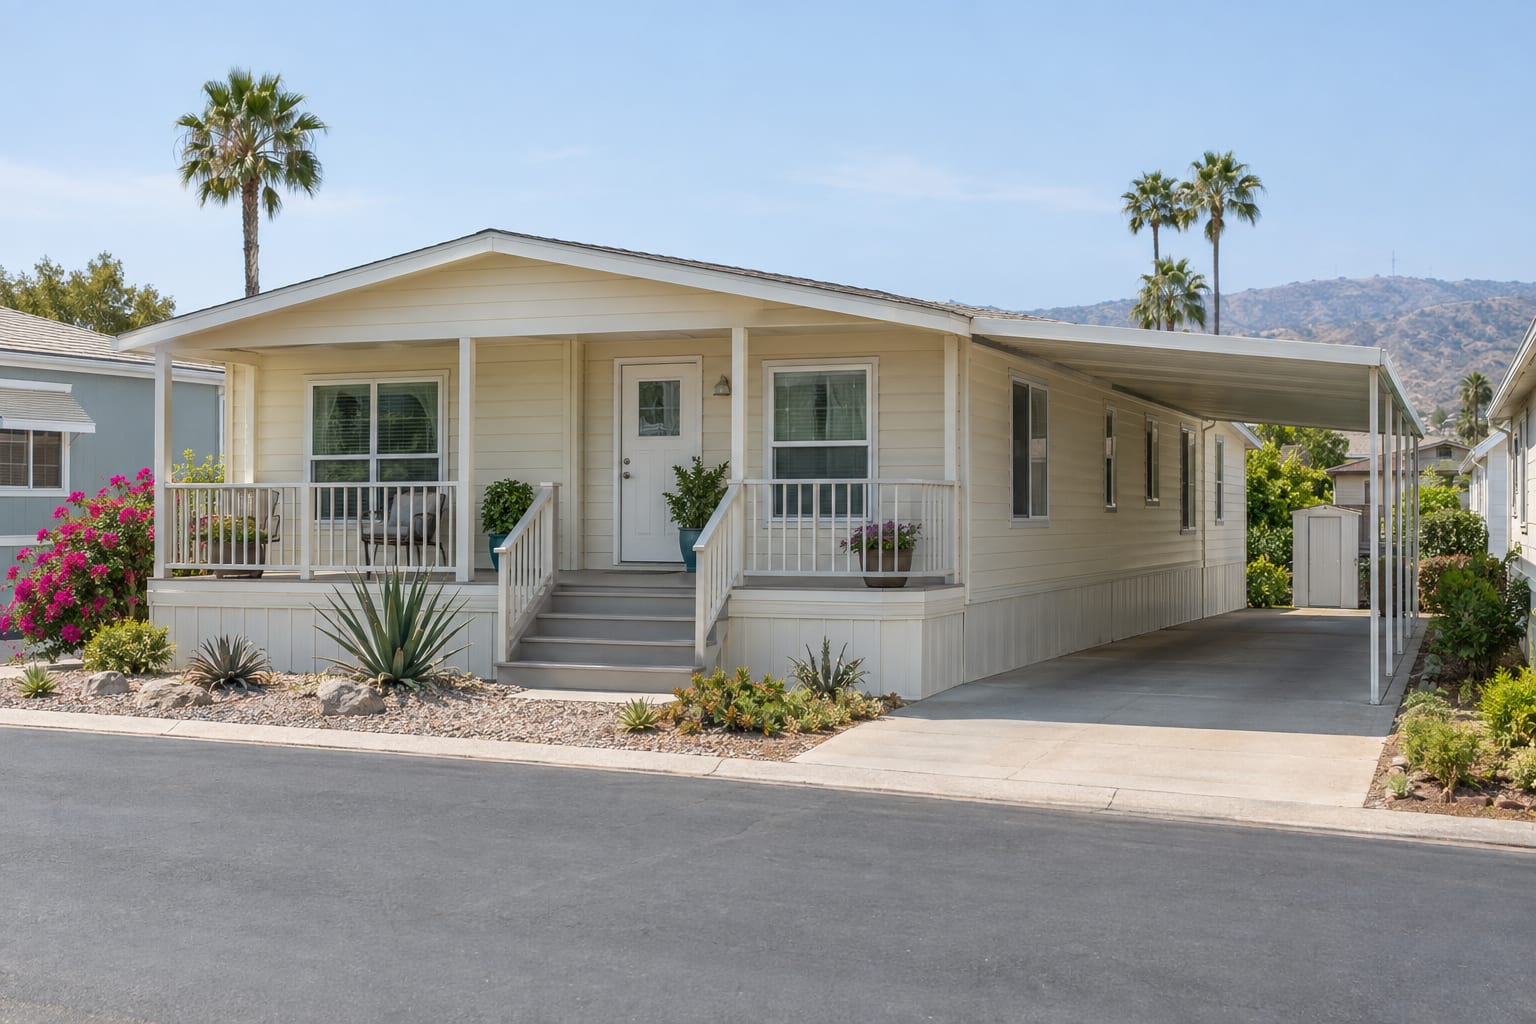
The rules for buying a manufactured home are the same across California, but what you find for sale changes a great deal from one region to the next. Near the coast and around the Bay Area, most homes sit on rented spaces in communities. Inland and in the foothills, homes on their own land become common, and with them come wells, septic systems, and wildfire or flood questions.
Those differences decide which kind of loan applies and what the home costs each month, so they are worth knowing before you pick a place to look.
What stays the same wherever you buy
- Title. California titles and registers manufactured homes through HCD (the Department of Housing and Community Development), not the DMV. California HCD title basics covers the paperwork.
- Community tenancy. Homes on rented spaces come under the state’s Mobilehome Residency Law, and HCD publishes consumer information for residents. Some cities and counties add a mobilehome rent ordinance of their own, so that part does vary by place.
- Two kinds of loan. A home on a rented space is financed on its own with a home-only or chattel loan. A home permanently attached to land you own can often be financed together with the land through land-and-home financing.
- Two approvals. In a community, the community’s approval of you as a resident and the lender’s approval of the loan are separate reviews.
How the regions compare
California regions for manufactured home buyers
| Region | What you mostly find | Ask about early |
|---|---|---|
| The coast, San Diego to the Central Coast | Homes on rented spaces in long-established communities | Space rent, local rent rules, salt-air wear |
| Inland Empire and the deserts | Communities, plus homes on their own lots | Age rules, summer cooling, part-year occupancy |
| Central Valley | Communities in the cities, rural parcels around them | Wells and septic, flood zones, cooling |
| Bay Area and North Bay | Homes on rented spaces where land is expensive | Space rent, local rent rules, wildfire zones |
| Foothills and mountains | Homes on land the owner also owns | Wildfire zone and insurance, roof load, road access |
The coast: mostly communities on leased land
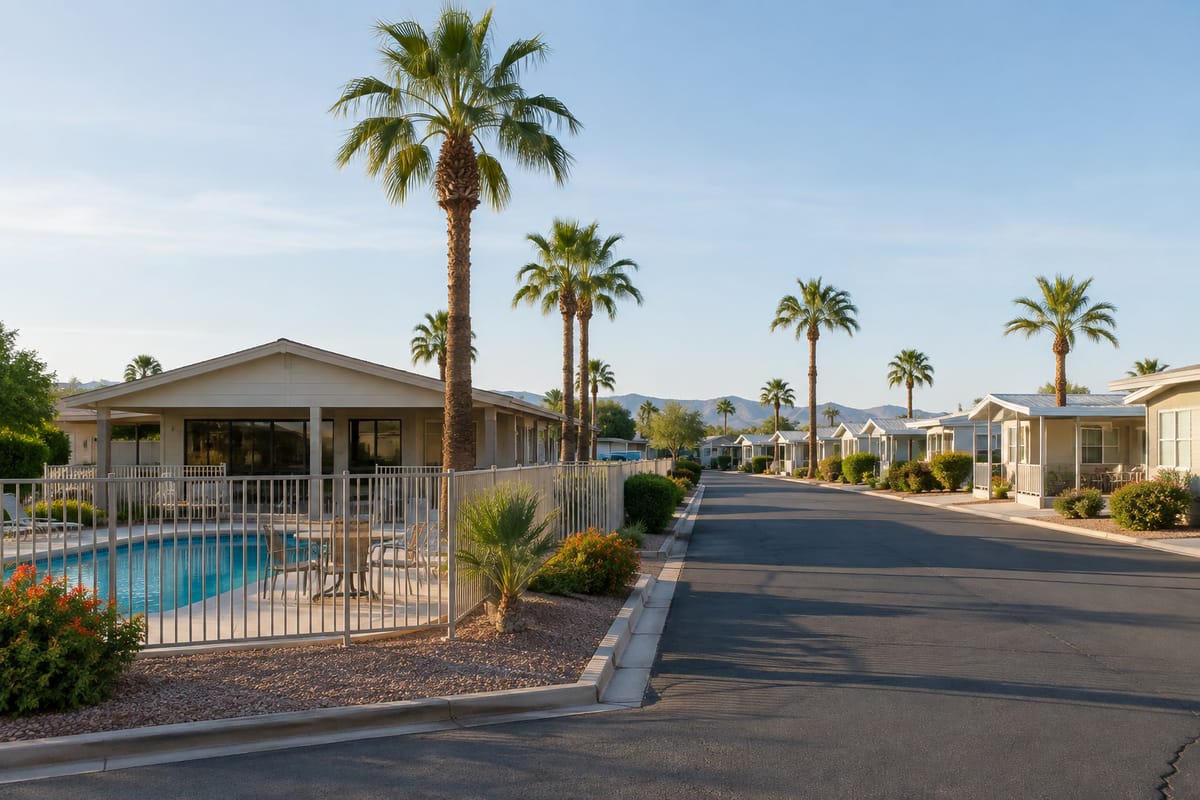
From San Diego County through Orange County, the Los Angeles coast, Ventura and the Central Coast, land is expensive and manufactured homes are concentrated in communities. You buy the home and rent the space, so space rent is the number that matters most. Get the current amount and the recent increases in writing, and ask whether the city or county has a mobilehome rent ordinance that covers the space.
Because the home is valued without land, what similar homes in the same community have sold for carries a lot of weight. Comparable sales reports show that for California communities. Close to the ocean, salt air is hard on metal roofs, awnings and fasteners, so look at them closely.
Local pages: San Diego, Huntington Beach and Long Beach.
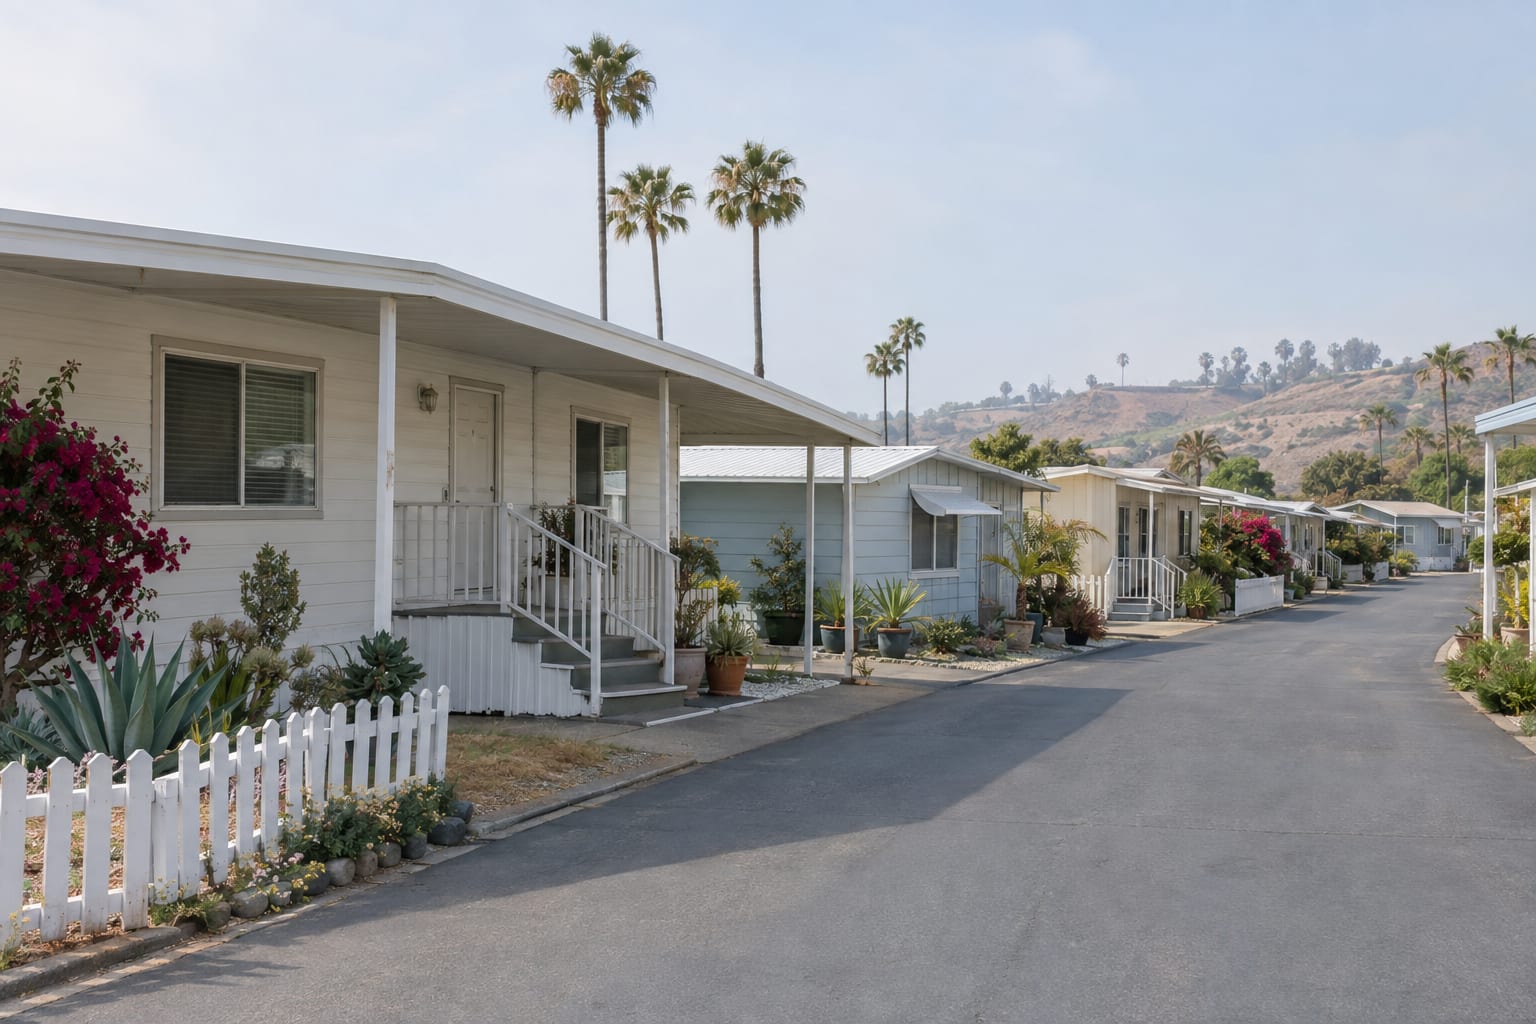
The Inland Empire and the deserts: communities and owned lots side by side
Riverside and San Bernardino counties offer both setups. There are land-lease communities in the valleys, some of them age-restricted, and homes on their own lots toward the edges and in the High Desert. Summers are hot, so cooling belongs in the monthly budget, and in the High Desert so does winter heating.
In the Coachella Valley and other resort areas, some owners live in their homes for only part of the year. If that is your plan, say so at the start. Many programs and communities require owner-occupancy, so ask whether financing is available for your intended use before you buy.
Local pages: Riverside, Palm Springs and Victorville.
The Central Valley: city communities and rural parcels
From Bakersfield north to Sacramento, the cities have communities and the counties around them have homes on rural parcels. A rural parcel brings things into the purchase that a community home never raises: a well, a septic system, propane and sometimes a private road.
If the home is on a foundation on land the owner also owns, expect to hear about a 433A. In California, HCD Form 433A is used to report the installation of a manufactured home on a foundation system and is recorded with the county when applicable. It is an important property record, but it does not by itself guarantee financing. What a 433A is explains the form.
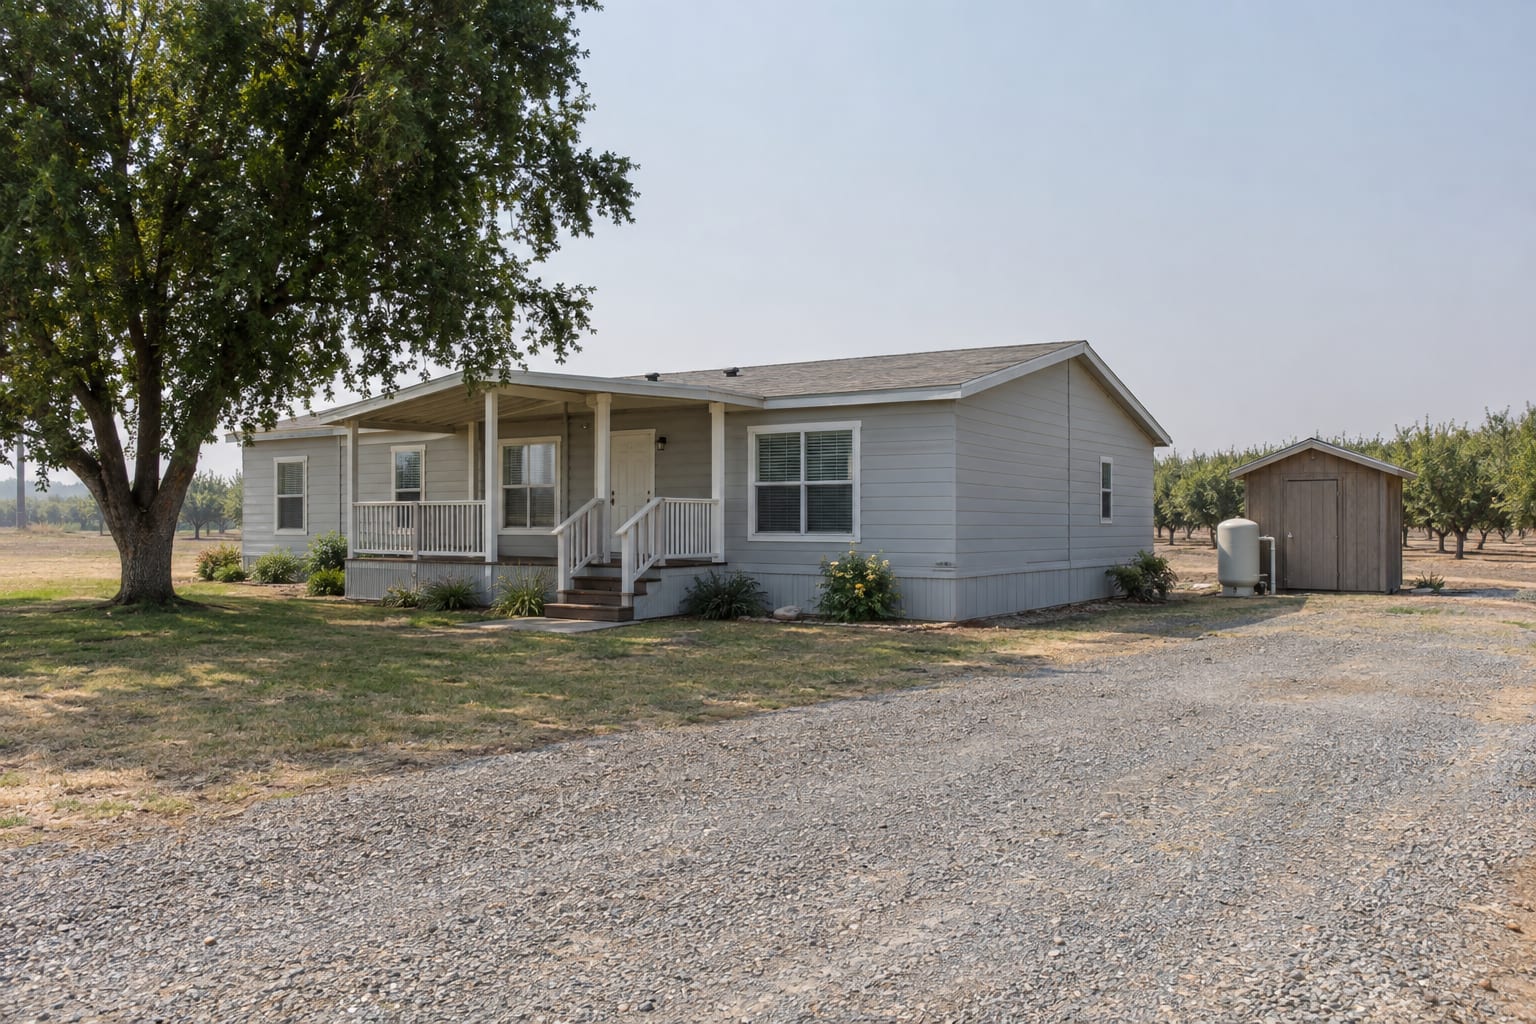
Low ground near the rivers and the Delta can sit in a mapped flood zone, so look up the address on FEMA’s flood map before you make an offer. Our list of California cities where manufactured homes are still affordable goes through several valley cities one by one.
Local pages: Bakersfield, Fresno and Sacramento.
The Bay Area and North Bay: rented spaces where land is expensive
Around San Jose and the rest of the Bay Area, manufactured homes are again mostly in communities on leased land, and the questions are the coastal ones: the space rent in writing, and whether a local ordinance applies to the space.
North of the bay, add wildfire. Look up the address on CAL FIRE’s fire hazard severity zone map and get a quote for manufactured home insurance before you make an offer, because the cost and availability of coverage can change the whole budget.
Local pages: San Jose and Santa Rosa.
The foothills and mountains: owned land, fire zones and snow
In the Sierra foothills, the mountain towns of Southern California and the far north of the state, manufactured homes are more often on land the owner also owns. Three checks come first.
- Wildfire. The same CAL FIRE map and insurance quote, before anything else.
- Roof load. The home’s data plate lists the wind, thermal and roof-load zones it was built for. HUD’s guidance is that a manufactured home should never be placed in a more restrictive zone than the one it was built for. In snow country, ask the county building department what applies at that elevation.
- Access and utilities. Propane, a well, a septic system, a private road, and who clears that road in winter.
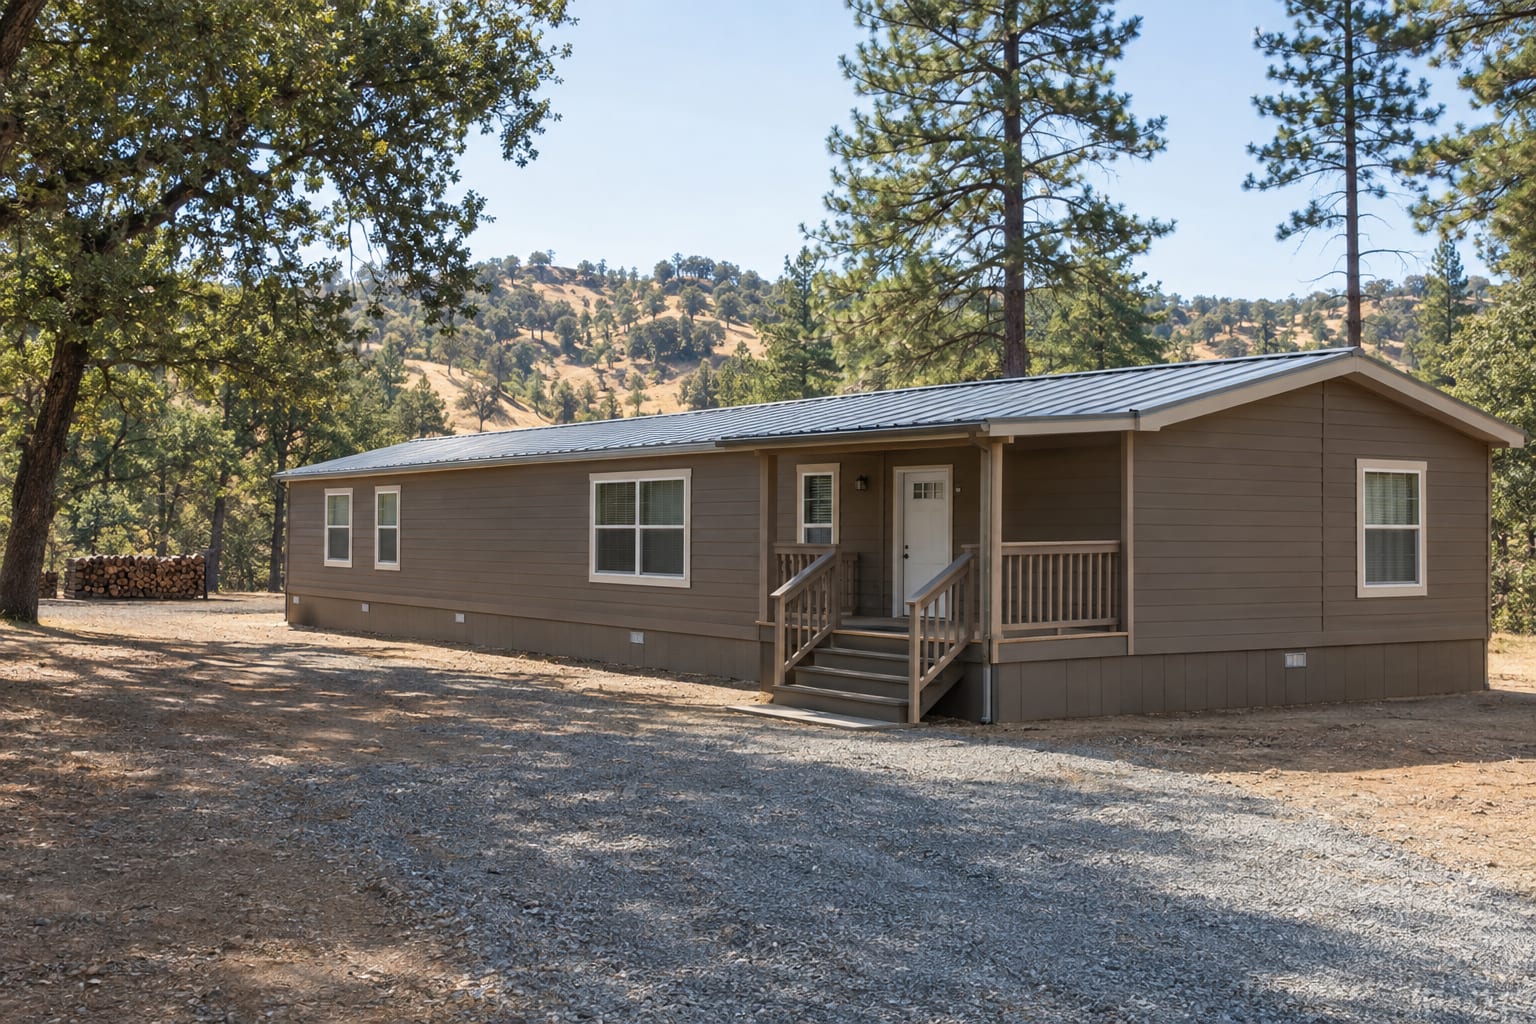
There are no city pages for these areas, and none is needed. Santiago Financial, Inc. finances manufactured homes in all 58 California counties, as financing a manufactured home anywhere in California or Arizona explains. All financing is subject to credit approval, and not every home or applicant qualifies.
Choose on monthly cost first, then on the setup
Compare regions on the full monthly cost of living there, then settle the setup: rented space or owned land. If you are not sure which loan your situation points to, find your financing path narrows it down in three questions, and the full list of California city pages has local detail for the places not named here.
Local ordinances and hazard maps change, so confirm the current details with the city, county or agency. This article is general information, not legal advice.