
Manufactured Home Purchase Loans
Finance a manufactured or mobile home in California or Arizona with a plan built around the home, the land beneath it, and your complete monthly budget.
Manufactured home purchase financing is shaped by more than the home’s price. The first decision is whether you are buying a home in a land-lease community, a home already installed on owned land, or a home and land project. Each path has different documents, third parties, monthly costs, and timing.
Santiago Financial, Inc. has focused on manufactured housing for over 50 years. We help buyers and their dealers, agents, sellers, communities, escrow teams, and insurers coordinate the financing side of a California or Arizona purchase. Start by estimating the complete monthly cost or beginning the application. Programs and terms are subject to current guidelines and credit approval.
Down payment varies
There is no single down payment for manufactured homes. It depends on the program, your credit, the home, and whether the land is leased or owned.
Two approvals for a home in a community
If the home is in a park or land-lease community, the community reviews you as a resident and the lender reviews the loan. They are separate reviews, and closing needs both.
Available terms depend on borrower qualifications, property type, loan amount, state, and lender guidelines. Programs may vary. Every application is reviewed individually; all financing is subject to credit approval, and not all applicants qualify.
Compare total housing cost, not only the sale price
Two homes with the same price can create very different monthly budgets.
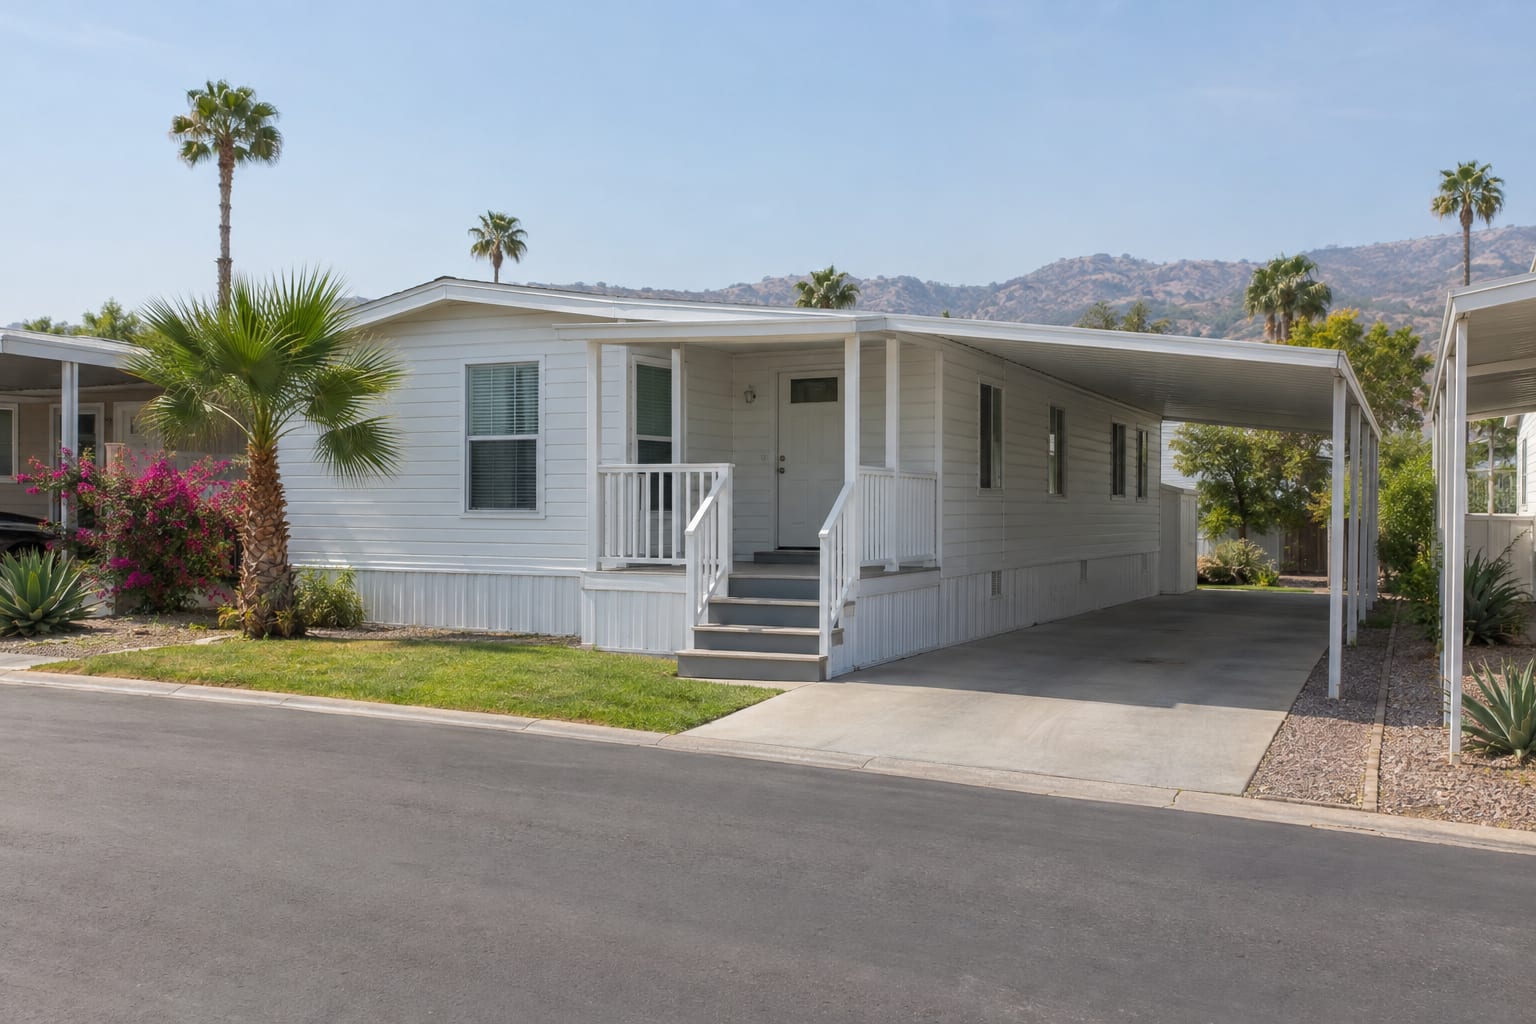
For a home in a community
Add the estimated loan payment to space rent, property taxes or registration-related charges as applicable, insurance, utilities, community fees, and a maintenance reserve. Ask how often rent can change, what services are included, whether the community has age or occupancy rules, and what approval standards apply.
For a home on owned land
Review the land title, whether the home is treated as personal or real property, foundation or affixture records, utilities, private-road or access issues, well or septic details where relevant, taxes, insurance, and any planned site work. These items affect both financing and long-term ownership cost.
Home in a community
- Loan payment
- Space rent
- Insurance
- Utilities
- Community fees
- Taxes or registration charges
- Maintenance reserve
Home on owned land
- Loan payment
- Property taxes
- Insurance
- Utilities
- Road, well or septic upkeep
- Maintenance reserve
The layers are not to scale. The loan payment is one of them; what the others add depends on the home, the community or the land, and the program. The payment calculator lets you enter each one. Its results are educational estimates, not a loan offer.
Our space-rent affordability guide and leased-land buyer checklist can help you compare choices before signing a purchase agreement. For every step in order, from choosing a home to getting the keys, read how to buy a mobile or manufactured home.
From an early estimate to closing
- 1
Define the full budget
Estimate the loan payment and add space rent, taxes, insurance, utilities, and community charges that may apply.
- 2
Get pre-qualified
Review an initial financing range before committing to a home. Pre-qualification is not final approval.
- 3
Confirm the home and land setup
Identify the home year, title, location, community terms or land ownership, and any seller payoff.
- 4
Coordinate approval and closing
Complete lender conditions, value review, title and escrow work, insurance, and community approval when applicable. Do not schedule the move until closing is confirmed.
Timelines vary by borrower, property, title status, community, escrow, appraisal or value review, insurance, and other parties. What happens after you apply, stage by stage, is on how the loan process works.
Home-only financing vs. financing the home with land
You will hear a home-only loan called a “chattel” loan. The difference is not just paperwork — it changes what secures the loan, how long you can take to repay it, and what you build equity in.
| How they differ | Home-only (chattel) | Home and land together |
|---|---|---|
| What secures the loan | The home itself. Common when the homesite is leased from a community. | The home and the real property together. |
| How the home is treated | Usually personal property, with its own title or registration. | Usually real property once it is permanently affixed and recorded. |
| Do you need to own land? | No. This is the route for homes on leased land. | Yes, either already owned or purchased in the same transaction. |
| Repayment period | Generally shorter than a comparable real-property loan. | Generally longer, which usually means a lower payment for the same amount borrowed. |
| Pricing | Typically priced higher than comparable real-property financing, reflecting the different collateral. | Typically priced more like other real-estate lending. |
| What you build equity in | The home only. The land stays with the community. | The home and the land. |
| Closing | Fewer moving parts, since there is no land title work. | Adds land title, appraisal of home and land, and usually escrow — so it takes longer. |
A general orientation, not a description of any specific program. Which structure fits depends on the home, the land, how the home is titled, and current guidelines. All financing is subject to credit approval.
Neither structure is better in the abstract. For many buyers the practical question is not which loan type is superior, but which one matches the home they actually want — and for a home in a community, home-only financing is what makes the purchase possible at all.
Estimate your monthly payment
Try our manufactured & mobile home loan calculator — adjust price, down payment, term, taxes, and space rent to see an estimated monthly payment. Estimates are for educational purposes; all financing is subject to credit approval.
Frequently asked questions
Can I buy a manufactured home in a park with a loan?
Financing may be available for a home in a land-lease community. The home is financed separately from the leased homesite, and the community commonly has its own resident-approval process. Loan approval does not replace community approval.
Can I buy a manufactured home and land together?
Yes, some transactions finance a manufactured home together with owned land. The loan structure depends on whether the home is already installed or will be placed after closing, how title and affixture are handled, the site, and current program guidelines.
How much down payment is required for a manufactured home?
The required down payment varies by program, borrower qualifications, home, land status, purchase price, and loan amount. Rather than relying on a single percentage, request a current estimate for the exact property setup you are considering.
What should I include in my monthly manufactured home budget?
Start with principal and interest, then account for space rent if the home is in a community, property taxes, insurance, utilities, community fees, and a maintenance reserve. The home with the lowest price is not always the one with the lowest total monthly cost.
Can I finance a manufactured home bought from a private seller or family member?
Potentially. Private-party and family transactions need a clear purchase agreement, title and lien review, seller identity and payoff information where applicable, value support, and an independent review under current lender guidelines.
What is the difference between pre-qualification and final approval?
Pre-qualification is an early review based on the information available at that time. Final approval requires verification of borrower information, an acceptable home and transaction, value and title work, and satisfaction of all applicable conditions. All financing is subject to credit approval.
Ready to buy your manufactured home?
Start online, by phone, or with a printable application. A specialist reviews the home, where it sits, and your situation together, then tells you what is needed next. No obligation; subject to credit approval.