Buying a Manufactured Home in Phoenix, Arizona: Where to Start
Local financing details: Mobile Home Loans in Phoenix
To buy a manufactured home in Phoenix, start with where the home will sit, not with the home. Whether it is on a rented space in a community or on land you own decides which kind of loan applies, what you pay each month besides the loan, and whose approval you need. Settle that, choose the part of the Valley, and get the monthly costs in writing before you make an offer.
This page is the short version. Each decision below links to a longer guide, and the Phoenix manufactured home loans page covers the financing itself.
Three decisions to make before you choose a home
The decisions, and where to read more about each
| Decision | Why it comes early | The longer guide |
|---|---|---|
| A community or your own land | It sets the type of loan, the monthly costs and the paperwork | Park or land in Phoenix |
| Phoenix or another Valley city | The mix of homes, the drive, and the city and county offices you deal with all change | Phoenix or a nearby suburb |
| How much space rent you can carry | In a community, rent is paid on top of the loan and is counted in the lender’s review | Comparing space rent near Phoenix |
The order matters. A buyer who picks a home first often learns about the rent, the age rule or the status of the land afterward, when changing course costs more.
What is different about buying in Arizona
A manufactured home here starts out as personal property with its own title, the way a vehicle has one. Arizona titles are issued by the MVD, the Motor Vehicle Division of the Arizona Department of Transportation, generally one title per section. A double-wide therefore usually has two.
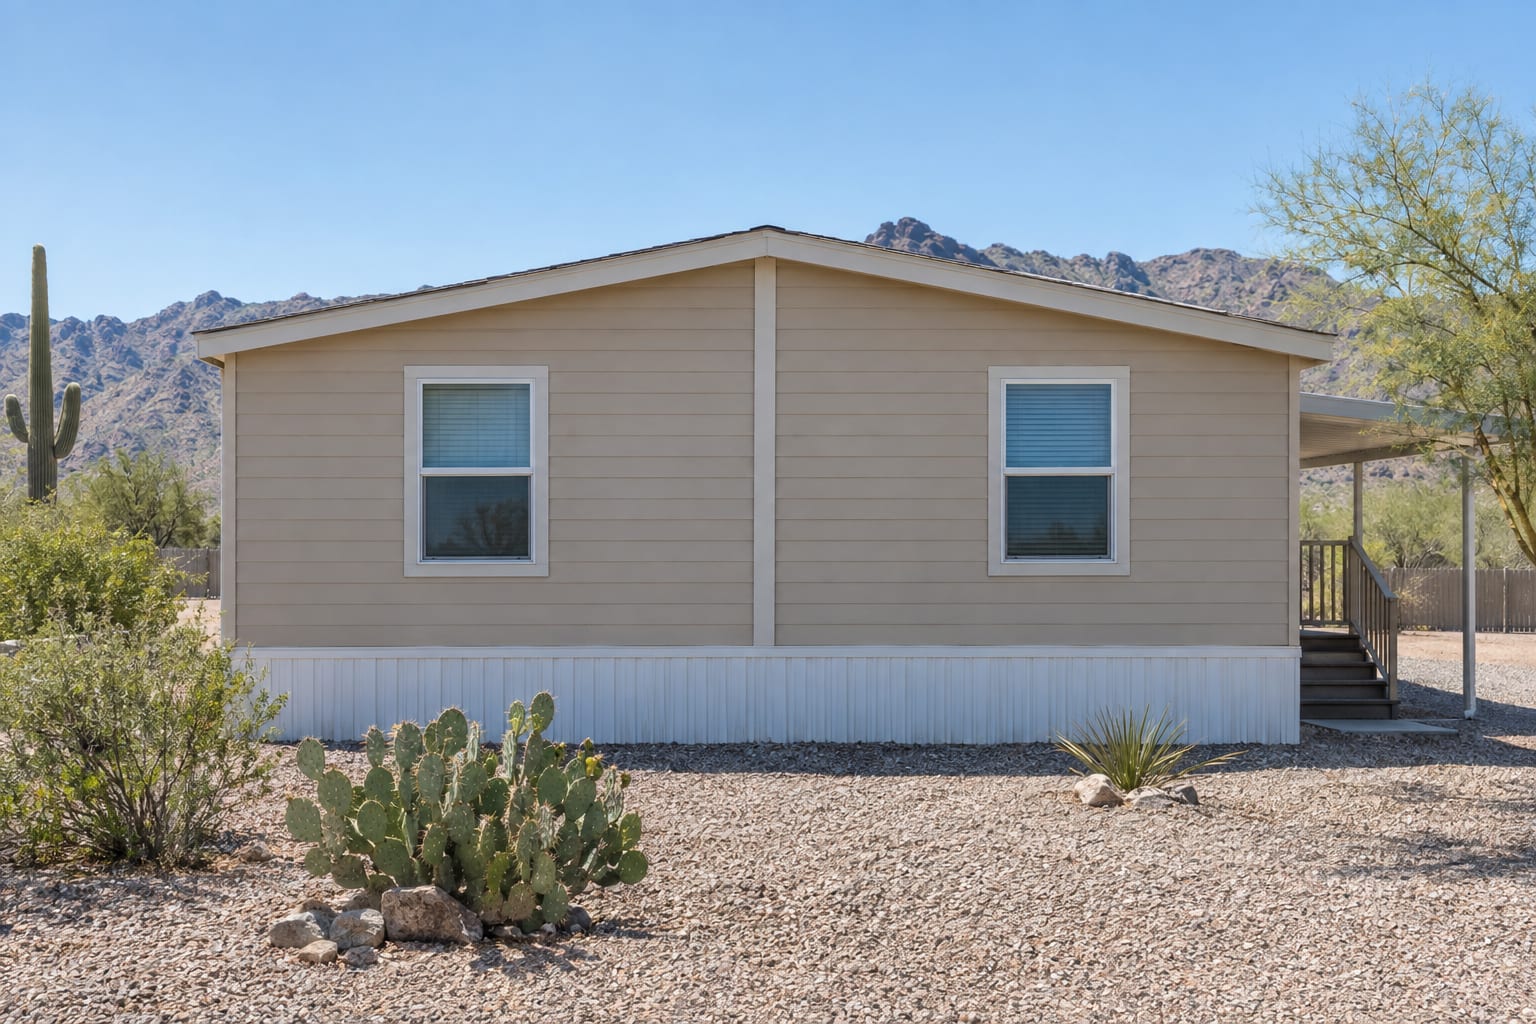
A home in a community stays personal property and is financed by itself, with what lenders call a home-only or chattel loan. A home permanently attached to land its owner also owns can become real property through an Affidavit of Affixture recorded with the county, and then the home and land can often be financed together.
Arizona title basics explains both records and what a lender looks for in each. The MVD describes its side on its mobile home ownership page. This is general information, not legal or tax advice.
What to have ready before you call a lender
A first conversation goes further when you can describe the property as well as yourself.
There is no single down payment or credit requirement to plan around. Both depend on the program, your credit, the home, and whether the land is leased or owned. A pre-qualification gives you an early read on what range may be realistic. It is not final approval, and all financing is subject to credit approval.
Santiago Financial, Inc. finances only manufactured homes, with more than 50 years in manufactured home lending and now serving buyers across Arizona. Once you have the basics above, talk with a specialist about which path fits the home you have in mind.