
Manufactured Home Refinance Programs
Review your payment, term, equity, and long-term cost with a lender that understands manufactured homes in communities and on owned land.
A manufactured home refinance replaces an existing obligation with a new loan. The goal may be a different payment or term, access to eligible equity, removal or addition of a borrower, or a cleaner financing structure after a title or ownership change. Whether the refinance is worthwhile depends on the complete new loan, not a single advertised rate or payment.
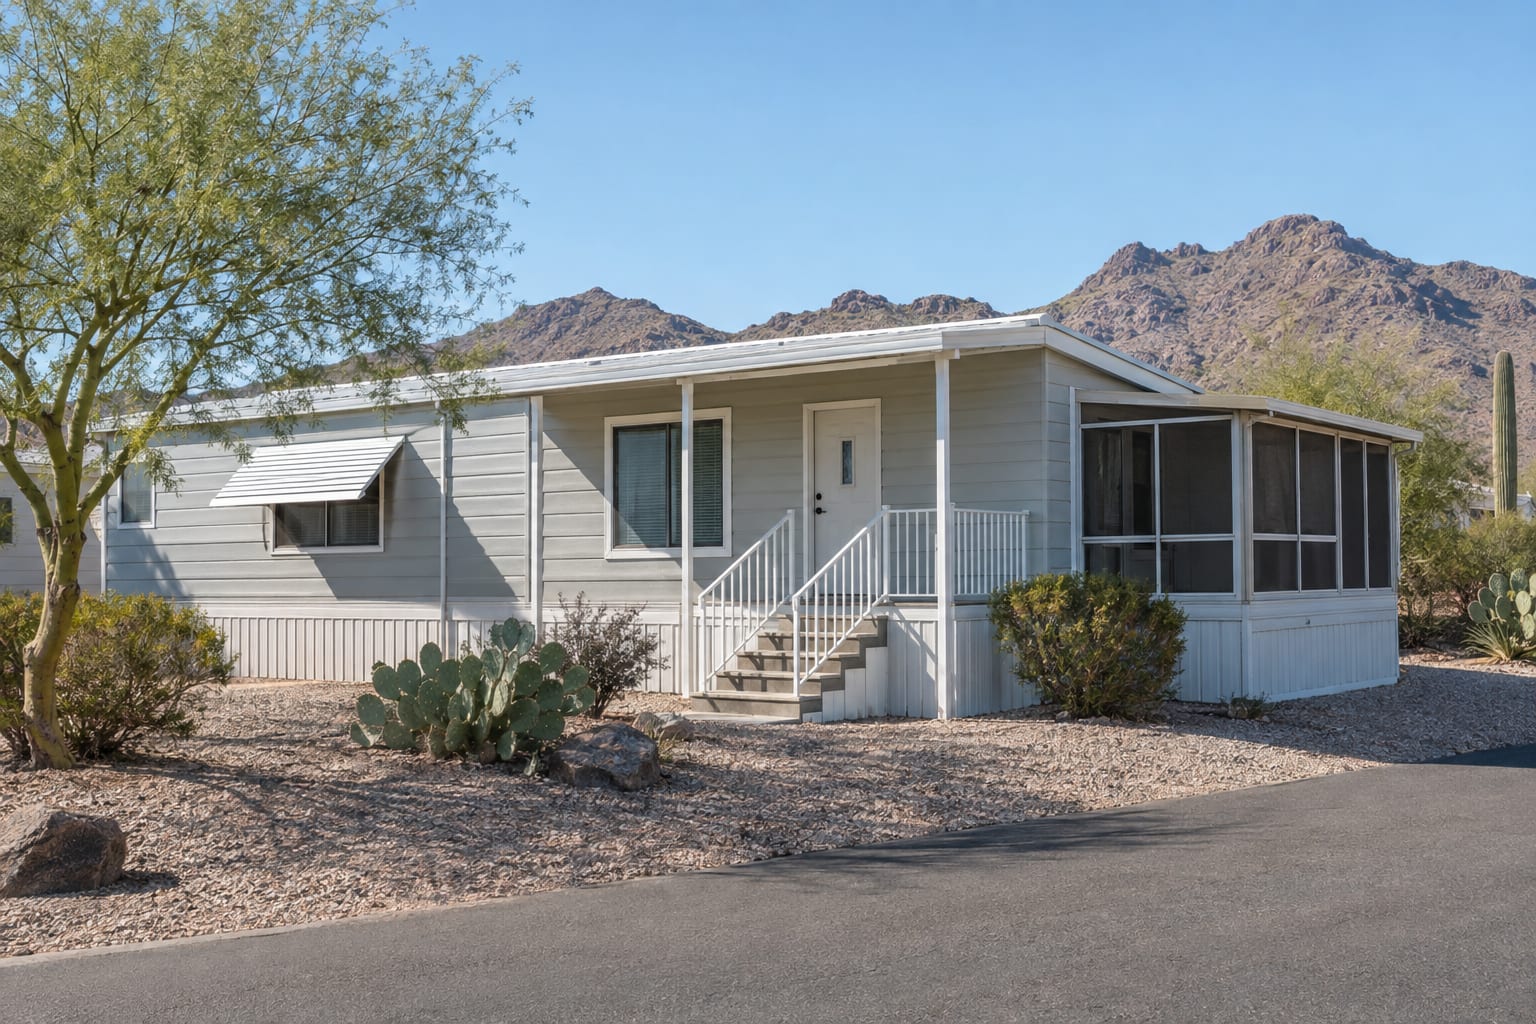
The property setup matters. A home in a land-lease community may be financed as the home itself, while a home attached to owned land may involve real-property, foundation, and affixture records. Santiago Financial, Inc. has worked in manufactured housing for over 50 years and serves eligible California and Arizona homeowners. Estimate a new payment, then request a personalized review.
Refinance goals
Could a new loan cost less overall?
Ask whether a refinance could lower your monthly payment or shorten your loan term. Whether it costs less overall depends on the complete new loan, which the decision guide below walks through.
Change your loan term
A shorter term pays the balance down sooner; a longer one can lower the payment while interest accrues for longer. Either way, compare the total cost, not only the payment.
Cash-out refinance where eligible
Cash-out options may be available when equity, the property, title, the requested loan amount, and program guidelines support them. Cash out is not guaranteed.
Change who is on the loan or the title
Some owners refinance to add or remove a borrower, or to put the financing in order after a title or ownership change. The home, the land status, and current guidelines decide what is possible.
Information, rates, and programs are subject to change without notice. All products are subject to credit approval. Other restrictions may apply. Not all customers will qualify. Product availability varies based on loan amount and state.
Look beyond the new monthly payment
A lower payment can come from a lower rate, a longer repayment period, a lower balance, or a combination of those factors. Extending the term can reduce the payment while increasing the time interest accrues. A responsible comparison includes:
- current balance, rate, payment, and remaining term;
- estimated new balance, rate, payment, and term;
- all closing costs and whether any costs are added to the loan;
- cash received, cash contributed, or debts paid through the transaction;
- the time needed for monthly savings to recover the cost of refinancing; and
- how long you expect to keep the home and the new loan.
A refinance can still serve a valid goal even when the monthly payment is not the only benefit. The key is understanding the tradeoff before you commit.
Title, value, home condition, and land status can affect eligibility
Home and title
The year, manufacturer, section count, serial information, condition, current title or registration, ownership, and existing liens help define the collateral and available path.
Community home
For a home on leased land, the file may need community details, space-rent information, residency or occupancy confirmation, and other documents required under the applicable program.
Owned-land home
Land records, affixture or foundation documents, taxes, insurance, utilities, access, and an appraisal of the real property may be relevant when the home and land are treated together.
For title questions, use the official California HCD registration and titling resources or Arizona MVD mobile home ownership guidance. Agency requirements and forms can change.
Estimate your monthly payment
Try our manufactured & mobile home loan calculator — adjust price, down payment, term, taxes, and space rent to see an estimated monthly payment. Estimates are for educational purposes; all financing is subject to credit approval.
Frequently asked questions
Can I refinance a mobile or manufactured home in a park?
Refinance options may be available for eligible homes in land-lease communities. The lender reviews the borrower, home, title, value, current loan, loan amount, community, and current program guidelines. Community documents or confirmation may also be needed.
Can I refinance a manufactured home on owned land?
Potentially. Owned-land refinances may require land records, title or affixture information, foundation details, insurance, taxes, value documentation, and confirmation of existing liens. The appropriate structure depends on how the home and land are legally treated.
How do I know if refinancing makes financial sense?
Compare the estimated monthly savings or other benefit with all closing costs and the time you expect to keep the new loan. Also compare the remaining term, total interest over time, cash received or contributed, and whether the new loan changes how quickly the balance is paid down.
Can I get cash out when I refinance?
Cash-out refinance options may be available when eligibility, equity, property, title, requested loan amount, and program guidelines support them. Cash out is not guaranteed, and the new balance and payment should be reviewed carefully.
What documents are commonly needed for a manufactured home refinance?
Common starting items include identification, income and asset documents, a current loan statement or payoff information, proof of insurance, home title or registration details, property or community information, and tax or land records where applicable. The final list varies by transaction.
Where does Santiago Financial offer manufactured home refinancing?
Santiago Financial, Inc. currently arranges manufactured and mobile home refinancing in California and Arizona only. All financing is subject to credit approval and current program availability.
Thinking about refinancing your home?
Talk with a specialist about refinancing a manufactured or mobile home in California or Arizona. Have your current loan statement handy if you can. No obligation; subject to credit approval.