Mobile & Manufactured Home Loans in California
Purchase or refinance a manufactured or mobile home anywhere in California, in a land-lease community or on owned land, with a specialist focused on manufactured housing.

Financing is available in all 58 California counties.
You don’t need to find your city below. The guides on this page cover specific areas in more detail, but financing is available statewide, in communities and on owned land. If your city isn’t listed, just ask.
In California, the first question about any manufactured home loan is who owns the land under the home. In a land-lease community you buy the home and rent the space, so the loan covers the home alone and space rent is paid on top of it. On land you own or are buying, a home attached to a foundation system can be financed together with the land as real property, which brings land title, foundation records and a combined appraisal into the file.
Santiago Financial, Inc. helps California buyers and homeowners with purchase financing, refinance options and land-and-home transactions, and coordinates with dealers, agents, sellers, communities, escrow companies, insurers and valuation providers along the way. Available terms depend on borrower qualifications, property type, loan amount, state, and lender guidelines. All financing is subject to credit approval.
Not sure which path describes your home? Find your financing path, or read how the loan process works before you apply.
What makes a California manufactured home file different?
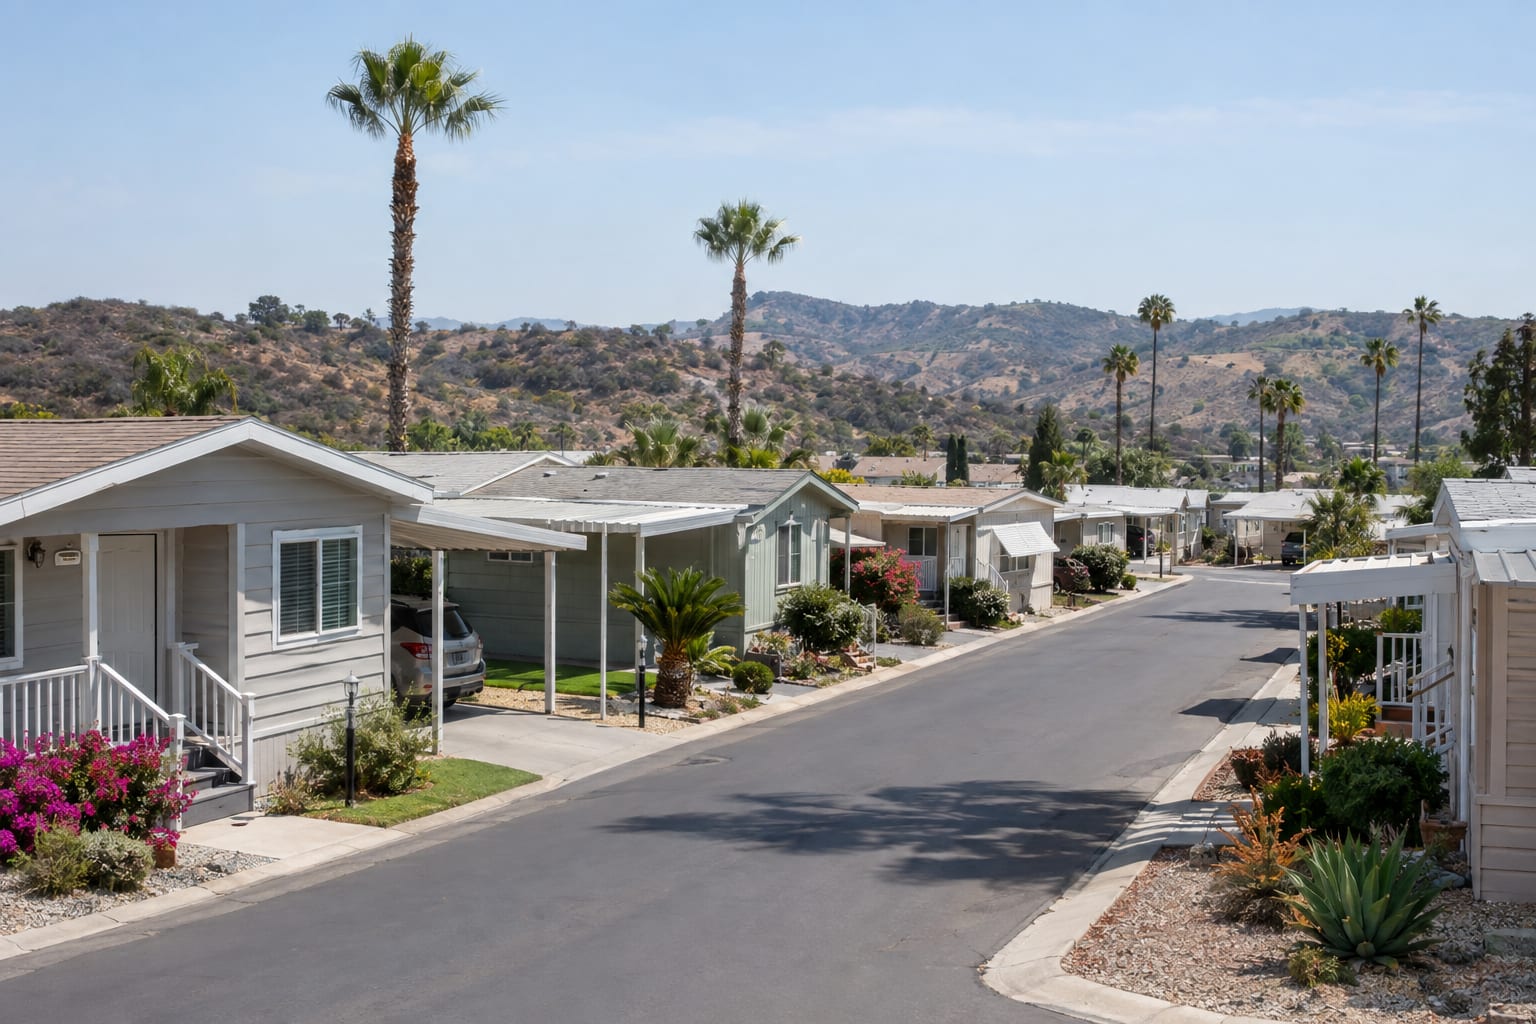
Community homes and space rent
For a home in a land-lease community, budget for the loan payment and space rent separately: the lender compares your income with the full monthly housing cost, including space rent. Community resident approval and lender approval are separate reviews; one does not replace or guarantee the other. Before committing, read the lease and the rules, and ask about utilities, fees, age or occupancy restrictions and how rent changes are handled.
California title and registration
California titles and registers manufactured homes through HCD (the Department of Housing and Community Development), not the DMV. HCD’s Registration and Titling Program issues the title and registration documents for new and resold homes and processes transfers. A transfer goes smoothly when the records line up:
- the registered owner is the seller, with lien releases for any paid-off loan;
- the serial number on the title matches the home’s data plate;
- property taxes or the in-lieu fee are current, so HCD can issue or accept the tax clearance it asks for;
- the transfer documents are completed and signed for the tax system the home is on.
Homes on a foundation or owned land
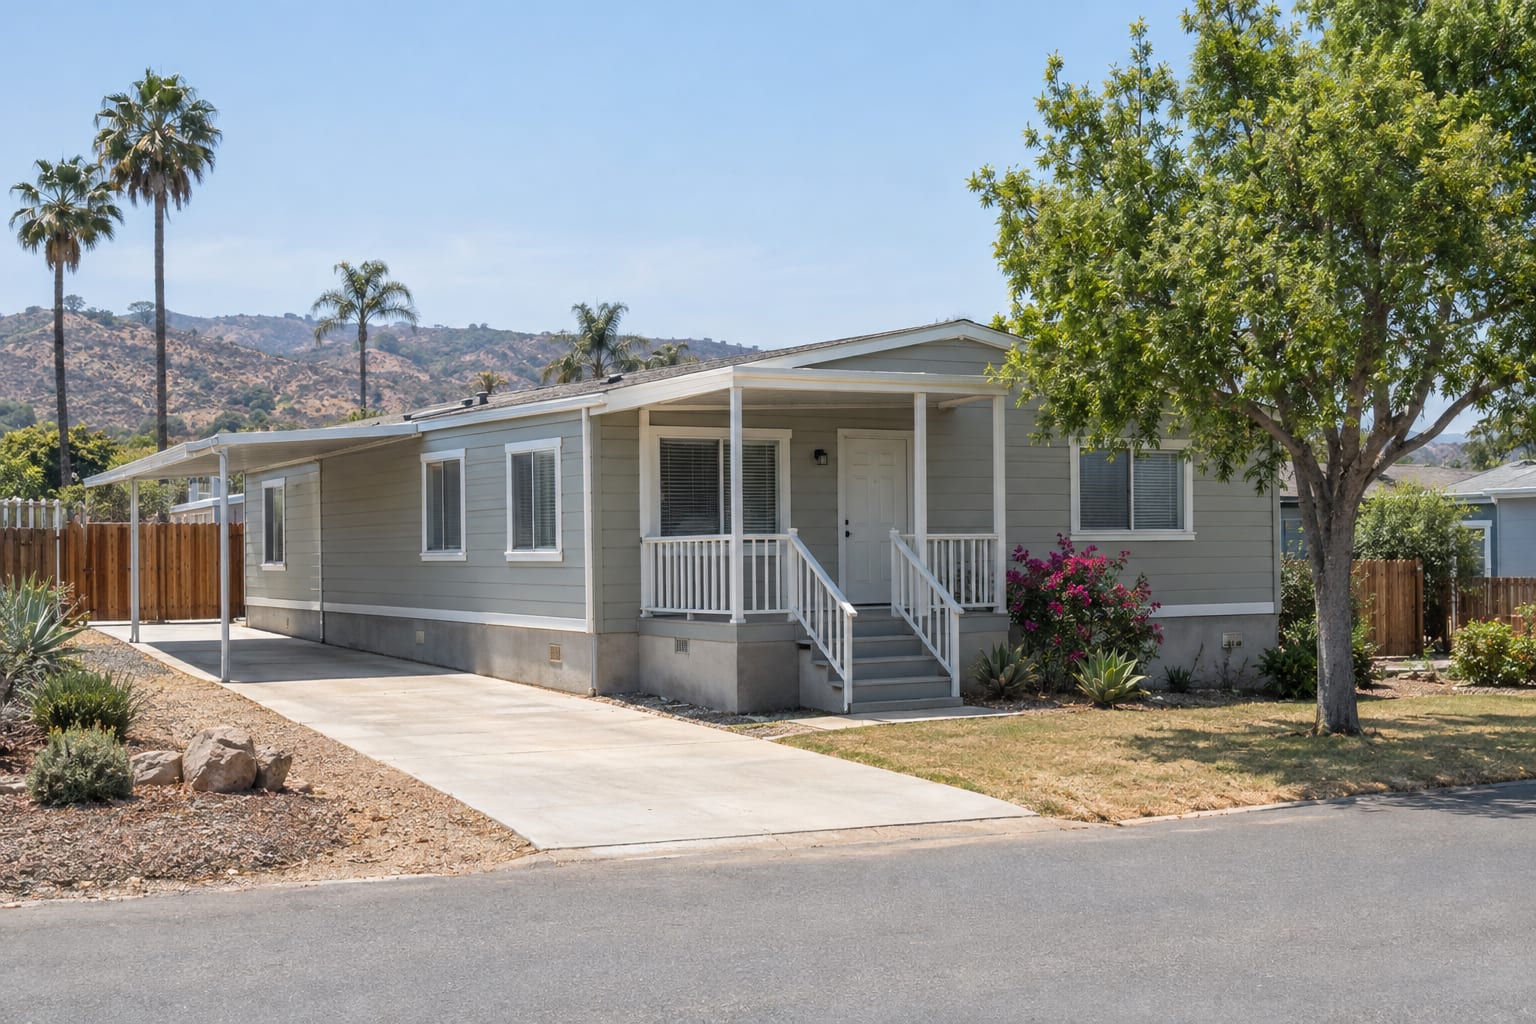
When a home is installed on a foundation system on land you own, HCD Form 433A is used to report the installation and is recorded with the county when applicable. Once the home is on an approved permanent foundation, the county assesses the home and the land together as real property, and the loan can cover both. The file then also includes the land title, an appraisal of home and land, taxes, insurance, utilities, access and local records. A 433A is an important property record, but it does not by itself guarantee financing: the complete property and the current program still have to qualify.
California rules that affect your budget
Beyond the loan payment, much of the monthly cost of a California manufactured home comes down to how space rent is set, how the home is taxed, and the hazards where it sits. This is general information, not legal or tax advice; confirm the details for the home you are considering with the county and the community.
Space rent, the Mobilehome Residency Law and local rent ordinances
Space rent is a lease payment to the community, set under your rental agreement and governed by California’s Mobilehome Residency Law. HCD’s Mobilehome Residency Law Protection Program helps resolve certain disputes between homeowners in mobilehome parks and park management.
Some cities and counties also have a mobilehome space-rent ordinance; many do not. The city guides say which applies where: for example, Santa Ana, Riverside, Santa Rosa, Salinas, Fresno and Santa Clarita each have one, while the guides for Bakersfield, Sacramento and Stockton found none published. An ordinance never sets your rent for you: ask the community for its current rent and fee schedule, and read how space rent affects what you can afford before you compare homes.
Local property tax or HCD’s in-lieu fee
A manufactured home sold new on or after July 1, 1980 is on local property tax, billed by the county like any other home. Many older homes instead pay HCD a yearly in-lieu fee with their registration renewal. An owner can ask HCD and the county assessor to convert an older home to local property tax, but once converted it cannot go back (California State Board of Equalization).
Ask the seller which system the home is on and whether it is paid up. HCD’s transfer forms differ by system, and a home on local property tax generally needs a tax clearance certificate from the county tax collector before HCD transfers the title. The assessor and tax collector of the county where the home sits hold the records.
Community home compared with a home on owned land in California
| What differs | Home in a land-lease community | Home affixed to land you own |
|---|---|---|
| What the loan covers | The home alone (a home-only, or chattel, loan) | The home and the land together |
| Title record | HCD title and registration | Land title at the county recorder, with HCD Form 433A recorded for the foundation installation |
| Property tax | Local property tax, or HCD’s in-lieu fee on many older homes | Local property tax on home and land as real property |
| Paid on top of the loan | Space rent, insurance, utilities, community fees | Property taxes and insurance; well, septic or propane where rural |
| Separate reviews | Community resident approval | Local permits and foundation records |
| What the appraisal covers | The home, supported by comparable sales | The home and the land |
A home on land you own that is not on a foundation system is still titled through HCD as personal property; the owned-land column describes an affixed home.
Location hazards that change the insurance and the inspection
Where the home sits changes what the insurer and the inspector will ask for, and insurance is part of the monthly cost the lender reviews.
California manufactured home loan guides by area
Orange County
Mostly land-lease communities, so space rent, the lease and community approval lead the file; whether the park sits in a city with a rent ordinance is the first local question.
Inland Empire
Both paths are common: parks under city rent programs and homes on owned lots, with fire-zone, fault and wind checks where the valleys meet the mountains.
San Diego County
City rent review ordinances in several cities, salt air and flood maps near the bay and the beaches, and canyon fire zones inland.
Los Angeles & South Bay
Which jurisdiction’s rent rules reach a park matters here: the City of Los Angeles applies its Rent Stabilization Ordinance to park spaces, the county’s ordinance covers unincorporated areas, and several cities have their own.
Coachella Valley
Rented spaces, owned lots and Indian lease land each produce a different loan file, and desert heat puts the cooling system at the center of the inspection.
High Desert
More homes on their own parcels, often with wells, septic and propane; heat, cold and wind make the data plate’s zones and the home’s condition part of the file.
Central Valley
Owned lots and parks both; levee-protected flood zones, the county tax clearance at transfer and summer heat come up in most files, and some cities have rent programs while others do not.
Bay Area & North Coast
City and county mobilehome rent rules, Fire Hazard Severity Zones after the Tubbs Fire, creek flood maps and earthquake bracing.
Central Coast
In Salinas: the city’s rent stabilization rule, Salinas River flood maps, seasonal income records and Monterey County title steps.
Don’t see your city? Financing is available throughout California. Ask us about your area →
Estimate your monthly payment
Try our manufactured & mobile home loan calculator — adjust price, down payment, term, taxes, and space rent to see an estimated monthly payment. Estimates are for educational purposes; all financing is subject to credit approval.
Frequently asked questions
Does Santiago Financial offer manufactured home loans throughout California?
Santiago Financial, Inc. currently arranges manufactured and mobile home financing throughout California. The city guides on this page provide local detail, but your city does not need to be listed for you to contact us. All financing is subject to credit approval and current program availability.
Can I finance a manufactured home in a California mobilehome park?
Financing may be available for eligible homes in land-lease communities. The home loan and the community’s resident approval are separate reviews, and space rent is paid separately from the loan payment. The borrower, home, community, loan amount, and current program guidelines all matter.
Can I finance a manufactured home on owned land in California?
Potentially. Owned-land transactions may require land records, title and registration information, foundation or affixture documentation such as an applicable recorded 433A, utilities, access, insurance, taxes, and an appraisal. The exact structure depends on the property and program.
Who handles manufactured home title and registration in California?
The California Department of Housing and Community Development Registration and Titling Program provides title and registration documents and processes transfers for manufactured homes and mobilehomes. A lender, escrow company, dealer, or agent may coordinate with HCD as part of a transaction.
What costs should I include when buying a California community home?
In addition to the estimated loan payment, review space rent, utilities, insurance, taxes or registration-related charges as applicable, community fees, possible rent increases, and maintenance. Compare the complete monthly housing cost before choosing a home.
Can I refinance a California manufactured home?
Refinance options may be available for eligible community homes and owned-land homes. Current balance, requested loan amount, equity, title, home age and condition, location, credit, income, and program guidelines affect availability.
Looking for a mobile home loan in California?
Tell us the city and whether the home is in a community or on land you own, and a specialist will explain what the California file needs. Start online, by phone, or with a printable application. All financing is subject to credit approval.