
Mobile & Manufactured Home Loans in Arizona
Purchase or refinance a manufactured or mobile home anywhere in Arizona, in a land-lease community or on owned land, with a specialist focused on manufactured housing.

Financing is available in all 15 Arizona counties.
You don’t need to find your city below. The guides on this page cover specific areas in more detail, but financing is available statewide, in communities and on owned land. If your city isn’t listed, just ask.
Arizona has a wide mix of manufactured housing: age-qualified and all-age land-lease communities, park models in some of them (which follow different rules), homes on privately owned desert and rural parcels, and homes that have been permanently affixed to real estate with an Affidavit of Affixture. The right financing path depends on which of those describes the home, and the first question is always who owns the land under it.
Santiago Financial, Inc. has more than 50 years in manufactured home lending, now serving buyers across Arizona with purchase financing, refinance options and land-and-home transactions, and coordinates with dealers, agents, sellers, communities, escrow companies, insurers and valuation providers along the way. Available terms depend on borrower qualifications, property type, loan amount, state, and lender guidelines. All financing is subject to credit approval.
Not sure which path describes your home? Find your financing path, or read how the loan process works before you apply.
What makes an Arizona manufactured home file different?
Community homes and the complete monthly cost
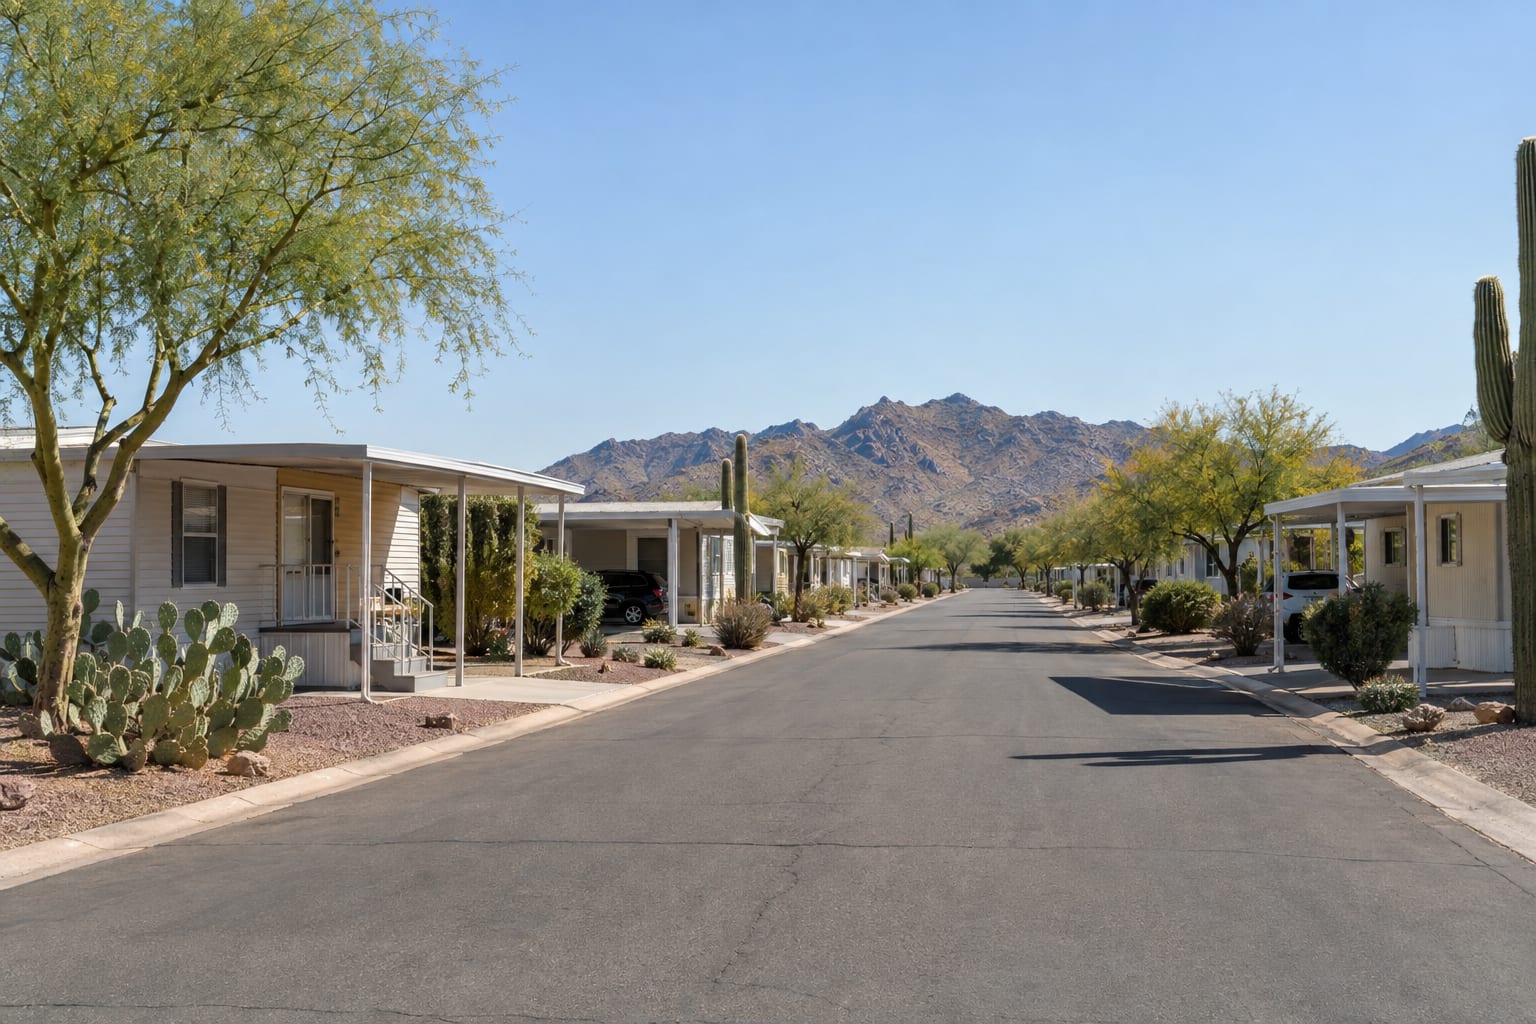
When you buy a home in a land-lease community, the loan finances the home while the homesite is rented separately. The lender compares your income with the full monthly housing cost, so add space rent, insurance, utilities, community fees, applicable taxes and a maintenance reserve to the estimated loan payment. Community approval and lender approval are separate reviews; one does not replace or guarantee the other.
Arizona titles and multi-section homes
Arizona titles are handled by the MVD (ADOT Motor Vehicle Division), generally one title per section, so a double-section home can involve two titles. Before a home is sold or refinanced, the records need to line up:
- the owner on each title is the seller, with lien releases for any paid-off loan;
- the serial numbers on the titles match the home’s data plate;
- county personal-property taxes are current (see below);
- the transfer documents are signed for every section.
Affixed homes on owned land
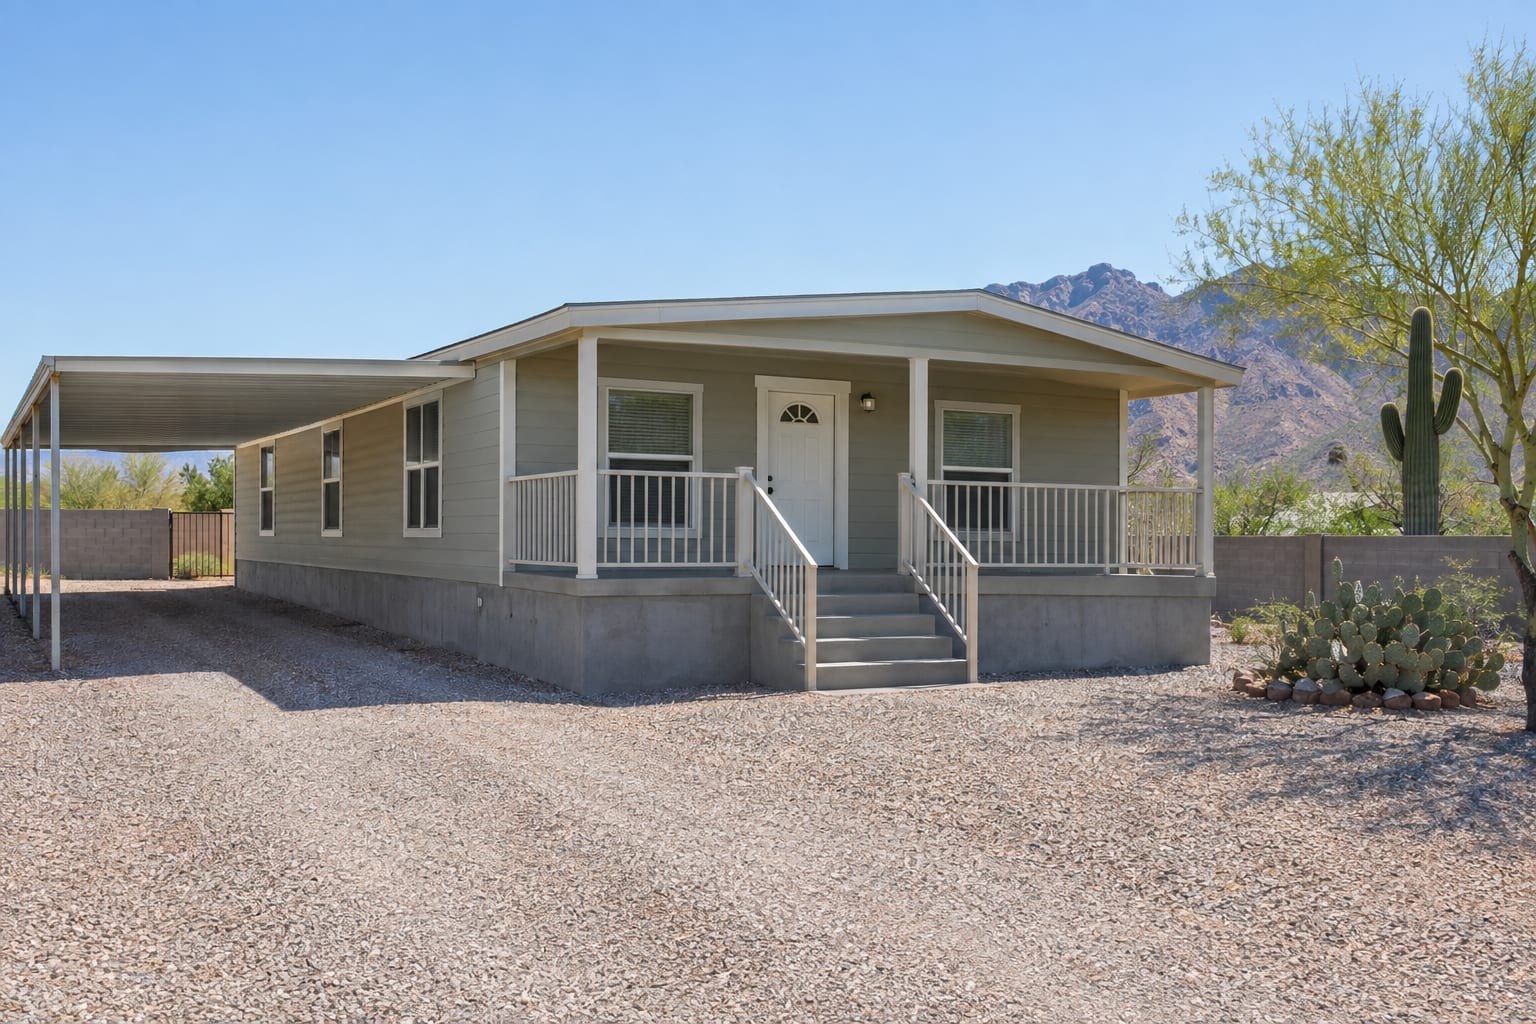
For an eligible Arizona mobile home permanently attached to real property owned by the homeowner, the Affidavit of Affixture process generally involves surrendering the MVD title and recording the affidavit with the county. Current MVD and county procedures should be confirmed. ADOT MVD describes the sequence this way:
Recording an Affidavit of Affixture, as ADOT MVD describes it
- Complete the affidavit. The homeowner fills in the top section of the Affidavit of Affixture form.
- Visit MVD with the title. Bring the affidavit and the title for each section, plus a tax clearance receipt if any taxes are delinquent and a lien release or letter from the lien holder; without one, a lien is placed on the affidavit.
- Surrender the title. The MVD agent takes the title for each section.
- Record it with the county. The affidavit is filed with the County Recorder; the county assessor then treats the home as real property rather than personal property.
Financing an affixed home still depends on the complete property, borrower, value and current program.
Arizona rules that affect your budget
Beyond the loan payment, much of the monthly cost of an Arizona manufactured home comes down to how space rent is set, how the home is taxed, and the climate where it sits. This is general information, not legal or tax advice; confirm the details for the home you are considering with the county and the community.
Space rent is set by the lease, not by a local ordinance
Arizona law does not let counties, cities or towns control the rent on mobile home spaces (A.R.S. 33-1416), so there is no local space-rent ordinance to look up: space rent is set by the community under your rental agreement. Park tenancies are governed by the Arizona Mobile Home Parks Residential Landlord and Tenant Act, and the state also keeps a Mobile Home Relocation Fund (A.R.S. 33-1476.02), administered through the Arizona Department of Housing; the statute explains who it is for. Read the lease, ask the community how rent changes are handled, then check how space rent affects what you can afford.
County personal-property tax until the home is affixed
In Arizona a manufactured home that has not been affixed to land its owner holds is taxed as personal property by the county: the county assessor keeps the account, the county treasurer sends the bill, and an Affidavit of Affixture changes the home’s status from personal property to real property, taxed with the land. State law makes it unlawful to knowingly move or sell a mobile home with delinquent property taxes (A.R.S. 42-19155), and a county property-tax clearance is needed before a home is moved.
Ask the seller for the current tax status and the county account before you make an offer. The Maricopa County Assessor’s mobile home page shows how one county handles it; each county has its own assessor and treasurer.
Community home compared with an affixed home on owned land in Arizona
| What differs | Home in a land-lease community | Home affixed to land you own |
|---|---|---|
| What the loan covers | The home alone (a home-only, or chattel, loan) | The home and the land together |
| Title record | MVD title, one per section | Affidavit of Affixture recorded with the county; MVD titles surrendered |
| Property tax | County personal-property tax on the home | Taxed with the land as real property |
| Paid on top of the loan | Space rent, insurance, utilities, community fees | Property taxes and insurance; well, septic or propane where rural |
| Separate reviews | Community resident approval | County recording and local installation permits |
| What the appraisal covers | The home, supported by comparable sales | The home and the land |
A home on land you own that has not been affixed keeps its MVD titles and stays on the county’s personal-property roll; the owned-land column describes an affixed home. For installation and permit questions, the Arizona Department of Housing is the state agency to ask.
Heat, monsoon storms and snow country
Arizona’s climate reaches the loan file through the inspection and the insurance quote, and insurance is part of the monthly cost the lender reviews.
Winter and seasonal residents
Many Arizona communities are age-qualified and fill with winter residents. If the home will be a seasonal residence rather than your primary one, say so to the lender at the start: many programs require owner-occupancy, and seasonal use can also change how the home is insured, so ask whether financing is available for your intended use before you choose a home. The guide to buying a manufactured home as a snowbird in Arizona covers occupancy, insurance and closing the home for the summer.
Arizona manufactured home loan guides by area
Phoenix & Central Valley
Extreme heat shapes which home to buy and how to inspect it; the county’s title and tax records, the Valley’s park-closure history and the relocation fund are the local questions.
East Valley
Large land-lease and age-qualified communities, park models in some, owned lots toward Apache Junction, the Pinal–Maricopa county line, and county floodplain maps.
West Valley
Communities inside the cities and owned lots with wells, septic and washes farther out, monsoon wind and flood checks, and near Luke Air Force Base a disclosure to read.
Southern Arizona
Pima County title and tax records in Tucson, age-qualified community rules south of the city, monsoon checks and the home’s build date, and high-desert parcels in Cochise County.
Northern & Central Arizona
High-elevation country: snow, heating fuel and winter access, and rural parcels with wells and septic alongside the in-town communities.
Western Arizona
Colorado River towns with many seasonal residents, summer heat that keeps cooling in every budget, and high-desert parcels around Kingman.
White Mountains & Rim Country
Mountain communities and rural parcels where snow, heating, insulation and winter road access belong in every budget and inspection.
Pinal County
Commuter cities between Phoenix and Tucson with community and owned-land homes; the county line changes which assessor and recorder hold the records.
Buying elsewhere in Arizona? Financing is available statewide. Ask us about your area →
Estimate your monthly payment
Try our manufactured & mobile home loan calculator — adjust price, down payment, term, taxes, and space rent to see an estimated monthly payment. Estimates are for educational purposes; all financing is subject to credit approval.
Frequently asked questions
Does Santiago Financial offer manufactured home loans throughout Arizona?
Santiago Financial, Inc. currently arranges manufactured and mobile home financing throughout Arizona. The local guides provide additional context for selected areas, but your city does not need to be listed. All financing is subject to credit approval and current program availability.
Can I finance a manufactured home in an Arizona community?
Financing may be available for eligible homes in land-lease communities. The home loan and the community’s resident approval are separate reviews, and space rent is paid separately from the loan payment. The borrower, home, community, loan amount, and current guidelines all matter.
Can I finance a manufactured home on owned land in Arizona?
Potentially. Owned-land transactions may require land records, title information, an Affidavit of Affixture when applicable, foundation details, utilities, access, taxes, insurance, and an appraisal. The correct structure depends on how the home and real property are legally treated.
Who handles mobile home titles in Arizona?
The Arizona Department of Transportation Motor Vehicle Division handles mobile home titles. Arizona generally issues a separate title for each section. When an eligible home is permanently affixed to the owner’s real property, the title may be surrendered and an Affidavit of Affixture recorded through the applicable process.
What should I budget for in an Arizona land-lease community?
Include the estimated loan payment, space rent, insurance, utilities, community fees, applicable taxes, and a maintenance reserve. Ask what cooling, water, trash, and other services are included, and review community rules and rent-change provisions before buying.
Can I refinance an Arizona manufactured home?
Refinance options may be available for eligible community homes and owned-land homes. Current balance, requested loan amount, equity, title or affixture status, home age and condition, location, credit, income, and current program guidelines affect availability.
Looking for a manufactured home loan in Arizona?
Tell us the city and whether the home is in a community or on land you own, and a specialist will explain what the Arizona file needs. Start online, by phone, or with a printable application. All financing is subject to credit approval.