
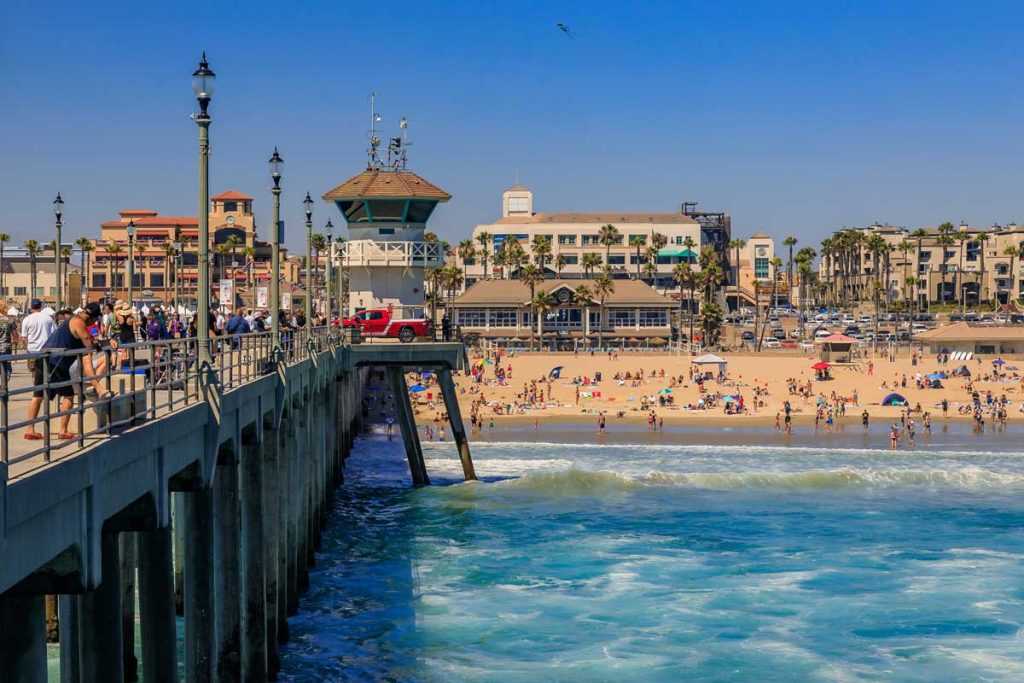
A manufactured home in Huntington Beach comes with questions that a home a few miles inland does not: whether the address is in a mapped coastal or channel flood zone, what salt air has done to the metal under and around the home, and, if the home is in a community, what the space rent is. The city’s own flood page says flooding here can come from the Santa Ana River, the East Garden Grove Wintersburg, Talbert and Huntington Beach channels, or the Pacific Ocean.
Santiago Financial, Inc., based in Tustin, finances purchases and refinances of manufactured homes in communities and on owned land across Orange County. In a community you own the home and rent the space, so the home is financed by itself as personal property with a home-only or chattel loan, and space rent is paid on top of the loan payment. All financing is subject to credit approval.
Flood zones, salt air and earthquakes reach the loan through insurance
A lender compares your loan payment, taxes, insurance and any space rent with your income. In Huntington Beach the insurance line can include flood coverage, and the inspection can turn up corrosion that an inland home would not have. Each item below can be looked up before you make an offer.
Local checks before you make an offer in Huntington Beach
| Local factor | What the source says | Where to look |
|---|---|---|
| Flood zone | Homeowner’s insurance does not cover flood damage, and in a Special Flood Hazard Area flood insurance is mandatory when the mortgage is through a federally regulated lender; map revisions since 2010 changed designations for Huntington Harbour, Sunset Beach and areas near the East Garden Grove Wintersburg Channel | City of Huntington Beach flood information and the FEMA Flood Map Service Center |
| Salt air | Salt spray is greatest near breaking waves and declines over the first 300 to 3,000 feet inland, though studies FEMA cites have found accelerated corrosion farther inland than that | FEMA Technical Bulletin 8 on corrosion in coastal areas |
| Earthquake | Earthquake damage to a mobilehome is in most cases not covered by a homeowners policy; a separate policy is added through your insurer, with a discount for a home that has been retrofitted | California Earthquake Authority and the EQ Zapp hazard map |
| City or county | Part of the Bolsa Chica area is unincorporated county territory rather than City of Huntington Beach | OC LAFCO’s list of unincorporated areas |
Whether your particular loan requires flood insurance depends on the program and on where the address falls on the map. Ask before you commit, and ask for a manufactured home insurance quote for the exact address, so the premium is in your monthly figure from the start rather than a surprise at closing.
What salt air means for the inspection
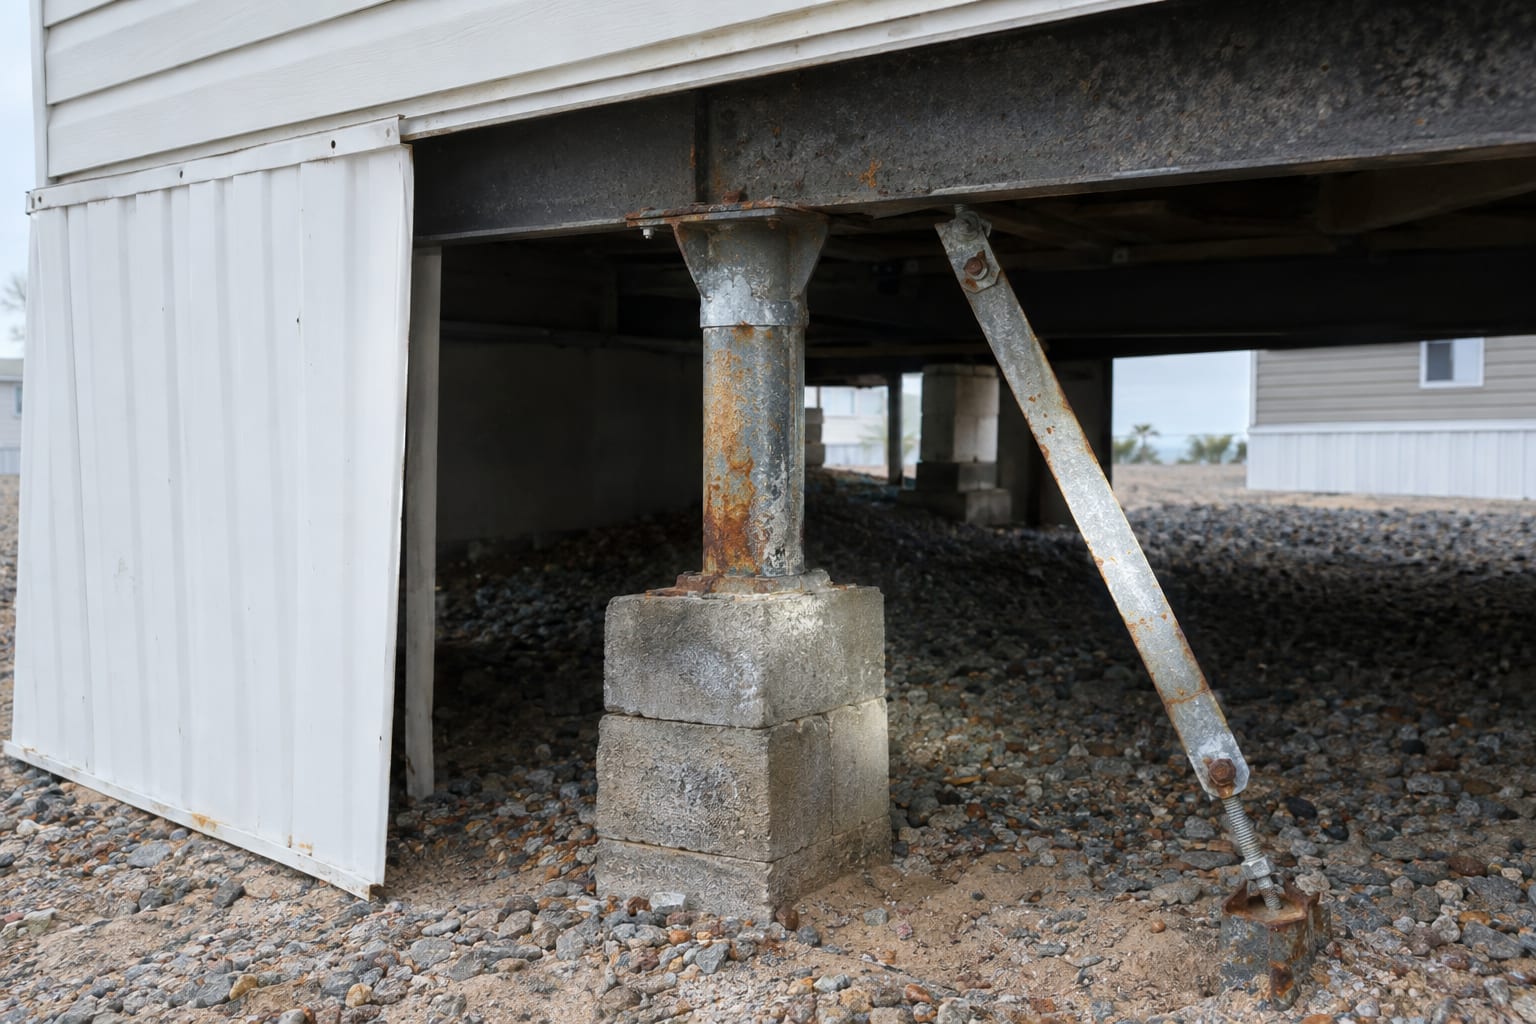
On a manufactured home, the parts that corrode are the ones you cannot see from the street: the steel frame the home sits on, the piers, the tie-down straps and ground anchors, the fasteners, and the posts of a carport or awning. FEMA’s coastal guidance is written for builders, but its point applies to a buyer: near the ocean, metal needs looking at and sometimes replacing.
Ask the inspector to open the skirting, check the frame, piers and tie-downs for rust, and put what they find in the report. This is a job for an inspection, not an appraisal; inspection versus appraisal explains the difference. If the report calls for repairs, settle who pays for them with the seller before the loan moves to its final conditions.
Space rent and how you will use the home
If the home is in a community, get the current space rent and the rent that will apply to you as the new owner in writing from the park; the lender verifies it as part of your monthly housing cost. Rent rules are set city by city. We could not confirm a published Huntington Beach rule for mobilehome spaces, so ask the park for its rent history and ask the city’s housing staff what applies.
State law applies in every park: California’s Mobilehome Residency Law, and HCD’s Mobilehome Residency Law Protection Program for certain disputes between homeowners and management. This is general information, not legal advice.
A beach city also raises the question of use. Some buyers want a home here for part of the year or as a second place. Many programs and communities require owner-occupancy, so if the home will not be your primary residence, ask whether financing is available for your intended use before you buy, and ask the community whether its rules allow it.
The community’s resident approval and the lender’s approval are separate reviews, and both need to finish before the purchase closes. For the records side, our Tustin page has a table of which Orange County office holds a manufactured home’s title, tax and recording records.
Nearby cities
Westminster, directly north, has pockets of county territory inside it and no city rent control. Santa Ana has a city rent ordinance that covers mobilehome spaces, Anaheim has its own fire and flood map questions, and Tustin is where our office is. Up the coast in Los Angeles County, Long Beach has a page too. Homes anywhere else in either county are financed the same way.