
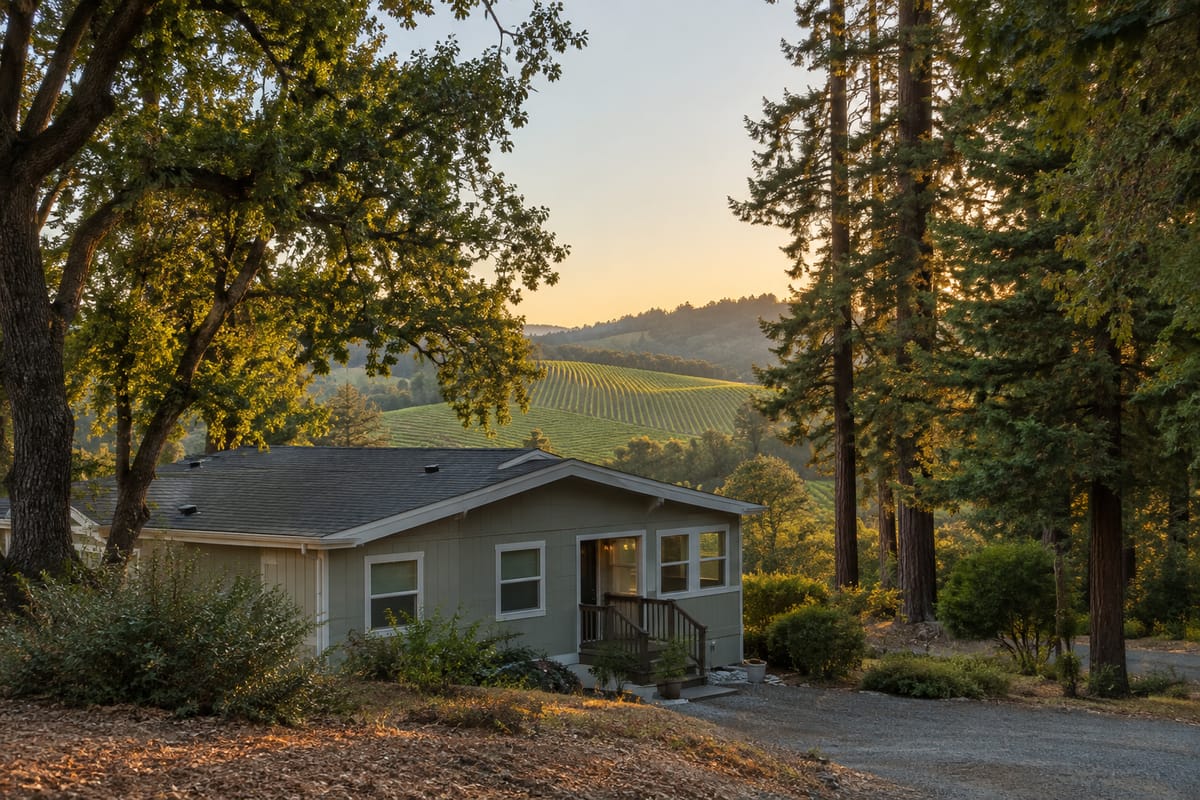
A manufactured home for sale in Santa Rosa is usually in one of the city’s mobilehome parks, where you buy the home and lease the space it sits on; a home on its own lot in the Sonoma County hills is a different loan with a longer document list. What sets Santa Rosa apart is what the October 2017 Tubbs Fire left behind: a mobilehome park that no longer exists, new fire-hazard maps, and an insurance market a buyer should start working with on day one.
For a park home, the loan is a chattel loan on the home alone, the title runs through HCD, and the park’s resident approval is a separate review from the lender’s; the California hub covers those basics. This page covers what is particular to Santa Rosa: fire hazard zones and insurance, two rent ordinances on different sides of the city line, and Sonoma County’s tax and title steps. Santiago Financial, Inc. has financed manufactured homes in California since 1975 and reviews every application individually.
Fire hazard zones changed what a buyer checks first
The Tubbs Fire destroyed a mobilehome park on Mendocino Avenue in October 2017; the city confirms it in its announcement of the senior housing built on the site. That history is why the first local check here is the fire map.
On February 24, 2025, CAL FIRE released new Fire Hazard Severity Zone maps for local responsibility areas, and the city’s summary says they changed its Very High zones and added High zones. Zones are rated Moderate, High or Very High; CAL FIRE’s Fire Hazard Severity Zones page explains the method and links a viewer that shows any parcel.
Three things follow for a buyer, according to the city. Sellers must disclose a home’s zone and supply a defensible-space inspection by the fire department in a sale. New construction and certain renovations in High and Very High zones must meet wildland-urban interface building standards, which matters if you plan a carport, deck or addition. And owners in Very High zones carry defensible-space obligations, which an inspector and the park’s rules will both have views on.
Insurance is where the zone bites. A lender needs proof of coverage before closing, so get quotes as soon as you have a home in mind and tell the insurer the zone. If regular insurers decline, the California FAIR Plan exists for residents who cannot obtain insurance through a regular insurance company; the Department of Insurance describes it as a limited fire policy, so ask what it does not cover. You can also ask us for a manufactured home insurance quote while the loan is being reviewed.
Two rent ordinances, depending on which side of the city line
Space rent is paid on top of the loan payment, so ask the park for the current rent, what it includes, the increase history and the lease on offer, in writing. How space rent affects what you can afford shows why that number decides more than the home price does.
Inside the city, Santa Rosa’s Mobilehome Rent Control Ordinance is Chapter 6-66 of the City Code, and the Department of Housing and Community Services’ mobilehome parks page says 16 parks with 2,154 spaces are subject to it. Outside the city limits, Sonoma County’s Mobilehome Space Rent Stabilization Ordinance (Ordinance 6450) is administered by the county’s Community Development Commission. Each has exemptions, so which one covers a given space, and what it allows, is a question for that office and the park’s management.
California’s Mobilehome Residency Law applies in every park in the state. HCD summarises your rights as a mobilehome park resident and runs a Mobilehome Residency Law Protection Program for certain disputes. This is general information, not legal advice.
Local factor, what it changes, and where to check
| Local factor | What it changes for a buyer | Where to check |
|---|---|---|
| Fire hazard severity zone | Disclosure and a defensible-space inspection at sale; WUI building standards for certain work; insurers price for it | CAL FIRE’s zone viewer and the city’s summary, linked above |
| Insurance availability | A lender needs proof of coverage before closing; the FAIR Plan is the fallback when regular insurers decline | The Department of Insurance FAIR Plan page above, and your insurer |
| Space-rent rules | A city ordinance inside Santa Rosa, a county ordinance in unincorporated parks, each with exemptions | The city and county pages above |
| Earthquake | Homeowners and mobilehome policies do not cover quake damage; USGS names the Hayward–Rodgers Creek system and the San Andreas as the Bay Area faults most likely to produce a damaging earthquake | The CGS EQ Zapp parcel map and the earthquake insurance guide from the Department of Insurance |
| Tax system and title | Local property tax or HCD fee by the home’s age; a county tax clearance before HCD transfers title | The Sonoma County Assessor page below |
On the earthquake row: ask whether the home has an earthquake-resistant bracing system under it, which in a park is installed under an HCD permit, and whether earthquake coverage is available for it. Whether a program requires that coverage varies, so ask before you shop for the policy.
Taxes, title and the county recorder
The Sonoma County Assessor’s manufactured home assessment page explains that homes sold new after July 1, 1980 pay local property tax, and that the buyer of an older home may have a choice between HCD’s in-lieu fee and county property tax. HCD requires a tax clearance certificate from the Sonoma County Tax Collector before it transfers title to a home on the local roll, and any outstanding taxes must be paid first.
Ask early which system the home is on and whether the title is in the seller’s name; California HCD title basics lists the records a clean transfer needs. For a home on its own lot, home and land are reviewed together under a land-and-home structure, the affixture record such as a recorded 433A sits with the Sonoma County Clerk-Recorder, and a well, septic system and private road are each documented.
Nearby areas
We finance manufactured homes throughout California, so a city without its own page is still served. Guides for the wider region cover San Jose and Sacramento.
Before you write an offer on a Santa Rosa home, ask a specialist to look at the fire-zone and insurance picture with you: talk with a specialist. Pre-qualification is not final approval, and not all applicants or properties qualify.