
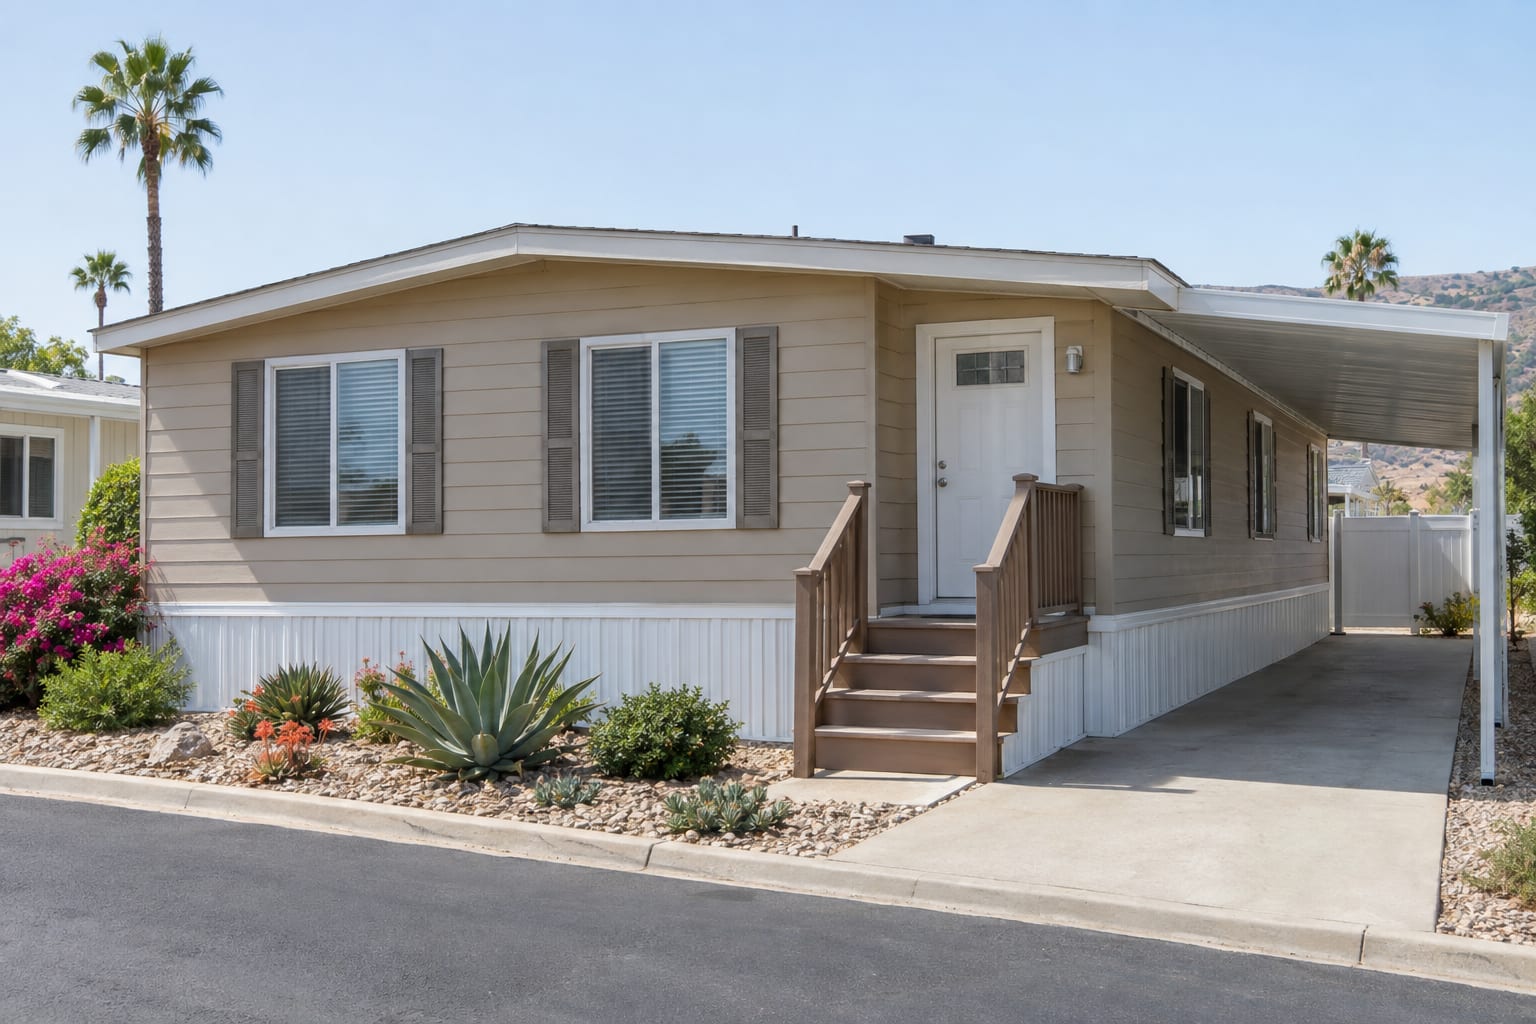
Santiago Financial, Inc. is a full-service manufactured housing lender, and manufactured and mobile homes are the only thing we finance. That focus is the point: we know how these transactions differ from a site-built mortgage, where they tend to get stuck, and what to check before a problem becomes a delay. We have specialized in manufactured and mobile home financing since 1975 and now serve buyers in California and Arizona. All financing is subject to credit approval.
What a specialist lender does differently
A manufactured home is not financed the way a site-built house is, and most of the friction in these files comes from lenders who treat it as if it were.
The home may be personal property, not real estate. Many manufactured homes, nearly all of those in land-lease communities, are financed as the home itself rather than as real estate. The paperwork differs, but the practical experience of applying and making a monthly payment is familiar. What it changes is which programs are available to you, which is why it helps to review the options with someone who works in this niche.
The title lives with a state agency. California titles and registers manufactured homes through HCD, with its own rules for converting a home to real property; Arizona does it through the Motor Vehicle Division, generally with a separate title for each section of the home. A specialist checks the title, the registration, and any existing lien in the first week of the file — not the last.
The community has a say. A home on leased land needs the community’s resident approval as well as the lender’s, and the two reviews run on separate tracks. We coordinate them so neither one becomes the surprise that delays a closing.
Value is established differently. Comparable sales inside the community, or an appraisal of the home and land together, support the value — and we know which one a given program expects.
Escrow, lien release, and insurance are part of the job. If something in the file needs attention, such as a title question, a missing lien release, a community requirement, or a policy that must name the lender, we would rather raise it in the first week than the last one.
What we finance
Homes in land-lease communities, homes on owned land, land-and-home projects including construction-style programs, and refinances of all of the above — in California and Arizona only. Start with the loan programs overview, then the purchase, refinance, or land and home page that fits, or answer three short questions on the financing path finder. Statewide detail lives on the California and Arizona pages.
Questions to ask any manufactured housing lender
Whether you work with us or someone else, these six questions separate a specialist from a generalist. Take them to any lender you are considering.
How to apply
The application itself is short. You provide some key information about yourself and the home, and we begin reviewing the request from there. Apply online, by phone, or with a printable form — and a specialist follows up to explain where the file stands and what is still needed. Timing depends on your transaction and the third parties involved. What happens after that, stage by stage and who does what at each one, is on how the loan process works.
Your initial consultation is free. Our licensed mortgage loan originators handle manufactured housing every day, and several members of the team assist clients in Spanish. All financing is subject to credit approval; not all applicants or homes qualify.