
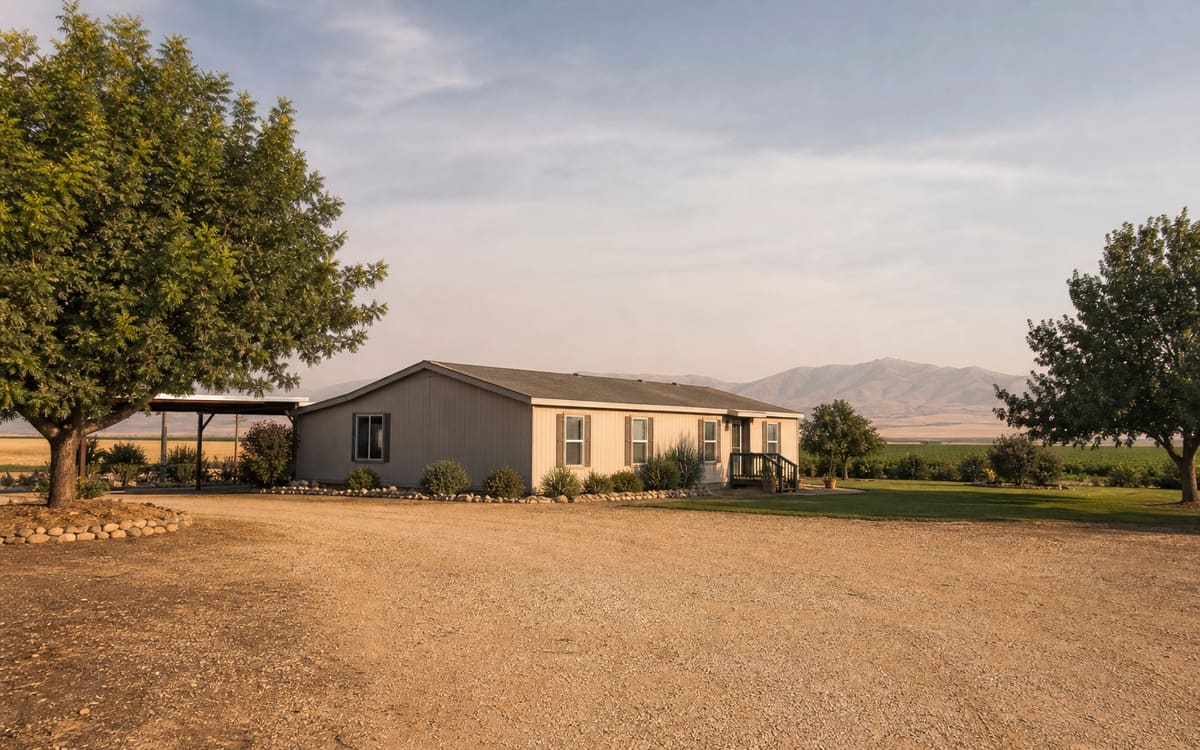
Bakersfield anchors the southern end of the San Joaquin Valley — Kern County’s seat, where agriculture, energy, and logistics meet at the foot of the Grapevine. It’s also one of California’s most genuinely attainable housing markets, and manufactured homes are a large part of why. Established communities fill the city; owned-land homes spread across the county in every direction.
Santiago Financial, Inc. has specialized in manufactured and mobile home financing for more than 50 years, and Kern County’s mix of community and acreage properties is exactly the kind of work that specialization is for.
Two Kern County paths, two different files
Almost every Bakersfield conversation starts by sorting which of these you’re in:
A home in a community. The loan finances the home itself, typically as personal property with its own title. The community owns the land; you lease your space and pay space rent alongside the loan payment. The community also runs its own resident-approval process, separate from the lender’s review. Both have to finish before you move in.
A home on owned land. Common across Kern’s unincorporated areas and the smaller towns ringing the city. Here the question becomes whether the home is affixed to the land as real property, and whether home and land transfer together — which may point toward a land/home loan. Land title, site access, and utilities join the documentation.
Neither is harder. They’re different instruments, and knowing yours before you shop keeps your budget honest.
What rural Kern properties bring to the file
Push past the city limits and the county’s practical realities enter the paperwork:
- Water: municipal service in town; wells or shared systems on outlying parcels
- Septic: standard outside the sewer district, and documented as such
- Access: county-maintained versus private or unpaved roads
- Installation: how and when the home was set, especially on older placements
- Agricultural surroundings: parcels adjoining working farmland are ordinary here
Every one of these is financeable. The buyers who run into trouble are the ones whose lender discovers the well in week six.
The purchase process
- Apply online or call — no obligation, and the budget conversation comes first.
- We review your application individually — income, identification, and financials.
- You shop with real numbers, comparing total monthly cost rather than sticker price.
- Documentation matched to your path — community terms, or land and site records.
- Program review against current guidelines.
- Value support via appraisal or a comparable sales report.
- Conditions, escrow, and signing.
Refinancing in Bakersfield
Kern County owners revisit financing for the ordinary reasons — reviewing a payment set years ago, adjusting a term, consolidating an eligible payoff, or updating the loan after an ownership change. Whether any of that is available depends on eligibility, the property, and current program guidelines. One call gets a straight answer; contact us for current program details.
Bakersfield and Kern County
The Kern River comes out of the Sierra just east of town; Highway 99 runs the valley north; the Grapevine climbs south toward Los Angeles. Country music built a reputation here, agriculture built the economy, and energy built much of the rest. Summers are genuinely hot and the valley’s winter tule fog is its own local institution — both worth budgeting around, in cooling costs and in commute time. For manufactured home buyers, Kern offers what much of coastal California no longer can: room, and a price that still makes sense.
Nearby areas we serve
We finance manufactured homes throughout California, so your city doesn’t need a page here. Nearby guides include Fresno, Santa Clarita, and Victorville, plus Delano, Wasco, Shafter, Taft, and Tehachapi. Browse all California service areas.
Start with a conversation
Begin the quick application, estimate a payment — educational estimates, not offers — or talk with a specialist about your community or parcel.
Available programs and terms depend on borrower qualifications, property characteristics, loan amount, home location, land ownership, and lender guidelines. All financing is subject to credit approval.