Small Towns Included: Financing a Manufactured Home Anywhere in California or Arizona
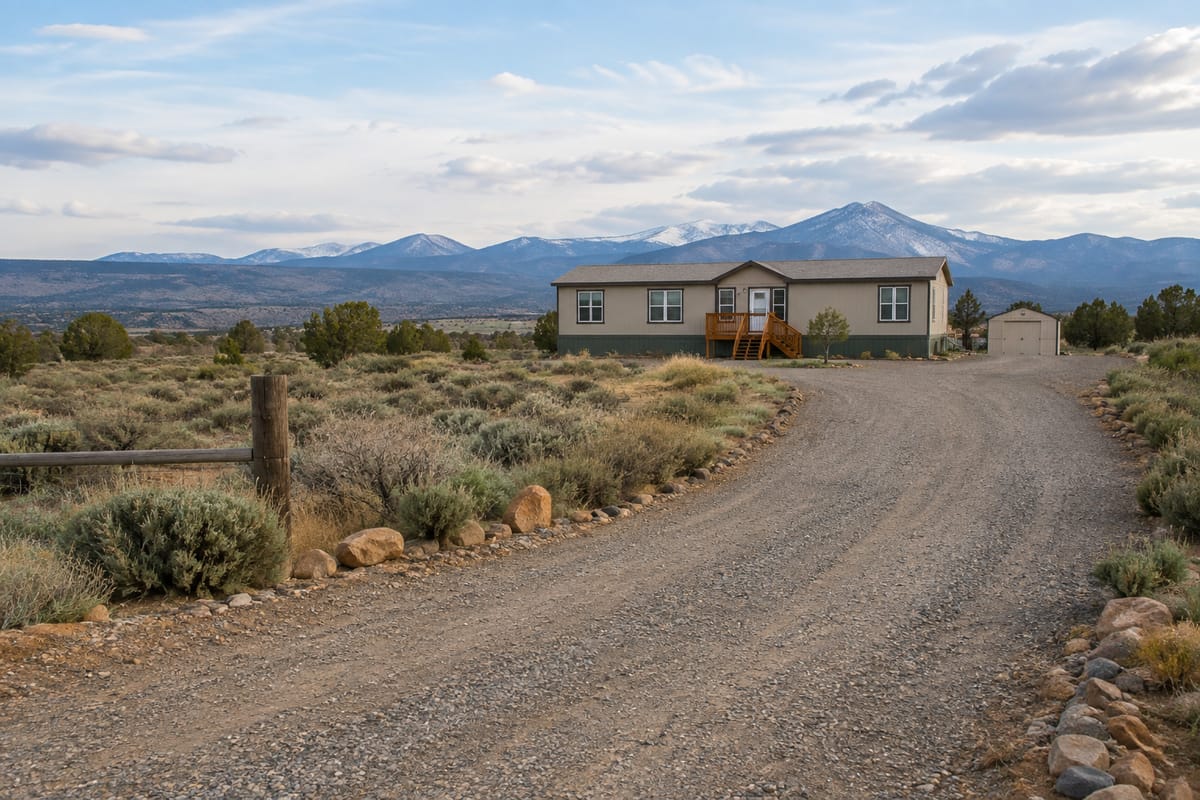
Santiago Financial, Inc. lends across all of California and Arizona, in all 58 California counties and all 15 Arizona counties. The cities we have written pages about are only a sample, so a home in a small town or a rural county is in the service area as much as one in a large city.
For over 50 years, our specialty has been manufactured and mobile home financing. If the home is in either state, it is in our service area.
Our city pages are guides, not boundaries
You’ll find pages on this site for places like San Diego, Fresno, Phoenix, and Prescott. Those exist because local details are useful: regional climates, community types, and the questions that come up in each area. They are local guides, not a service-area limit.
The real boundary is about states, not cities. We finance manufactured and mobile homes located in California and Arizona, anywhere in either state. We don’t lend outside those two states.
Is the home in the service area?
| Where the home is | In the service area? |
|---|---|
| A California or Arizona city with a page on this site | Yes |
| A California or Arizona town with no page | Yes |
| Rural or unincorporated land in either state | Yes; expect questions about access, water, septic and title |
| Any other state | No, even if you live in California or Arizona |
Being in the service area means we can review an application for the home. Every application is reviewed individually, all financing is subject to credit approval, and not all applicants or homes qualify.
If your home is in a California or Arizona town too small to have its own page here, that changes nothing about where we lend. It’s still worth a conversation. For a starting point by region, see the directories of six inland California cities and six Arizona cities.
Rural and small-town homes bring a few extra details
Small-town and rural properties do add a few items to the file, all of them familiar to a manufactured housing specialist:
- Access: unpaved, private, or seasonally maintained roads need to be documented.
- Utilities: wells, hauled water, septic systems, and propane are ordinary outside town, and the file needs records for each.
- Land and title: a home on owned land raises the personal-property-versus-real-property question, covered in financing a home on owned land, while a community home follows the leased-land model with space rent.
- Placement: how and when the home was set matters for classification and program fit.
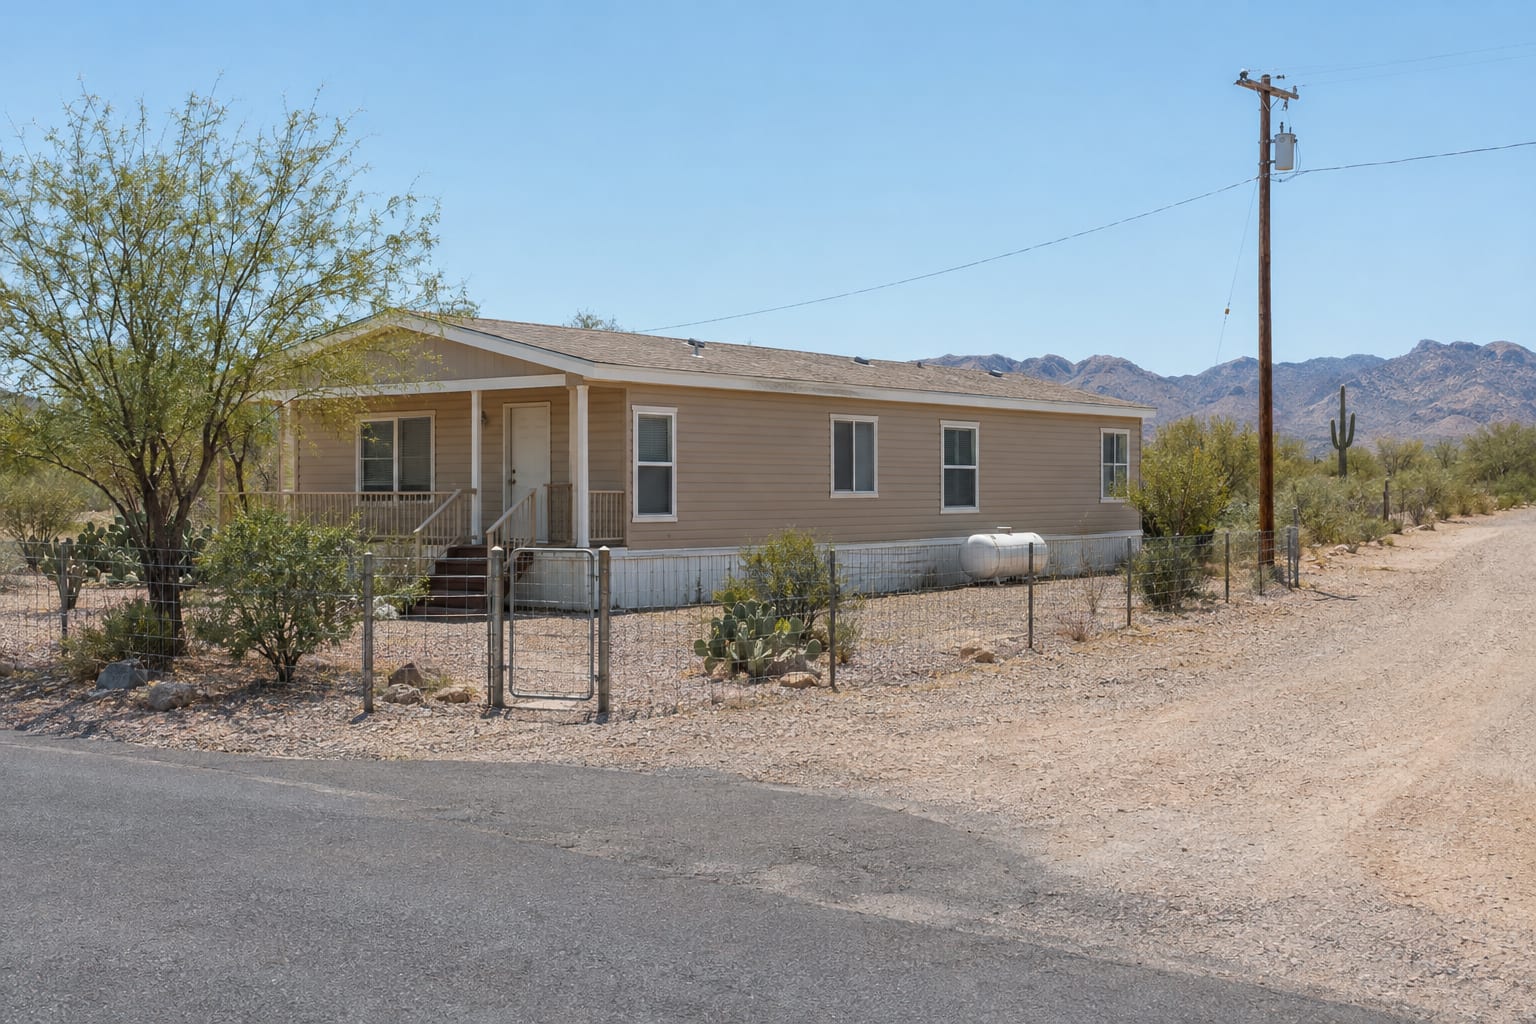
Bring these up on the first call instead of discovering them mid-escrow. A rural file is reviewed the same way as a metro one; it just has more to document.
Distance from our office does not limit where we lend
Our one office is in Tustin, California, and a loan file does not have to pass through it in person. The stages are the same wherever the home is.
How a file moves when you are far from Tustin
- Apply Complete the application online, on a printable form, or by phone, from wherever you are.
- Send documents Your processor tells you what is needed for your situation and how to send it.
- Local pieces are coordinated Valuation, community or land paperwork, and title are handled with the parties where the home is.
- Sign Loan documents are signed with escrow or a notary.
Timing depends on the transaction and the third parties involved, not on how far the home is from Tustin. How the loan process works walks through each stage and who is involved.
Purchase or refinance, both statewide
This applies just as much to refinancing. Owners across both states revisit their loans for ordinary reasons, such as adjusting a term, reviewing a payment set years ago, or replacing older financing, and where you live within California or Arizona doesn’t limit that. Whether refinancing helps depends on your credit, the home, and current program guidelines.
Not sure whether your area is covered? If the home is in California or Arizona, it is. Ask a specialist about your town or parcel, or browse the California and Arizona service areas.