Land & Home and Construction Loans
Finance an existing manufactured home with land or coordinate a new home-and-land project in California or Arizona, subject to property and program eligibility.

A manufactured home on owned land can be financed very differently from a home in a land-lease community. The file may include the home and land as one real-estate transaction, along with title, foundation or affixture records, utilities, access, permits, insurance, taxes, and a combined appraisal.
There are also two very different project types: an existing home already installed on land and a new home that still must be ordered, delivered, installed, and completed. Santiago Financial, Inc. helps eligible California and Arizona borrowers identify the correct path and coordinate the financing work with the other parties involved.
If you already own the parcel — inherited it, bought it years ago, or paid it off — the equity in that land may be able to count toward your down payment instead of cash. The industry calls this arrangement land in lieu (land in lieu of a cash down payment), and it is one of the more common reasons a landowner ends up with a smaller out-of-pocket figure than expected. Whether it applies, and how much of the down payment it can cover, depends on the land’s value, any liens against it, the program, and your qualifications.
Home and land are already together
The review can include land title, home identity and age, current ownership and liens, foundation or affixture documentation, taxes, insurance, utilities, access, condition, and real-property value.
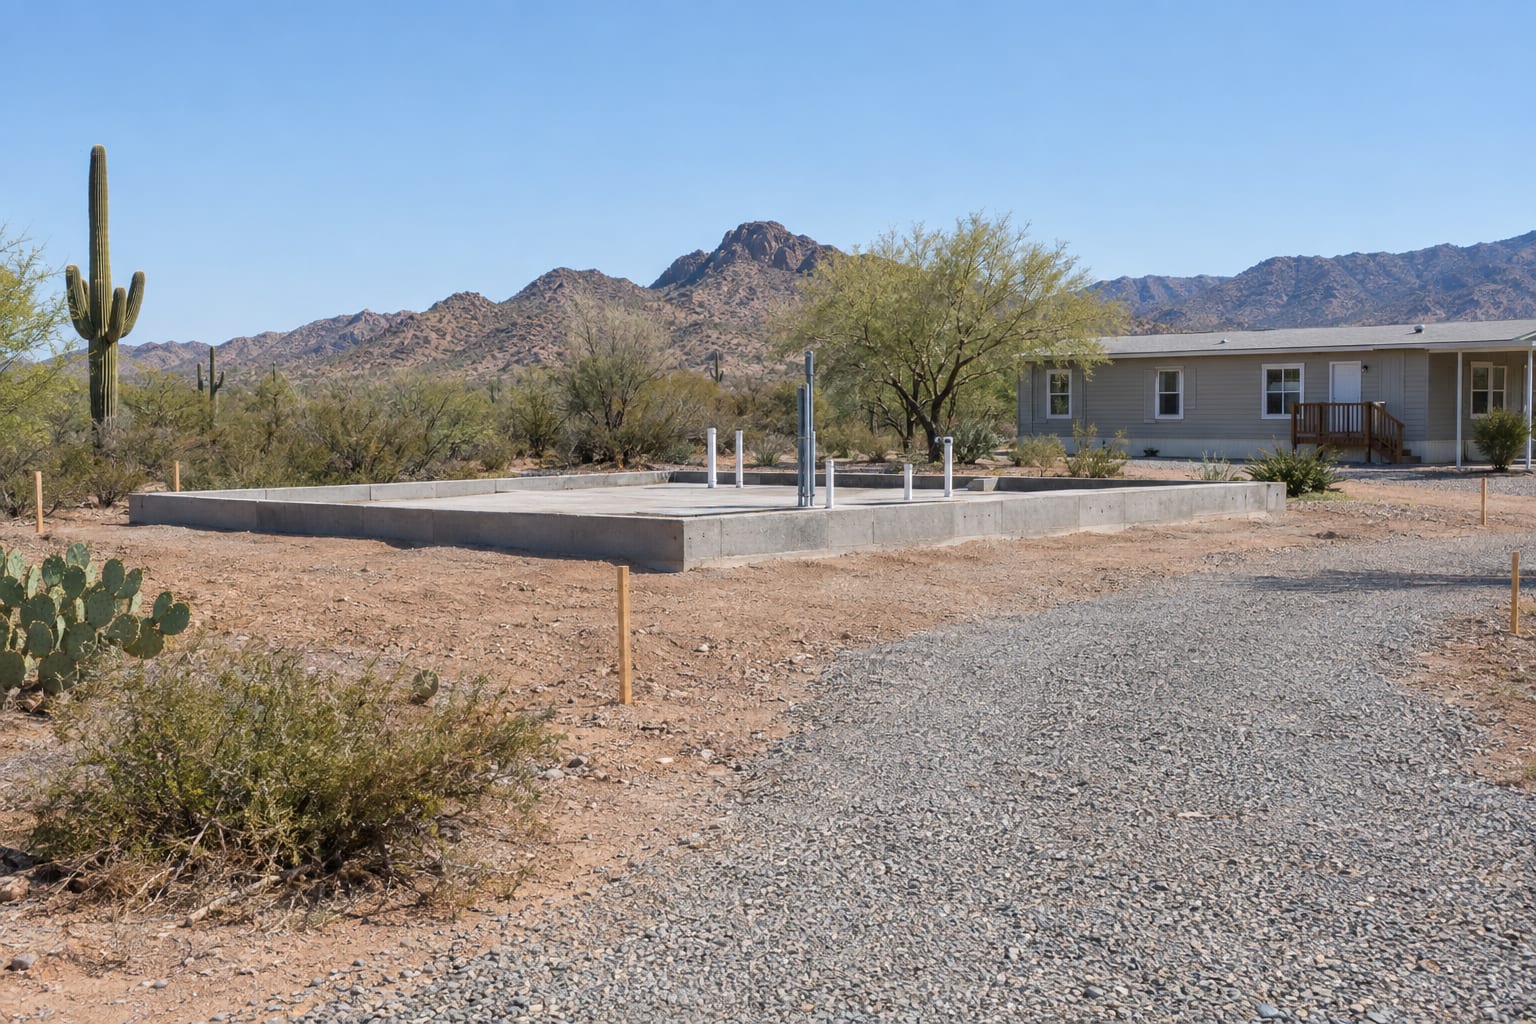
Land, site work, and home must be coordinated
In addition to borrower and land review, the project may involve zoning, permits, site preparation, utilities, foundation plans, dealer or builder contracts, delivery, installation, inspections, and final completion.
- Land Own it or buy it. Zoning, deed restrictions, access and utility availability are checked before anything is ordered.
- Permits and site work Permits, grading, the foundation, and the water, sewer or septic and power connections.
- Home ordered and delivered The home is ordered from the dealer or builder, built at the factory and transported to the site.
- Installation and inspections The home is set on the foundation, connected and inspected. Title or affixture records are completed as the state and county require.
- Completion Final inspections, insurance and value are confirmed, and the loan settles into its permanent phase. When that phase is set up depends on the program structure.
Land & Home Real Estate Loans
For a home that is already on land, or being bought together with its land: purchases and refinances where the home and the real property are financed as one.
- Purchase money and refinance transactions — Conventional, FHA, and VA
- FHA 203(k) rehabilitation financing
- Programs that may consider any-age pre-HUD homes (built before June 1976)
- Manufactured home multi-family properties
- Financing tied to a California 433A real-property conversion
Construction Real Estate Loans
For a new home that still has to be ordered, delivered and installed on your land, so the financing has to cover the project stages as well as the finished home.
- Structures available through FHA, VA, and USDA programs
- Single-close structures where the permanent loan is set up before construction begins, so there is no second qualification step later
- Some programs defer regular loan payments until the home is complete
- Credit requirements vary by program and investor — ask what applies to your scenario
- Down payment requirements vary by program, property, and borrower qualifications
A few of the terms above, in plain words:
- FHA 203(k)
- An FHA-insured program type that lets the cost of repairs or improvements be financed together with the purchase or refinance. Like every FHA, VA and USDA program, it has its own eligibility, property, foundation and fee rules (HUD’s 203(k) page).
- Pre-HUD home
- A factory-built home from before June 15, 1976, the date the federal HUD Code took effect. Technically a mobile home rather than a manufactured home.
- 433A
- The California HCD form that reports a manufactured home’s installation on a foundation system, recorded with the county when applicable. An important property record, but it does not by itself guarantee financing.
- Single-close
- One closing covers both the construction period and the permanent loan, rather than one loan for construction and a second one afterwards.
Ask which of these applies to your project; none of them is automatic. The title and affixture resources further down link the official HCD and MVD pages.
No-Draw Option
On some projects a no-draw structure can cover land and closing costs without the construction-period draw fees and interest charges that a traditional draw schedule creates. It generally suits projects with low on-site costs, or borrowers who can cover permits in cash. Whether it is available depends on the project, the program, and your qualifications.
The items above describe program structures Santiago Financial, Inc. works with, summarizing information we currently present. They are not an offer, a commitment to lend, or a statement of the terms you will receive. Program availability, eligibility, credit requirements, down payments, rates, costs, fees, interest treatment, and terms vary by program, investor, property, and borrower, and can change without notice. All financing is subject to credit approval. Not all applicants or properties will qualify. Contact Santiago Financial, Inc. for current program details.
Questions to answer before choosing land or ordering a home
- Is a manufactured home allowed by the jurisdiction, zoning, deed restrictions, and any association?
- Does the parcel have legal and practical access?
- Are water, sewer or septic, power, and other utilities available, permitted, and included in the budget?
- What grading, foundation, transport, crane, installation, garage, porch, or other site work is required?
- Who is responsible for each permit, inspection, contract, draw, and completion item?
- How will the home be titled or affixed when complete?
- Does the full cost—including contingency—fit the financing and cash plan?
Do not rely on a home price alone. The land, site, permits, utility connections, taxes, insurance, closing costs, and contingency can materially change the total project.
Estimate your monthly payment
Try our manufactured & mobile home loan calculator — adjust price, down payment, term, taxes, and space rent to see an estimated monthly payment. Estimates are for educational purposes; all financing is subject to credit approval.
Frequently asked questions
What is a manufactured home land-and-home loan?
A land-and-home loan finances an eligible manufactured home together with the real property beneath it. It may apply to an existing installed home and land purchase, a refinance, or a project that combines land, site work, and a manufactured home. The structure depends on the property and current program.
Can I buy land and place a new manufactured home on it?
Potentially. A project may require acceptable land, zoning and land-use review, permits, utilities, access, site preparation, foundation and installation plans, a home contract, builder or dealer coordination, insurance, value support, and an approved financing structure.
Can I finance an existing manufactured home already on land?
Potentially. The lender will review the home, land title, ownership, foundation or affixture status, permits or records where applicable, utilities, access, taxes, insurance, value, liens, and borrower qualifications.
What does "land in lieu" mean?
Land in lieu is short for using land in lieu of a cash down payment. If you already own the parcel, the equity in that land may be able to serve as part or all of the down payment on a land-and-home transaction, reducing the cash you bring to closing. Availability depends on the land’s value, existing liens, the program, and borrower qualifications. It is not automatic, and all financing is subject to credit approval.
Can I use land I inherited or already paid off?
Often that is exactly the situation land-and-home financing is built for. The lender will want to confirm ownership and title, check for liens or unpaid taxes, and establish the land’s value. Bring whatever deed or parcel information you have to the first conversation, even if it is incomplete.
What is a California 433A?
In California, HCD Form 433A is used to report the installation of a manufactured home on a foundation system and is recorded with the county when applicable. It is an important property record, but it does not by itself guarantee financing or establish that every program requirement is satisfied.
What is an Arizona Affidavit of Affixture?
For an eligible Arizona mobile home permanently attached to real property owned by the homeowner, the Affidavit of Affixture process generally involves surrendering the MVD title and recording the affidavit with the county. Current MVD and county procedures should be confirmed.
How long does a land-and-home project take?
Timing varies substantially. Land review, permits, utilities, site work, home production, transportation, installation, inspections, appraisal, insurance, title work, and financing conditions can all affect the schedule. Build a realistic timeline before making move-in commitments.
Interested in a land & home or construction loan?
Tell us whether the home is already on the land or still to be ordered, and whether you own the parcel. A specialist can walk through which structure fits. No obligation; subject to credit approval.