Where to Buy a Mobile Home in Phoenix, AZ: Park vs. Land Deals
Local financing details: Mobile Home Loans in Phoenix
Around Phoenix you can buy a manufactured home two ways: on a rented space in a park, or together with the land under it. A park home usually costs less to buy and is financed by itself, but you pay space rent every month and live by the park’s rules. A home with land costs more up front and can often be financed as real estate, but zoning, utilities and title records become yours to sort out.
Neither is the better deal for everyone. It comes down to the cash you have, the monthly total you can carry, and how much say you want over the ground. The Phoenix manufactured home loans page covers the financing; this article is about choosing between the two and where each tends to be found.
In a park you own the home and rent the space
A park, more formally a land-lease community, owns the ground. You buy the home, and you pay the community space rent each month for the homesite, on top of your loan payment.
The home stays personal property. It is titled through the MVD, the Motor Vehicle Division of the Arizona Department of Transportation, generally with one title per section, and it is financed by itself with a home-only loan, also called a chattel loan.
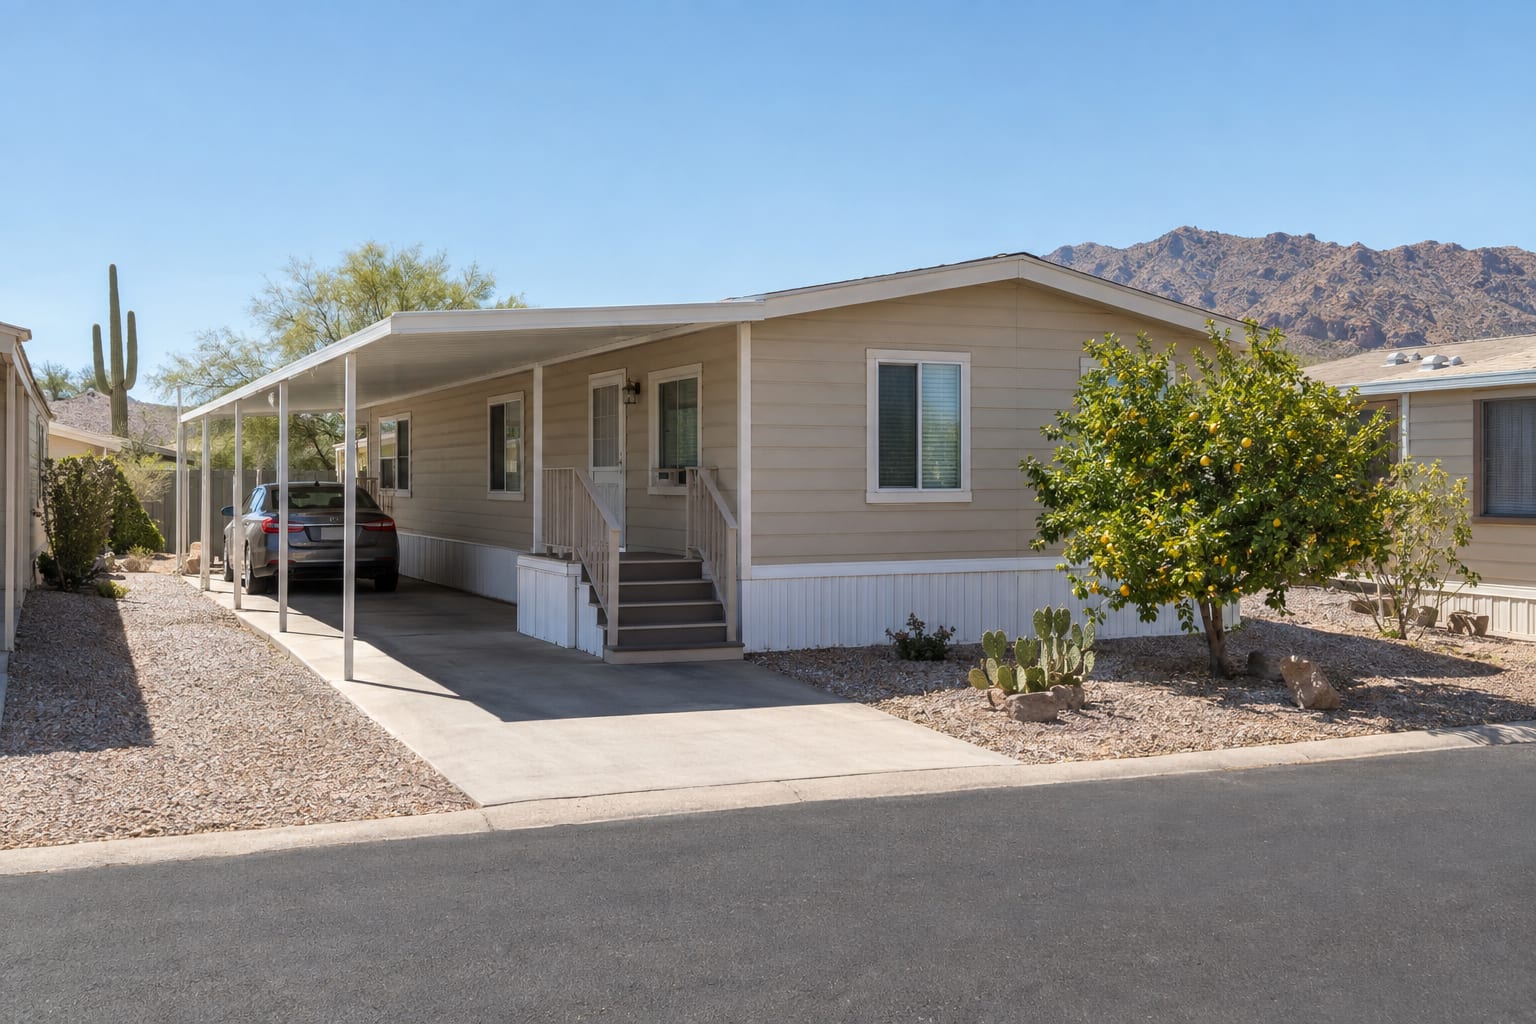
Three things come with that arrangement:
- The rent is part of the price. A lender counts space rent in your monthly housing cost, so it affects how much you can borrow as well as what you pay. Comparing space rent near Phoenix shows how to get the real figure for each park.
- The park approves its residents. Its review of you is separate from the lender’s, and both have to finish before you move in.
- Many parks have an age rule. In a 55+ park, the written rules decide whether a younger spouse or family member may live in the home. Ask for the rule in writing.
With land, the site and the records are yours
When you buy the home and the ground together, there is no space rent and no park office. In exchange you take on what a park would otherwise handle: the road in, water and sewer or a well and septic system, and permits for anything you add.
The paperwork changes too. For an eligible Arizona mobile home permanently attached to real property owned by the homeowner, the Affidavit of Affixture process generally involves surrendering the MVD title and recording the affidavit with the county. Current MVD and county procedures should be confirmed; the MVD outlines them on its mobile home ownership page.
Once the home is real property, home and land can often be financed together through land-and-home financing, and the appraisal covers both. If no affidavit has been recorded, the home may still be titled separately from the land, which changes how it can be financed. Find out which it is before you make an offer. The financing questions for a home on owned land go through the site and the records in order.
Park and land compared
Buying in a park or with land in the Phoenix area
| What to compare | In a park | With land |
|---|---|---|
| What you buy | The home | The home and the lot |
| How it is usually financed | Home-only (chattel) loan | Land-and-home loan, when the home is affixed and recorded as real property |
| Monthly costs besides the loan | Space rent, utilities, insurance, tax on the home | Property tax, insurance, utilities, upkeep of the lot |
| Who else has a say | The park: resident approval, rules, any age restriction | The city or county: zoning and permits |
| Records to check | MVD title for each section, the rental agreement, the park rules | Recorded Affidavit of Affixture, land title, permits |
| What you sell later | The home, to a buyer the park approves | The home and the land |
The table has no row for rates, terms or down payments because neither column has a single figure. Those depend on the program, your credit, the home, and whether the land is leased or owned. As a general matter, chattel loans run shorter and are priced to reflect the different collateral. Credit requirements vary by program and investor, so ask what applies to your scenario.
Where each kind of property tends to be found
Parks are spread across the metro area, inside Phoenix and in the cities around it. Homes on their own lots turn up more often toward the edges of the Valley and in unincorporated places such as Tonopah and Wittmann, where parcels are larger. Treat that as a pattern to test against current listings, not a rule. Phoenix or a nearby suburb looks at how the areas differ.
Before you tour a home with land, find out whose rules apply to the parcel:
- City or county. Inside city limits, the city’s planning department decides whether and how a manufactured home may sit on a lot. In unincorporated Maricopa County, the county says a rural or residential lot may be issued a permit for one HUD-Code manufactured home on a permanent foundation system. See the county’s answer to where a manufactured home can be placed.
- Which county. Not every Valley address is in Maricopa County. The city of Maricopa and most of Apache Junction are in Pinal County, so the recorder and assessor you deal with there are Pinal County’s.
- Water, sewer and access. At the edges, a lot may rely on a well or hauled water, a septic system and a private road. A lender and an appraiser will ask how each one is documented.
- Flood areas. Desert washes flood. The Flood Control District of Maricopa County offers a floodplain viewer, and it notes that not every flood hazard has been mapped yet.
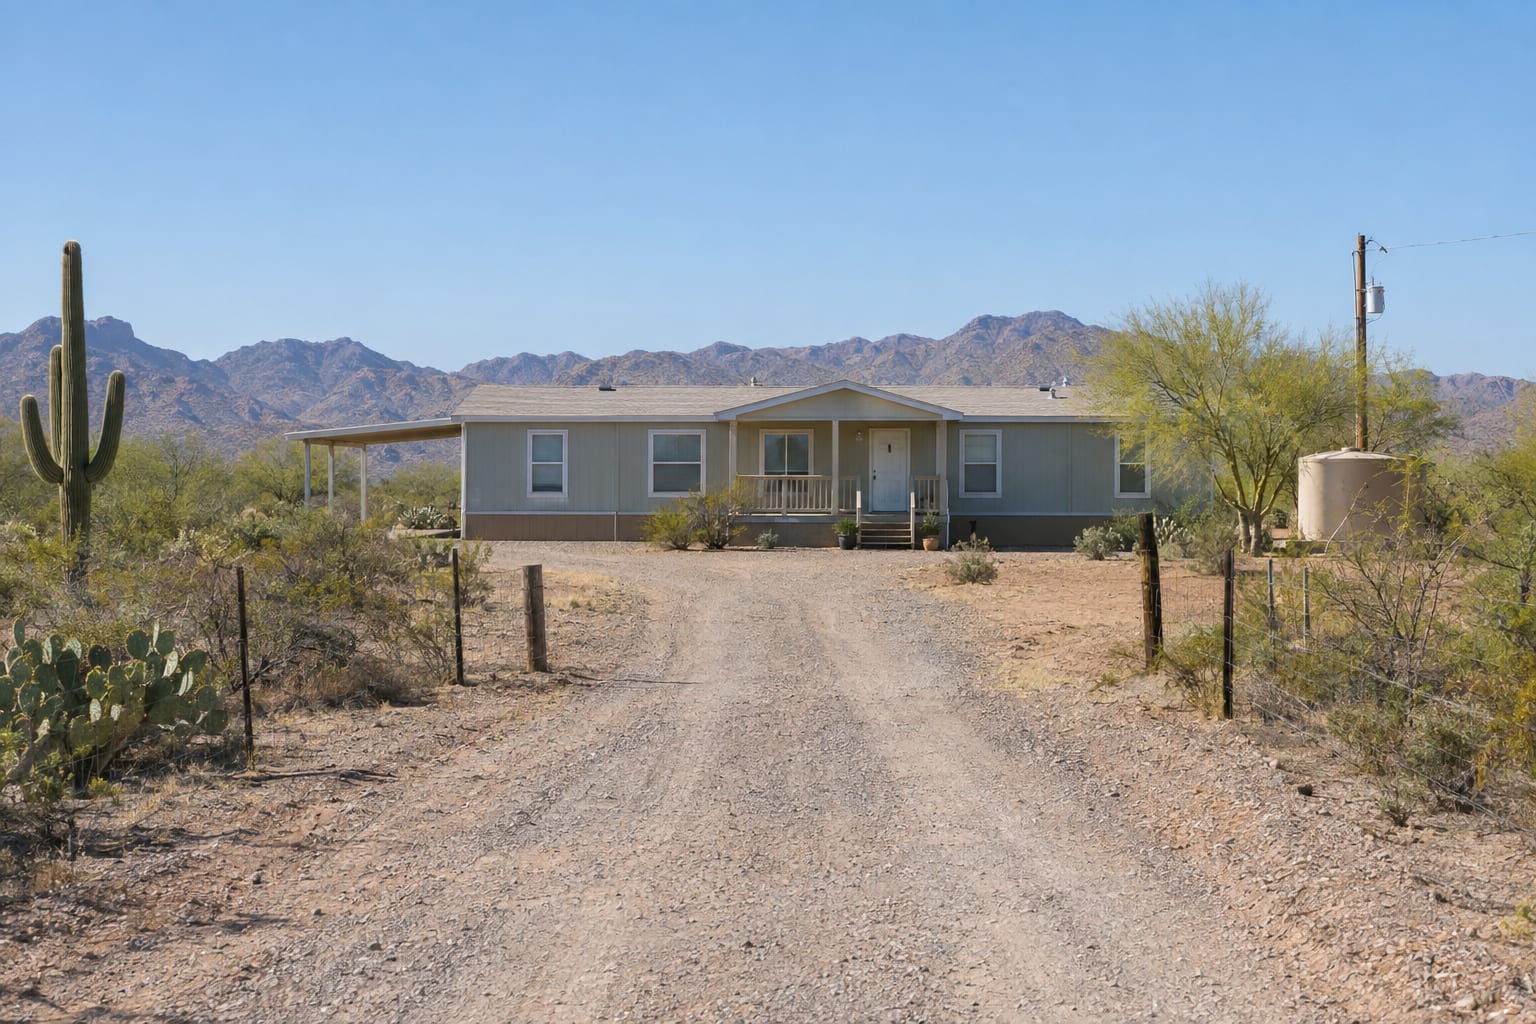
Moving a home onto land you own
Buying a used home and moving it to your own lot is possible, but it involves permits, a mover and site work as well as the purchase. The lot has to allow the home, and the home has to be installed under permit.
In unincorporated Maricopa County, the county requires its own permit before the state installation permit, which comes from the Arizona Department of Housing. The county assessor also generally requires a property tax clearance before a home is moved, as its mobile home questions page explains.
An older home may not be worth the cost of moving, or may not be allowed where you want to put it. Ask whether financing is available for a home that will be relocated before you commit to buying one.
Which one tends to fit
A park tends to fit a buyer who has less cash to start with, wants someone else to keep up the streets and common areas, and can live with a rent that may change. Land tends to fit a buyer who can put more in up front, plans to stay, and is willing to manage a site.
To see how the two compare over the years you expect to stay, work through the long-term cost comparison of a park and owned land with your own numbers. This article is general information, not legal or tax advice, and all financing is subject to credit approval.