Mobile & Manufactured Home Loans in Napa, California
A loan on a manufactured home in Napa County is reviewed the way it is anywhere in California: a home in a community is financed on its own, and a home on land you own may be financed together with the land. What is particular to Napa is the property side of the file. Wildfire zones, the supports under the home, river flooding and the insurance that goes with them can decide whether a purchase closes.
So the order matters. Check the address and get an insurance quote before you make an offer, not after. Santiago Financial, Inc. finances purchases and refinances of manufactured and mobile homes throughout California, including Napa, American Canyon, St. Helena, Calistoga and the unincorporated county.
Where the home sits decides the kind of loan
Start by working out which of these two situations you are in, because each has its own loan, records and approvals.
A community space compared with land you own
| What to compare | Home in a community | Home on land you own |
|---|---|---|
| What you own | The home; the space is rented | The home and the land |
| How it is usually financed | A home-only (chattel) loan | Home and land together, when the home is permanently attached |
| Records involved | HCD registration and title | Land title, plus the foundation record |
| Monthly costs besides the loan | Space rent, insurance, utilities | Property tax, insurance, upkeep of a well or septic system |
| Other approvals | The community’s resident approval | County or city permits for the site |
HCD is the California Department of Housing and Community Development, which titles and registers manufactured homes in California. The foundation record is HCD Form 433A, which is used to report the installation of a manufactured home on a foundation system and is recorded with the county when applicable. It is an important property record, but it does not by itself guarantee financing.
If you are buying a home with its land, or placing a home on a parcel, land-and-home financing explains how the two are financed together. All financing is subject to credit approval, and not all applicants or properties qualify.
Check the wildfire zone and get an insurance quote first
Wildfire is a practical concern in Napa County. The Glass Fire of September 2020 burned in Napa and Sonoma counties and destroyed more than 1,500 structures, according to CAL FIRE.
The Office of the State Fire Marshal maps Fire Hazard Severity Zones in three classes (Moderate, High and Very High) and offers a viewer you can search by address. Look up the home before you get attached to it.
The zone reaches the loan through insurance. A lender needs proof of an acceptable policy on the home before closing, and the premium counts toward your monthly housing cost. In a higher hazard zone an insurer may decline the home or price it differently, which is far better to learn before an offer than during escrow. How insurance costs affect a manufactured home loan covers where the premium enters the review.
If the regular market turns you down, ask about the California FAIR Plan. The California Department of Insurance describes it as available to Californians who cannot get insurance through a regular insurance company, and as a private association run by insurers, not a state agency. Its coverage is more limited than a standard policy, so an owner may need a second policy to fill the gaps.
Santiago Financial’s insurance team can quote manufactured home insurance. For preparing the home itself, see wildfire preparedness for manufactured home communities.
Ask what the home is resting on
On August 24, 2014, the magnitude 6.0 South Napa earthquake struck just south of the city. The state’s after-action report found that mobile home parks were particularly vulnerable: the earthquake shifted 145 homes off their foundations, and fires afterward destroyed 42 mobile homes.
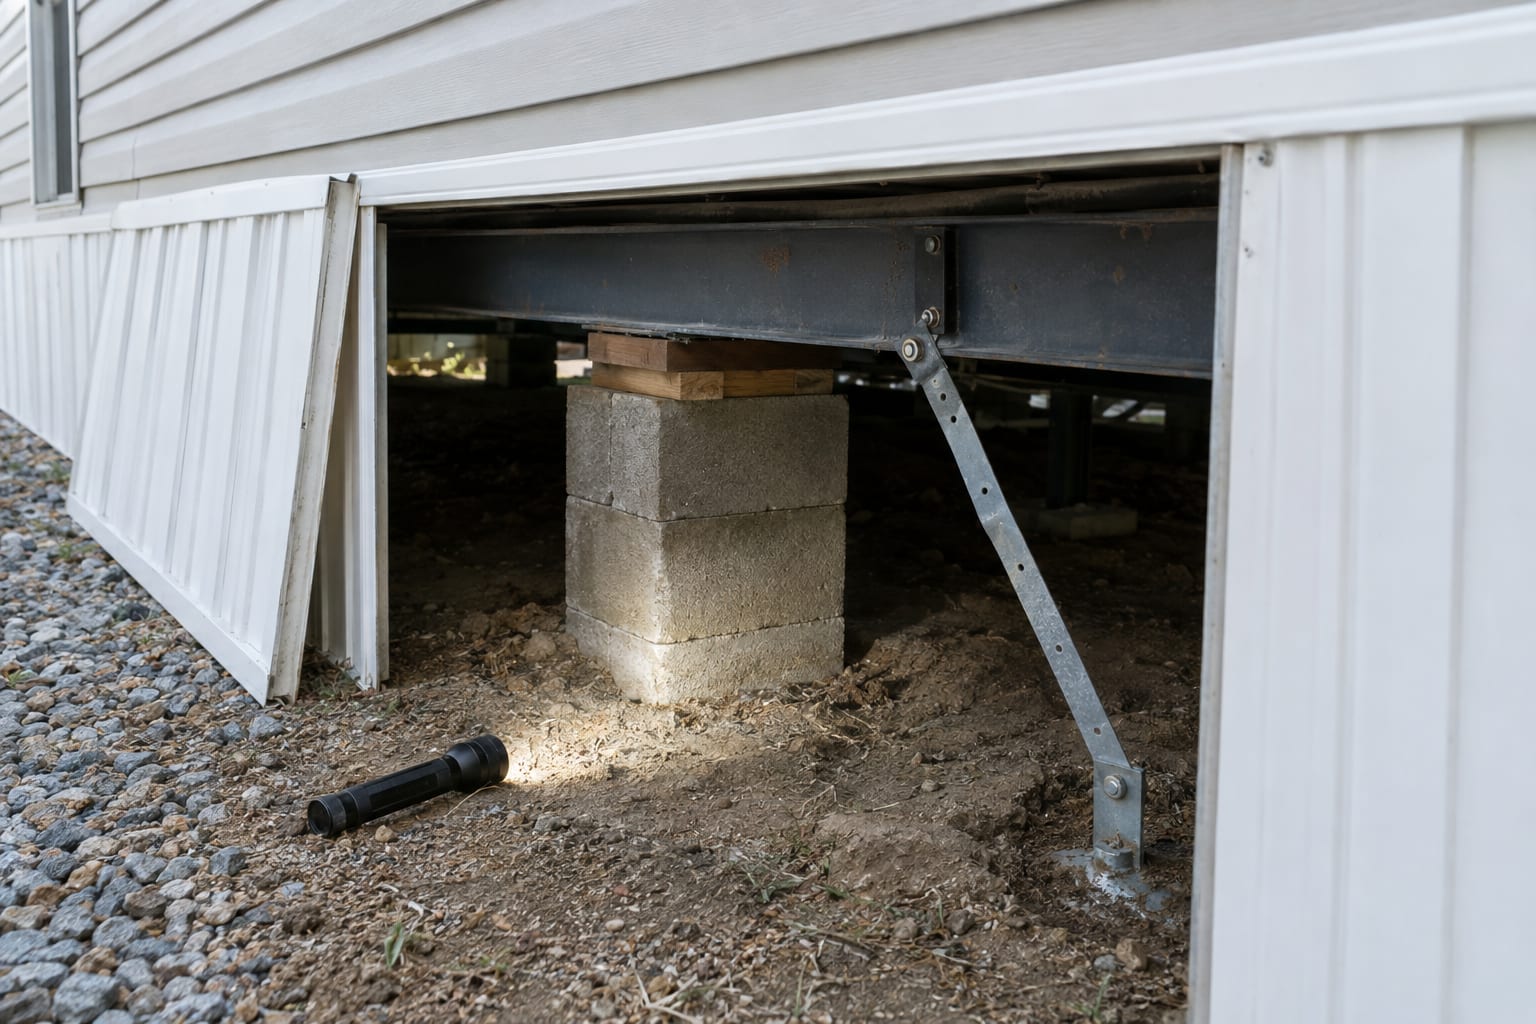
A home in a community usually rests on piers, not a continuous foundation. Ask the seller whether an earthquake-resistant bracing system has been installed. HCD certifies these systems and requires a permit to install one, so there should be a record. Have the inspection include the underside of the home, and ask your insurance agent about earthquake coverage, which is generally a separate policy.
Look up valley-floor addresses on the flood map
The Napa River has a long history of flooding, which is why the Napa County Flood Control and Water Conservation District has spent years on a flood protection project. Search the address at FEMA’s Flood Map Service Center. If the home is in a mapped special flood hazard area, a separate flood policy may be required.
Age rules, space rent and local ordinances in communities
Three questions come up with communities here.
- Who can live there. Some communities are for residents 55 and older and others are open to all ages. Ask before you tour, and ask who in the household has to meet the rule.
- What the space costs. Space rent is paid on top of the loan payment, and a lender counts it when comparing your housing cost with your income. Get the current rent for the specific space in writing.
- Which local rules apply. Rent rules are set city by city. Calistoga, for example, has a Mobile Home Rent Stabilization Ordinance. Elsewhere, ask the city, or the county for unincorporated areas, whether an ordinance or an agreement with the park owner covers the community.
A manufactured home on rural land in Napa County
When a manufactured home sits on its own parcel, the site becomes part of the loan file. Napa County’s Planning, Building and Environmental Services department handles zoning, building permits, wells and septic systems for unincorporated parcels. Start there to confirm that a manufactured home is allowed on the parcel and which permits apply.
Then check how you reach the property, where the water comes from, how wastewater is handled, and whether power or propane serves the site. Buying a manufactured home on owned land goes through each of these in order.
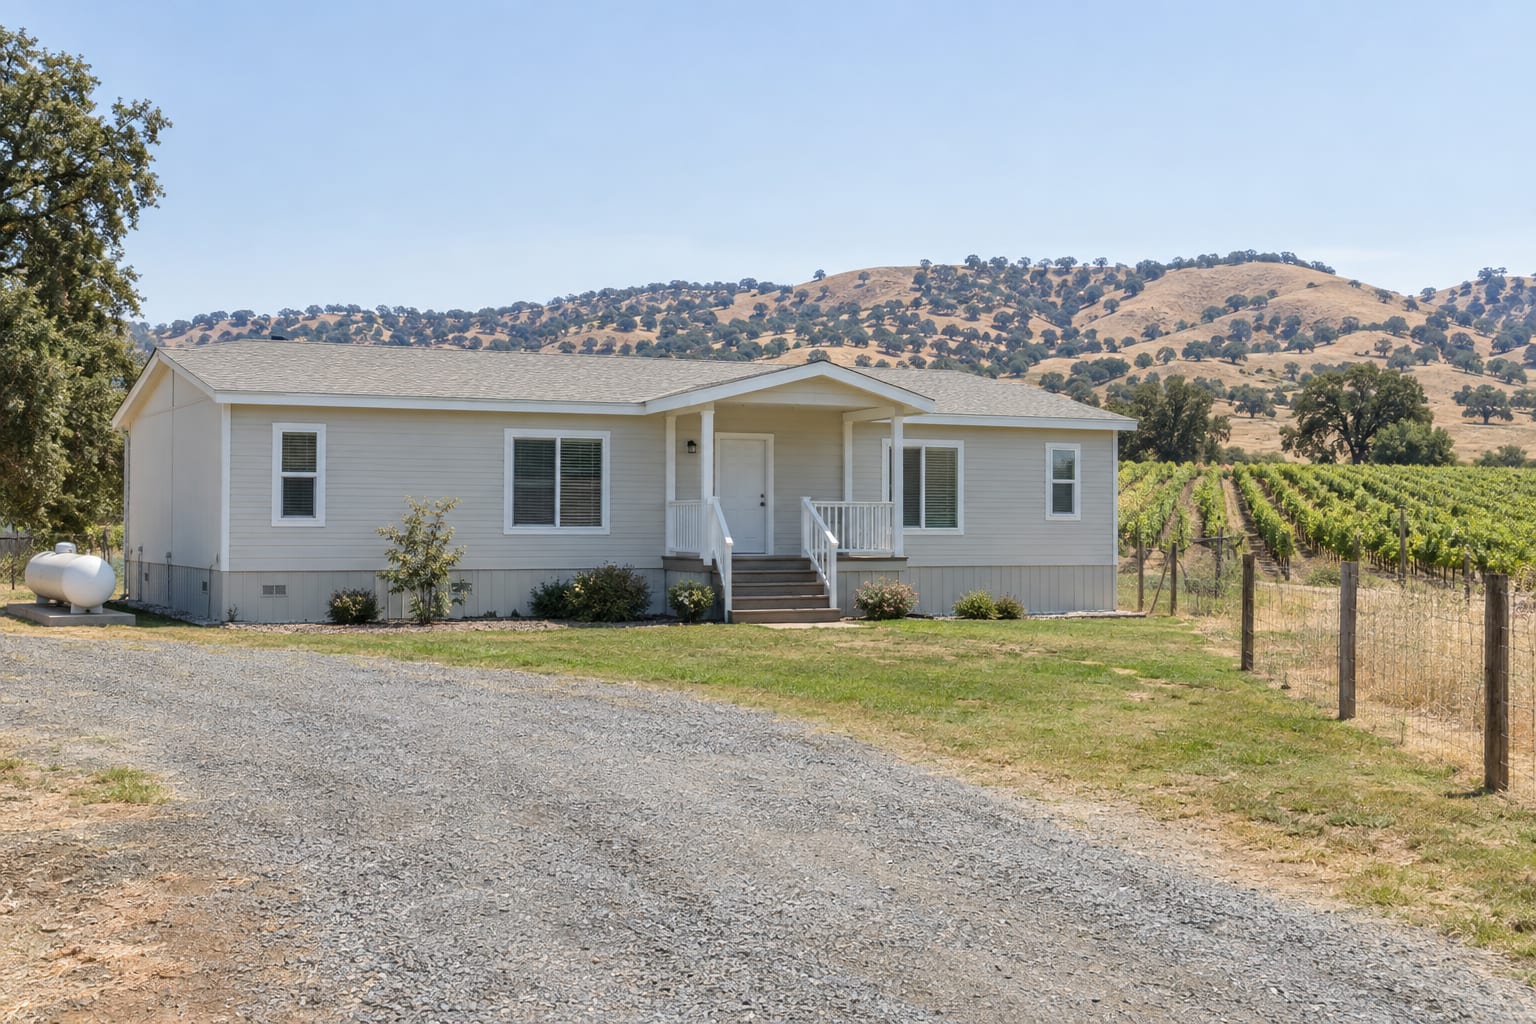
On a hillside or wooded parcel, run the fire hazard zone lookup and the insurance quote before anything else. They are the two answers most likely to change your mind about a property.
If your search crosses into Sonoma County, the same checks apply; see Santa Rosa. This article is general information, not legal or insurance advice, and agency procedures change.