Buying a Manufactured Home as a Snowbird in Arizona
Buying a manufactured home in Arizona for the winter months works the same way as any other purchase, with three differences. The lender will ask how you plan to occupy the home, and the answer affects which loan programs may apply. The insurer needs to know the home will sit unoccupied for months. And the home has to get through an Arizona summer closed up, under the community’s rules, while you are somewhere else.
Deal with all three before you make an offer. Each is better settled early than discovered late.
Tell the lender how you will use the home
A loan application asks whether the home will be your primary residence. Many loan programs are written for a primary residence, and seasonal or second-home use can limit which ones apply. Ask whether financing is available for your intended use before you buy, and before you choose a home.
Describe your plans plainly: how many months a year you will be in Arizona, where you live the rest of the year, and whether you expect to move here full-time later. Give the same account to everyone involved. The answer has to be accurate on the application, so settle it in your own mind first.
Expect the cost of your other home to count as well. A lender compares your monthly obligations with your income, and housing costs in two places are part of that picture. Programs for Arizona manufactured home loans vary, and all financing is subject to credit approval.
Who needs to know the home is seasonal
| Who | What to tell them | Why it matters |
|---|---|---|
| Lender | Months of use, where you live otherwise, the costs of your other home | Occupancy affects which programs may apply |
| Insurer | That the home will be unoccupied for months, and who checks on it | Coverage for an unoccupied home can differ |
| Community office | Your dates, an emergency contact, who has a key | The rules still apply while you are away |
Insurance for a home that sits empty
A policy written for a home someone lives in all year may treat a long absence differently. Before you buy, ask the insurer three things: whether any coverage is limited or excluded when the home is unoccupied, whether it requires someone to check the home at set intervals, and what it expects you to shut off before you leave.
A leak that runs for weeks with nobody there is the kind of loss these questions are about. Get the answers in writing, and build the insurer’s conditions into your shut-down routine. Santiago Financial, Inc. can help with manufactured home insurance quotes; say at the start that the home will be seasonal.
What the community expects while you are away
Many communities popular with winter visitors are age-qualified, and their rules do not pause when you leave. Four subjects matter more to a part-year owner than to anyone else.
- Occupancy. Ask whether the community has any rule on how long a home may stand unoccupied.
- Guests. If family will use the home while you are away, find out whether guests may stay without you and for how long.
- Renting it out. Many communities restrict or prohibit renting your home to someone else, and many loan programs require owner-occupancy. Do not count on summer rental income without checking both.
- The yard and the space. Weeds, landscaping and the look of the space are your responsibility all year. Find out what the office expects and who will do it.
The community also reviews you as a resident before you move in, and that review is separate from loan approval. Both have to be in place before closing. How park rules can affect your purchase covers what to read before you make an offer.
Closing the home for an Arizona summer
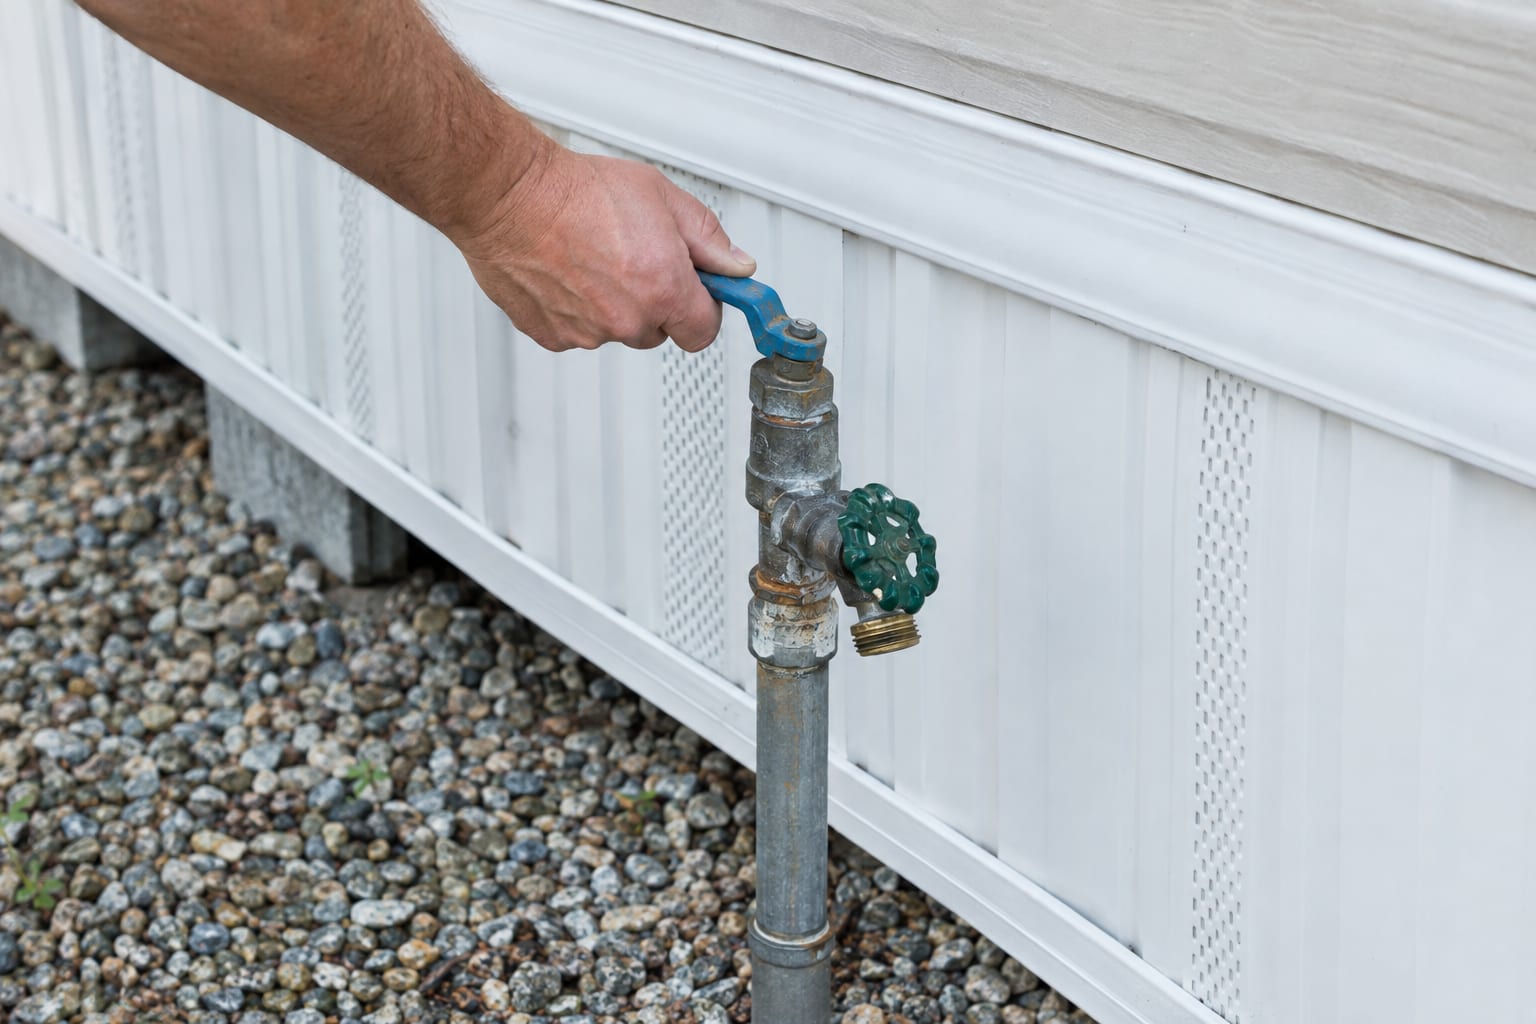
A closed home in the low desert faces months of heat and then the summer monsoon. The National Weather Service office in Phoenix lists dust storms, damaging winds and flash floods among the hazards on its monsoon safety page. The routine below is a starting point; your insurer and the community may add to it.
One bill is often overlooked. An Arizona home on a rented space is generally assessed by the county as personal property, separately from the land, and the tax bill is mailed to the owner. The Maricopa County Assessor explains how that works in its county. Keep your mailing address current with the assessor in the county where the home sits. This is general information, not tax advice.
The summer heat checklist goes further into the cooling system, insulation and sealing.
Choosing where to winter
Winter visitors mostly choose the low desert: the Phoenix area, Tucson, Yuma and the Colorado River cities. Those areas differ in elevation, in medical care and in how quiet they get in summer. Comparing Arizona’s regions sets them side by side.
Once you know how many months you will spend in the home, talk with a specialist before you shop. It is better to learn at the start whether a program fits seasonal use than after you have chosen a home.