Buying a Mobile Home Under 150K: Where to Look and What to Expect
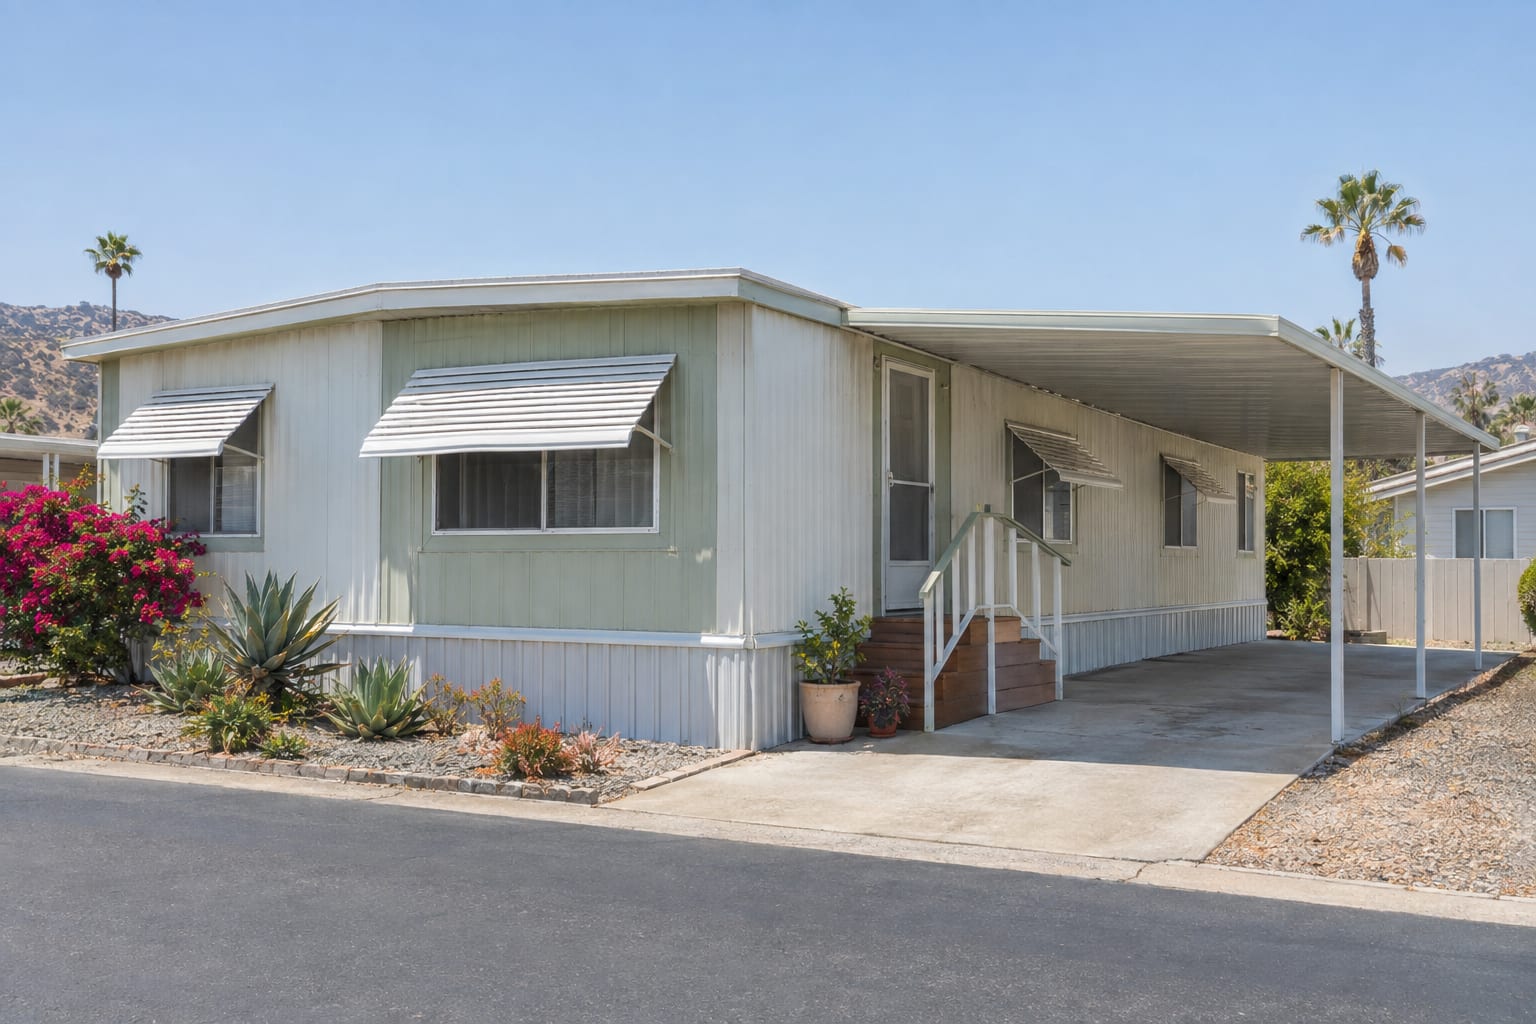
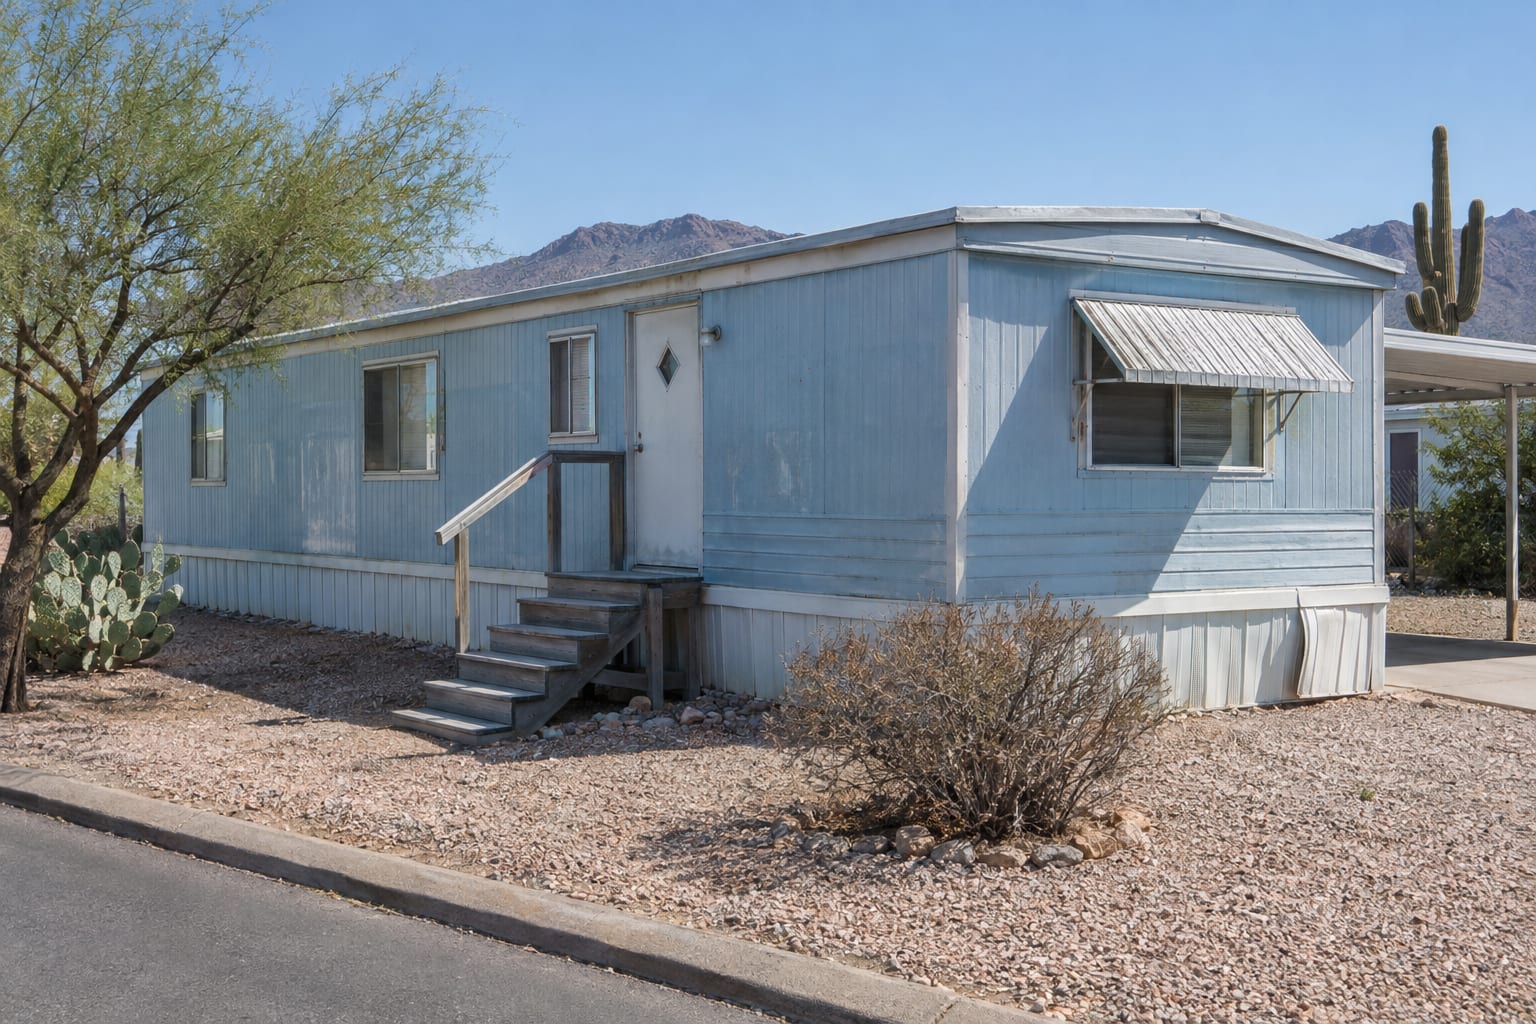
A lower-priced manufactured home is usually a particular kind of home: an older one, often a single-section home, and most often one on a rented space in a community instead of on its own land. You are more likely to find one inland or in a rural area than near the coast, because home prices follow the local housing market. Each of those traits changes how the home is financed and what it costs each month, so the asking price is the first number to look at, not the last.
Santiago Financial, Inc. finances homes located in California and Arizona only, so those two states are the ones covered here. All financing is subject to credit approval, and not every home or applicant qualifies.
What a lower price usually tells you about the home
A manufactured home is priced low for a reason, and usually for more than one. None of the reasons below rules a home out. Each one tells you what to check.
Why a home is priced lower, and what to check
| Why the price is lower | What it means for you | What to check |
|---|---|---|
| The home is older | Its build date, records and condition get a closer look | Year built, HUD label, data plate |
| It is a single-section home | Less floor area than a double-wide of the same age | Whether the layout works for your household |
| It sits on a rented space | You buy the home only and pay space rent every month | The rent in writing; the community’s approval steps |
| It needs work | The loan is based on the home as it stands | Roof, floors, plumbing, electrical; written repair quotes |
| It is far from the coast and the big job centers | Lower local housing costs, longer drives | The cost of the commute; recent sales nearby |
A budget is a ceiling, and two homes under it can be different purchases
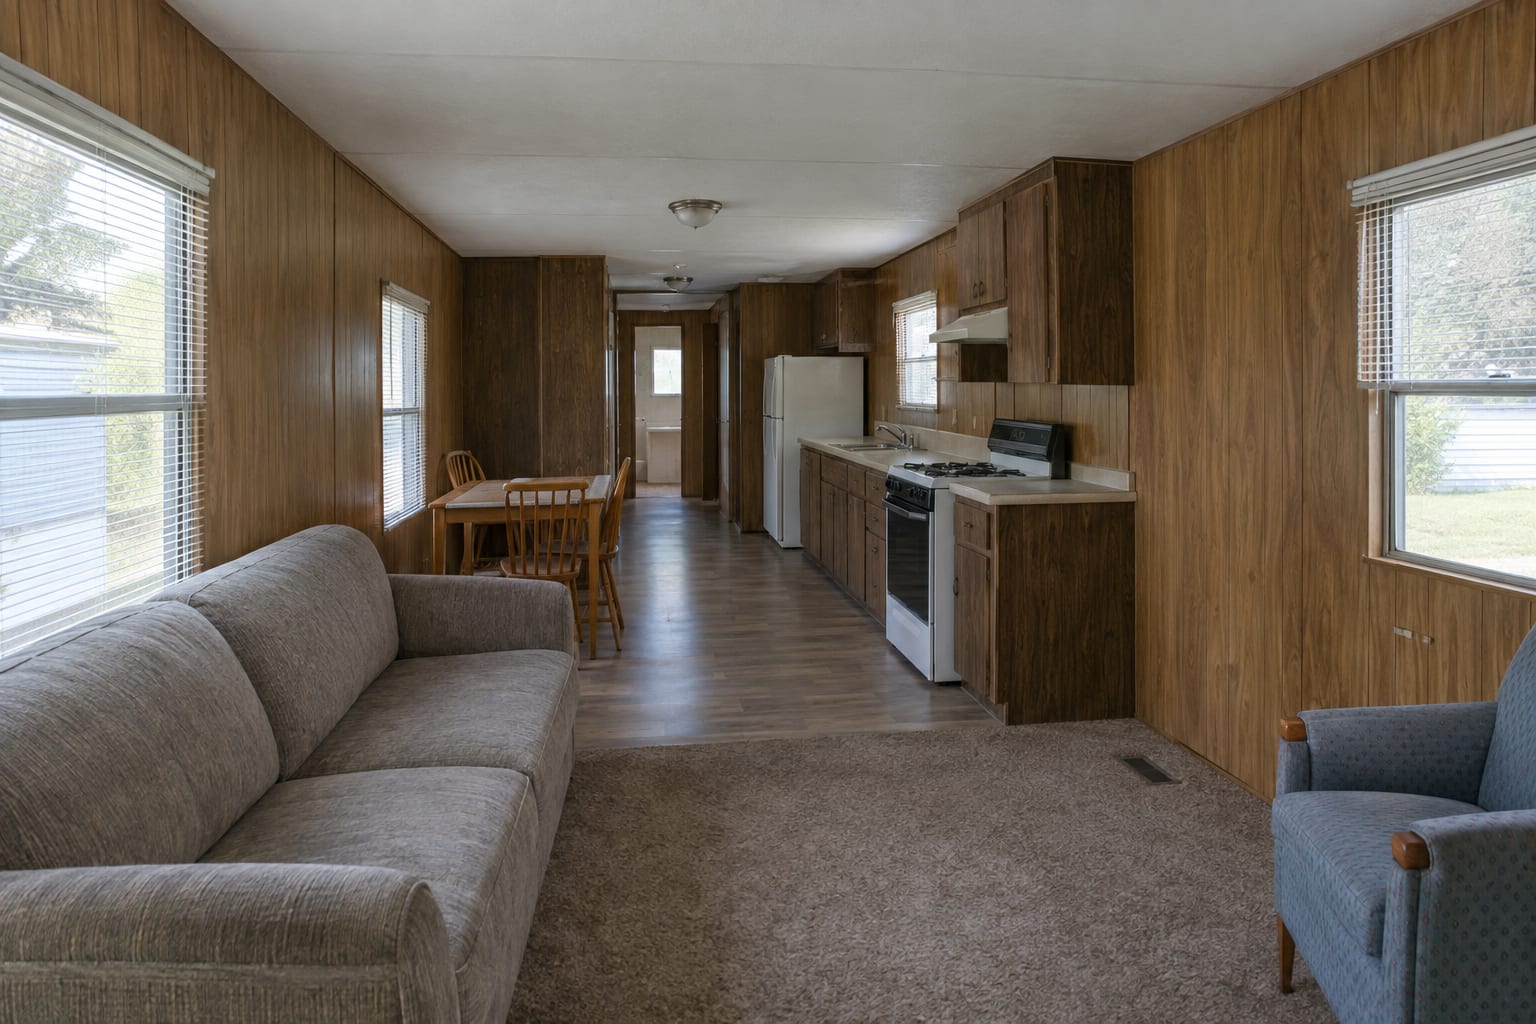
Searching by price alone puts very different homes in the same list.
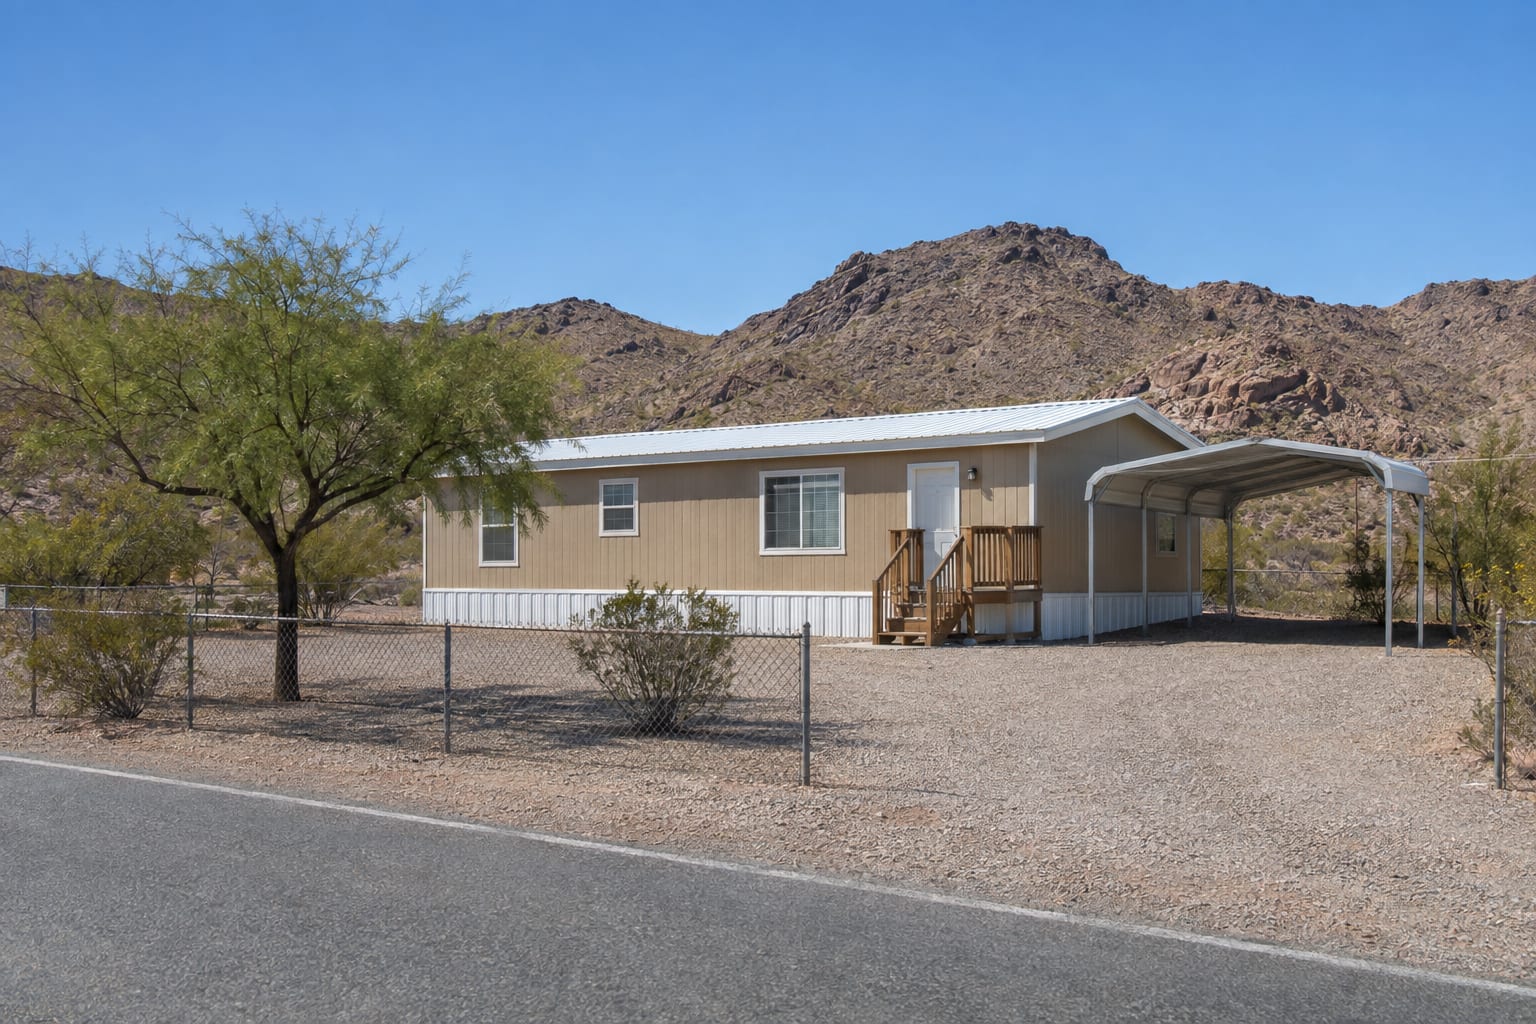
The loans differ as well. The community home is financed on its own with a home-only or chattel loan, and the space rent counts in the monthly cost a lender reviews. The home on its own lot may be financed together with the land if it is permanently attached and recorded as real property.
To see what either home might cost each month, enter your own figures in the payment calculator and add the space rent. The results are educational estimates, not a loan offer. How space rent affects what you can afford shows how to compare two communities fairly.
What a lender looks at on a lower-priced home
The review is the one every pre-owned home gets. A lower-priced home is simply more likely to raise one of these four questions.
- Age. A manufactured home is a factory-built home constructed on or after June 15, 1976 to the federal HUD Code. A factory-built home from before that date is, technically, a mobile home, and lenders treat it differently. Past that line, age limits come from the individual program. Ask whether financing is available for a home of that year before you make an offer.
- Records. The HUD label on the outside, the data plate inside and the serial number have to match the title. On older homes, labels get painted over and data plates go missing.
- Title. It should be current, in the seller’s name and clear of old liens. California titles and registers manufactured homes through HCD (the Department of Housing and Community Development), not the DMV. Arizona titles are handled by the MVD, generally one title per section.
- Condition. The loan is measured against the home as it stands, and the home has to be insurable. Cosmetic work can wait until after closing. A failing roof or soft floors usually cannot. Loan options for a fixer-upper explains where that line falls.
The amount matters too: available terms depend on the program, the home’s age and type, the loan amount, and whether the land is owned. Financing options for pre-owned manufactured homes goes through each of these checks in detail.
Where lower-priced homes tend to be
Prices follow local housing costs, land values and distance from jobs, so lower-priced homes turn up most often in three kinds of places.
- Inland California. The Inland Empire, the High Desert and the Central Valley. Our list of California cities where manufactured homes are still affordable says what to check in ten of them. Near the coast, a lower-priced home is usually an older home in a community, where space rent makes up more of the monthly cost.
- Rural and river-area Arizona. In Mohave County, around Kingman and Bullhead City, buyers find homes on their own lots as well as homes in communities. The two are financed differently even at the same price.
- Older communities in the metro areas. Around Phoenix and in Southern California’s inland valleys, long-established communities have older homes on rented spaces. Many are age-restricted, and some owners live there for only part of the year. Many programs and communities require owner-occupancy, so ask whether financing is available for your intended use before you buy.
What is for sale changes from week to week. Treat any count or price quoted for a city as a snapshot, including the ones on listing sites.
How to search at this price without overpaying
From budget to offer
- Start with the setup, not the price Decide which you are shopping for: homes on rented spaces, homes on land, or both. Each is a different loan and a different monthly cost.
- Talk with a lender before you tour Describe the kind of home, its likely age and where it sits, and ask which programs may fit. Pre-qualification is not final approval, but it tells you which homes are worth the drive.
- Screen each listing by phone The questions in the next section save wasted trips.
- Check the price against recent sales For homes in California communities, comparable sales reports show what homes in that community have sold for. They are sales data, not appraisals.
- Capture the details at the showing Photograph the data plate, and note the year, the manufacturer and the number of sections. A lender will ask for all three.
Questions to ask about a listing before you drive out
If the answers hold up, ask a specialist whether a home of that age and setup fits a current program before you make an offer: contact us. This article is general information, not legal advice.