Manufactured Home Loans in Fresno and the Central Valley: Buyer Guide
Local financing details: Mobile & Manufactured Home Loans in Fresno, California
Buying a manufactured home in Fresno or elsewhere in the central San Joaquin Valley follows the same steps as anywhere in California. What differs is how many buyers here are paid: by the season, by the load or by the crop. If that is you, the first question is whether your income counts. It can, when it is documented, and it is measured across a full year, not by your peak month.
Two other things shape a Valley budget: summer cooling, and the choice between a community space in town and a parcel in the county. Loan options in the city itself are on the manufactured home loans in Fresno page. All financing is subject to credit approval, and not all applicants or homes qualify.
Seasonal income is measured over the year, not the month you apply
A lender needs one monthly income figure to set against your monthly housing cost. For a salaried buyer that is simple. For a buyer who works most of the year and is laid off for the rest, the lender generally takes what you earned over the whole year, often looking at more than one year, and spreads it across twelve months.
Two things follow. A strong run of pay stubs in August does not mean you qualify on August’s pay. And applying in January, between seasons, does not by itself sink the file, provided your records show you going back to the same kind of work each year. What a lender looks for is a pattern: similar work and similar earnings, year after year.
How much history a file needs, and whether a gap or a change of employer matters, depends on the program. Ask before you shop.
How each kind of Valley income is documented
The records a lender asks for depend on how you are paid, and a household often has more than one kind of income.
Income types and the records that support them
| How you are paid | What documents it | What to know |
|---|---|---|
| Seasonal job with a paycheck: field crew, packing house, cannery, processing plant | Pay stubs for this season and W-2s from prior years | Several employers in one year is normal. Keep every W-2. |
| Unemployment benefits between seasons | Benefit statements, with your seasonal work history | Ask whether a program can count it. Do not assume it is added to your wages. |
| Paid on a 1099 or running your own operation: owner-operator, labor contractor, custom farm work | Federal tax returns with every schedule | The figure used is net profit after expenses, not gross receipts. |
| Farming your own or leased ground | Tax returns including Schedule F, the IRS form titled “Profit or Loss From Farming” | Farm expenses reduce the income a lender can count. |
| Cash with no records | Nothing a lender can use | Income that is not on a pay stub, W-2, 1099 or tax return generally cannot be counted. |
If you are self-employed, turning net profit into a monthly figure has steps of its own. Getting a loan with self-employed income walks through them.
The payment is due in the off-season too
Qualifying is one test. Living with the payment through the slow months is the other, and only you can run it. Add up the full monthly cost of the home: the loan payment, insurance, taxes, utilities, and space rent if the home is in a community. Space rent is the monthly rent you pay for the homesite under a home you own.
Then set that total against your averaged monthly income, not a peak-season check. The payment calculator estimates the loan portion. Its results are educational estimates, not a loan offer.
Utilities deserve their own line. Summer afternoons above 100 degrees are a normal part of the year in Fresno, according to National Weather Service climate records, so cooling is likely to be one of your largest utility costs. Before you make an offer:
- Ask the seller for the last twelve months of electric and gas bills.
- Find out what cools the home (central air, a heat pump or an evaporative cooler on the roof) and how old it is.
- Have the inspector look at the ducts under the home, the insulation and the roof, which are common places for cooled air to be lost.
- Note the afternoon sun. Awnings, a carport on the west side or a shade tree change how hard the system works.
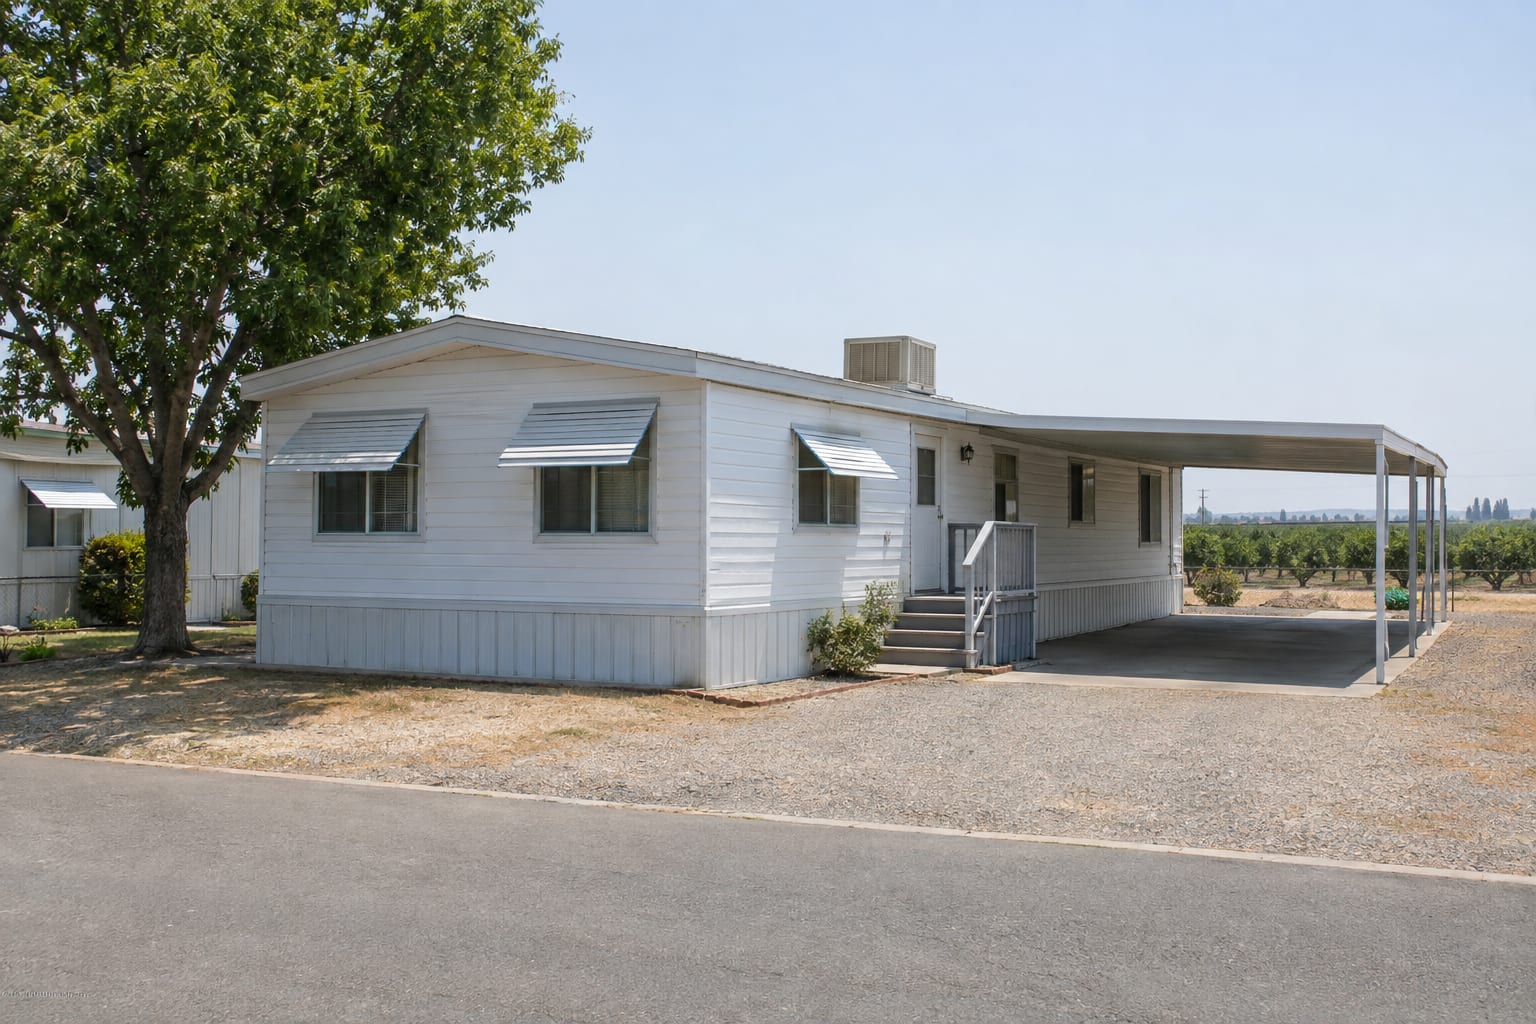
Preparing a home for summer heat covers the maintenance side.
A community space in town or a parcel in the county
Valley buyers usually end up choosing between two setups, and they are financed and reviewed differently.
Two Valley setups compared
| Home in a community | Home on its own parcel | |
|---|---|---|
| What you own | The home; the space is rented | The home and the land |
| Monthly housing cost | Loan payment, space rent, insurance, utilities | Loan payment, property tax, insurance, utilities, well and septic upkeep |
| Who else reviews you | The community, through its own resident application | No community; the site itself is reviewed |
| Water and sewer | Supplied through the community or the city | Often a private well and a septic system |
| How the home is titled | Personal property | Personal property, or real property once it is affixed to the land and recorded |
California titles manufactured homes through HCD, the Department of Housing and Community Development, not the DMV. HCD’s registration and titling page is the official source.
For a seasonal earner, the community’s review matters as much as the lender’s. A community runs its own resident application and decides for itself what proof of income it accepts. Community approval and loan approval are separate reviews, and you need both. Ask the office what it wants to see before you apply.
On a rural parcel, the checks move to the land. Fresno County’s Environmental Health Division issues well construction permits in the unincorporated county, and its frequently asked questions say it does not routinely inspect existing private wells. The condition of a well is yours to establish: ask for the well records and a current water test.
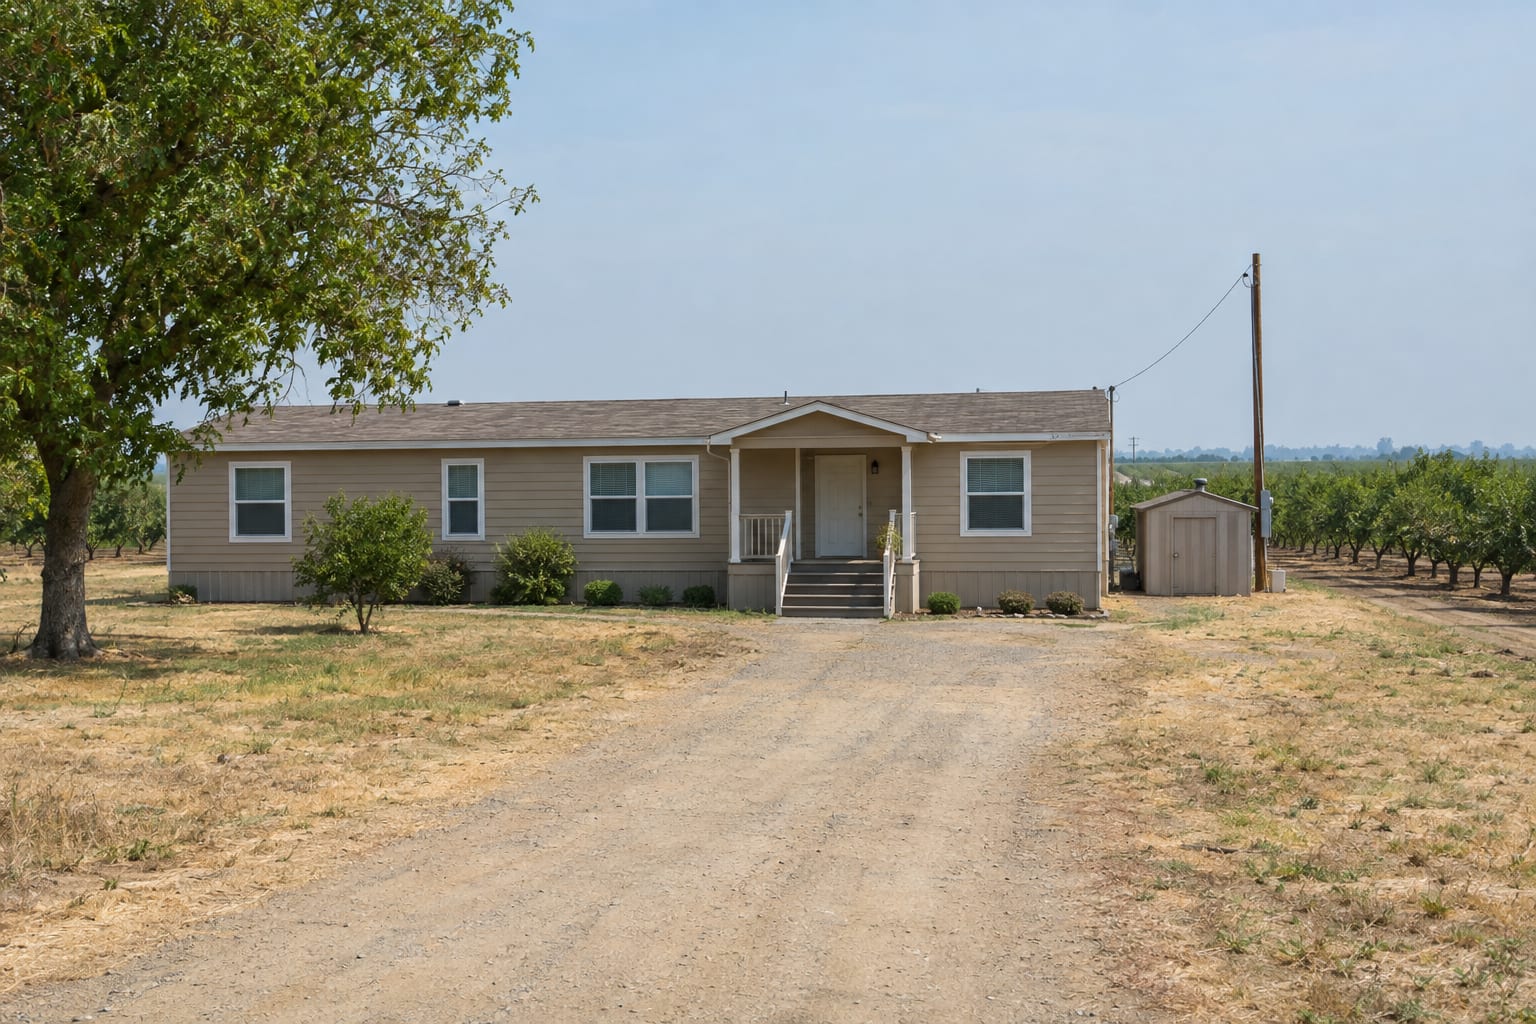
The Kern County guide goes through wells, septic systems and road access one question at a time, and the same questions apply anywhere in the Valley.
Inside Fresno city limits, the city oversees the parks
Two local facts are worth knowing if the community you like is inside the City of Fresno. Since July 1, 2021, the city has enforced California’s Mobilehome Park Act at parks within city limits, which includes park maintenance inspections. The city also has a mobilehome park rent review and stabilization ordinance, with a commission that hears rent increase applications. Both are described on the city’s mobilehome parks page.
Rules differ in Clovis, in other Valley cities and in the unincorporated county. Ask each community which jurisdiction it is in and whether a local rent ordinance applies to the space you would rent, and get the current space rent and the lease terms in writing.
Have the income conversation before you tour homes
If your income is seasonal, start with your paperwork and then look at homes. Bring last year’s W-2s or tax return and a description of your work year when you talk with a specialist at Santiago Financial, Inc., and ask what your file would need. Pre-qualification is not final approval, but it tells you which price range your records support before you choose a home.