Manufactured Home Loans in Ventura County: What Coastal Buyers Should Know
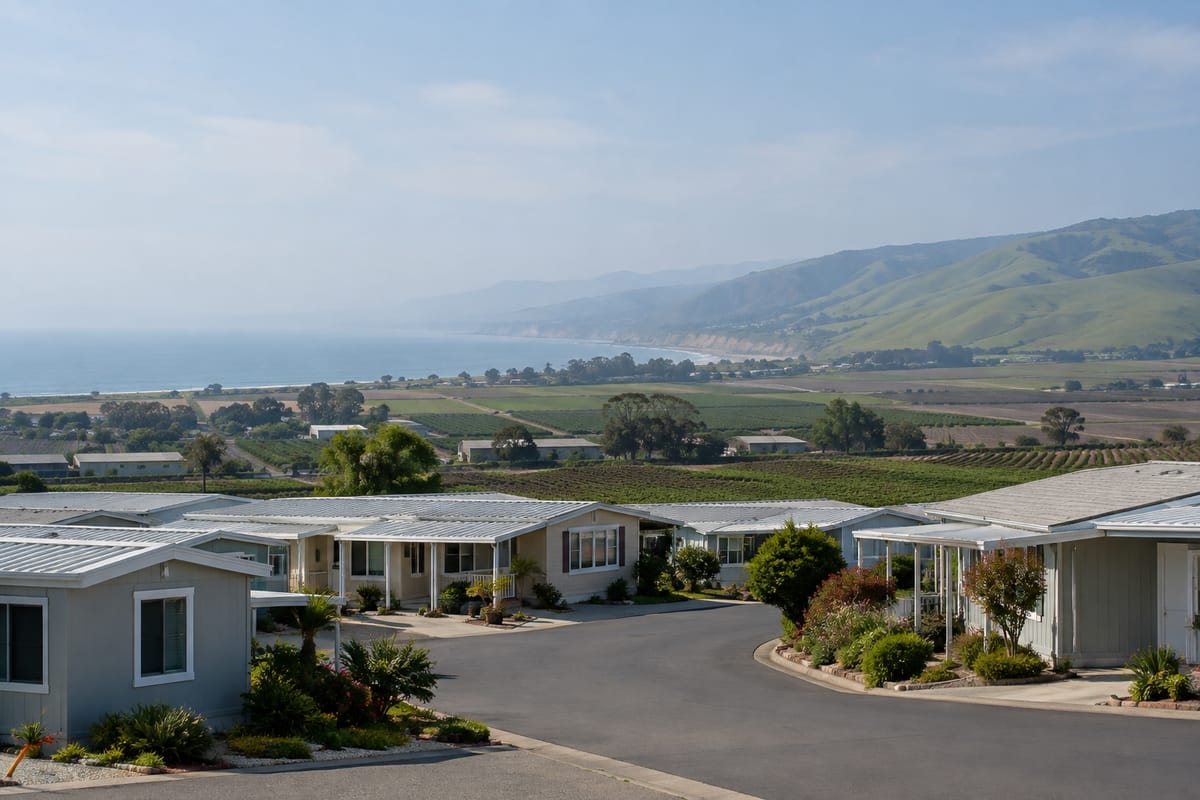
Buying a manufactured home in coastal Ventura County usually means buying a home in a land-lease community: you own the home and rent the space it sits on. Compared with an inland purchase, three things need more attention here. Space rent tends to be higher near the water, many of the homes are older, and insurance has to be checked by address.
Ventura County adds a fourth. The rules on space rent increases depend on which city the park is in, or whether it sits outside city limits altogether. Santiago Financial, Inc. serves manufactured and mobile home buyers throughout California, Ventura County included.
Local space-rent rules depend on where the park sits
California’s Mobilehome Residency Law applies in every park in the state. HCD, the state Department of Housing and Community Development, notes on its page about your rights as a mobilehome park resident that cities and counties often add their own ordinances, including rent control. In Ventura County several have, each with its own office.
Who publishes the local space-rent rules
| If the park is in | Look at |
|---|---|
| An unincorporated area, outside any city | The county’s Mobile Home Park Rent Control Program |
| The city of Ventura | The city’s Mobile Home Rent Stabilization page |
| Oxnard | The city’s Mobile Home Rent Stabilization page |
| Santa Paula | The city’s Mobile Home Rent Stabilization page |
| Camarillo, Ojai, Thousand Oaks or another city | That city’s housing or community development office |
Read the rules on the official page. They are not summarised here, because they change and because not every space is necessarily covered. Ask the office about the specific space you are considering.
Space rent is the first number to get in writing
Space rent is paid to the community on top of the loan payment. Near the coast it tends to be higher, because the land is worth more, and it is part of the monthly housing cost a lender compares with your income.
Ask the office for the rent you would pay as the new resident, what it includes, and the history of increases. How space rent affects what you can afford shows how to compare two communities on the full monthly cost.
A home on a rented space is financed by itself, as personal property, with a home-only loan, also called a chattel loan. The space rent is not part of that loan, but it is part of every month.
The monthly costs of a home in a community, and who to ask
| Cost | Paid to | Ask |
|---|---|---|
| Loan payment | The lender | What it would be for this home and loan amount |
| Space rent | The community | The rent for a new resident, what it includes, past increases |
| Utilities | The community or the utility company | Which are billed through the park and which directly |
| Insurance | The insurer | A quote on this address, and whether flood cover is separate |
| Property tax or HCD fee | The county or HCD | Which one applies to this home, and whether it is paid up |
On the last row: manufactured homes first sold new on or after July 1, 1980 are on local property tax, and older homes generally pay an annual in-lieu fee to HCD instead. The State Board of Equalization explains both in its manufactured homes FAQ.
Older communities mean older homes to check
Many communities near the coast have been in place for decades, and the homes in them range from recent replacements to homes built in the 1970s or earlier. Ask the year first.
The dividing line is June 15, 1976, when the federal HUD Code took effect. A home built on or after that date is a manufactured home. One built before it is, technically, a mobile home. Programs treat the two differently, so ask whether financing is available for a home of that age before you spend money on it. Not every home qualifies.
A lender’s value review, whether an appraisal or comparable sales, establishes what the home is worth. It is not an inspection. On an older home near the ocean, an inspection that includes the underside is worth the cost, because salt air corrodes the steel frame, piers and tie-downs. The coastal checklist for homes near the beach lists what to look at.
Prices vary from one coastal community to the next, so recent sales in the same community are the most useful guide to an offer. Our comparable sales reports cover California communities and show what similar homes sold for. They are not appraisals.
Wildfire, flood and tsunami maps take a few minutes each
Ventura County has all three exposures within a short drive of each other. The Thomas Fire started north of Santa Paula in December 2017 and destroyed more than 1,000 structures across Ventura and Santa Barbara counties, according to CAL FIRE. Low ground near the coast and the rivers raises the flood question, and the shoreline has mapped tsunami hazard areas.
Look up the address on each map:
- Wildfire: the State Fire Marshal’s Fire Hazard Severity Zone maps.
- Flood: the FEMA Flood Map Service Center. FEMA notes that most homeowners insurance does not cover flood damage; flood insurance is a separate policy.
- Tsunami: the California Geological Survey’s tsunami hazard area maps, which include Ventura County.
Then get an insurance quote on that address before you make an offer. A lender requires insurance on the home before closing, and a home that is hard to insure can stop a purchase at the last stage. Our insurance team can quote manufactured home insurance.
A home on its own land is a different loan
Away from the coast, in the valleys and rural parts of the county, some manufactured homes sit on land the owner also owns. There the home and the land can often be financed together as real property, with land-and-home financing.
The questions change with it: how the home is attached to the land, how it is recorded, and what serves the lot, such as a well or city water, septic or sewer, propane or gas, and a private road. In California, HCD Form 433A is used to report the installation of a manufactured home on a foundation system and is recorded with the county when applicable. It is an important property record, but it does not by itself guarantee financing.
Before you make an offer in Ventura County
Pre-qualifying before you shop tells you what range to look in. It is not final approval, and all financing is subject to credit approval. This article is general information, not legal, tax or insurance advice.