Manufactured Home Insurance Before Closing: What to Ask Your Agent
Proof of a homeowners policy is a condition of funding on a manufactured home loan, and the quote comes back with fewer follow-up calls when the agent gets every detail about the home on the first call rather than the third. Gather the facts before you dial, ask your loan specialist what the lender needs on the policy, and start the week your offer is accepted. In some locations the answer takes time, and a quote that comes back high, or does not come back, is better learned early.
Why premiums have been rising and how the premium affects the loan review is covered in rising insurance costs. This article is about preparing the quote and the proof-of-coverage file.
What to have ready for the agent
The agent will ask about the home, the site, you and the loan. Write the answers on one page before you call.
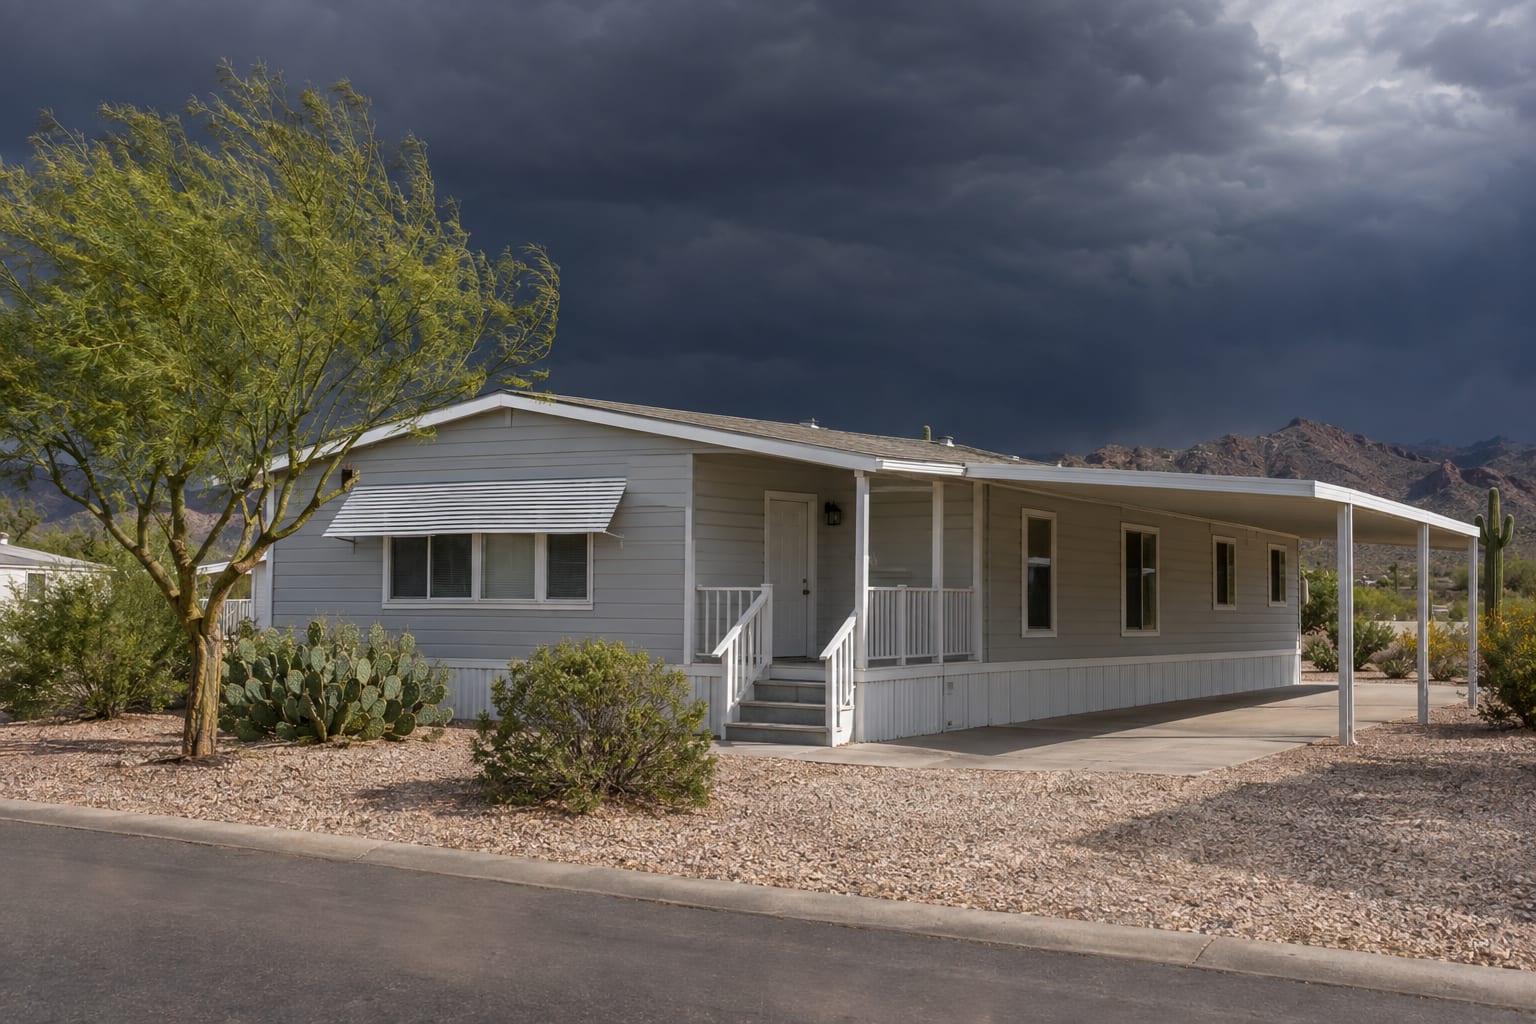
Most of the home facts are on the data plate, the paper sheet inside the home that lists the manufacturer, serial number, build date and the wind, snow and thermal zones the home was built for. Photograph it at the showing. The additions line matters more than buyers expect; buying a home with an added room, deck or carport explains why the insurer asks.
What the lender needs from the policy
The lender does not need to approve your insurer, but it does need the policy to say certain things. Ask your specialist for the exact wording before the agent writes it, because a declarations page that names the lender wrong has to be reissued.
What the lender looks for on the proof of insurance
| Item | Why it matters |
|---|---|
| The home described correctly: address, year, serial number, sections | The policy has to cover the home the loan is on |
| The lender named as lienholder or loss payee, in the lender’s wording | So the lender is paid on a covered loss to its collateral |
| An effective date on or before the funding date | Coverage cannot start after the loan does |
| Coverage that meets the lender’s requirement | Ask what the requirement is; it varies by program and loan |
| The first premium paid, or shown on the settlement statement | The premium is a prepaid item at closing |
The first year’s premium is one of the prepaid items that make up cash to close; closing costs beyond the down payment shows where it sits on the statement.
Questions to ask the agent
The quote is a number; these questions are what the number is made of.
- Is this replacement cost or actual cash value? Replacement cost pays to replace the home with one of similar kind and quality; actual cash value deducts depreciation, which on an older home can leave a large gap. Ask which the lender requires.
- What is the deductible, and are there separate ones for wind or fire? A low premium with a high deductible is a different product.
- What is excluded? Flood is usually a separate policy. Ask how the policy treats wildfire in California and wind, hail and monsoon water in Arizona, and whether the home’s zone affects it.
- Does the home’s age or any addition change the quote or the availability? Some insurers want an inspection on an older home before they will write it.
- Is the quote firm, and for how long? A quote that lapses before closing has to be requoted.
- Does the policy cover the additions and the carport, or only the home? Ask it directly.
Timing: start when the offer is accepted
From accepted offer to proof of coverage
- Ask your specialist what the lender needs on the policy and how it wants the proof delivered.
- Gather the home facts from the data plate and the seller, including additions.
- Call the agent with the one-page list and the lender’s wording.
- Compare the quotes on coverage basis, deductibles and exclusions, not premium alone.
- Bind the policy with an effective date on or before funding, and send the declarations page to the lender and escrow.
- Keep the policy and the receipt with your home records; a refinance will look at them again.
Santiago Financial, Inc. can also quote manufactured home coverage through its own insurance team. Whoever writes the policy, the file needs the same things, and all financing is subject to credit approval.