Manufactured Home Inspection vs. Appraisal: What Buyers Should Know
Plan on both, because they answer different questions. An inspection is something you order to learn the home’s condition before you are committed to buying it. An appraisal or value review is ordered for the lender to support what the home is worth, and the loan amount is measured against it.
Neither does the other’s job. An appraiser is not looking for a leaking water heater, and an inspector will not tell you what the home should sell for. On a manufactured home the inspection deserves particular attention, because much of what holds the home up is out of sight behind the skirting.
Two reports that answer two different questions
Inspection compared with appraisal
| Feature | Inspection | Appraisal or value review |
|---|---|---|
| Question it answers | What condition is the home in? | What is the home worth? |
| Who orders it | You | The lender, as the program requires |
| Who it is written for | You | The lender; you are entitled to a copy |
| Who does it | A home inspector you choose | An appraiser, or a review of comparable sales |
| When | Before you are committed to the purchase | After you apply, during the loan review |
| Part of the loan? | Usually your choice | Yes, in some form |
| What you receive | A written list of defects and items to watch | An opinion of value |
For a loan secured by a first lien on a home, federal rules require the lender to give you a copy of the appraisal and any other written valuation it obtains, and the rule’s definition of a dwelling includes a manufactured home whether or not it is attached to land (Regulation B, section 1002.14). The Consumer Financial Protection Bureau explains the right to a copy in what appraisals are and why to read them. Ask your lender who pays for the appraisal and when.
What an inspection covers on a manufactured home
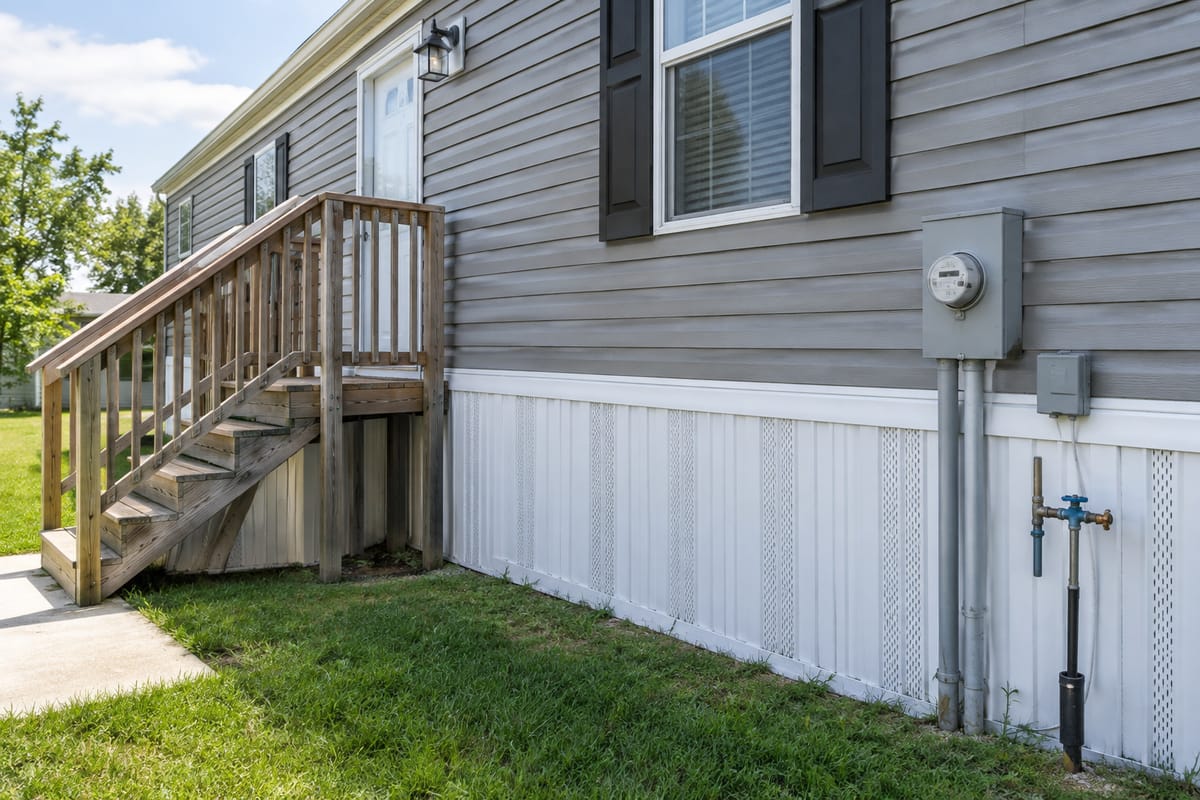
A manufactured home has a roof, plumbing, wiring, heating and cooling like any house, and an inspector checks all of them. What is different is underneath. The home is built on a steel frame that rests on piers and is held in place by tie-downs, and a multi-section home is two or more sections joined on site. Those are the places a general house inspection can miss.
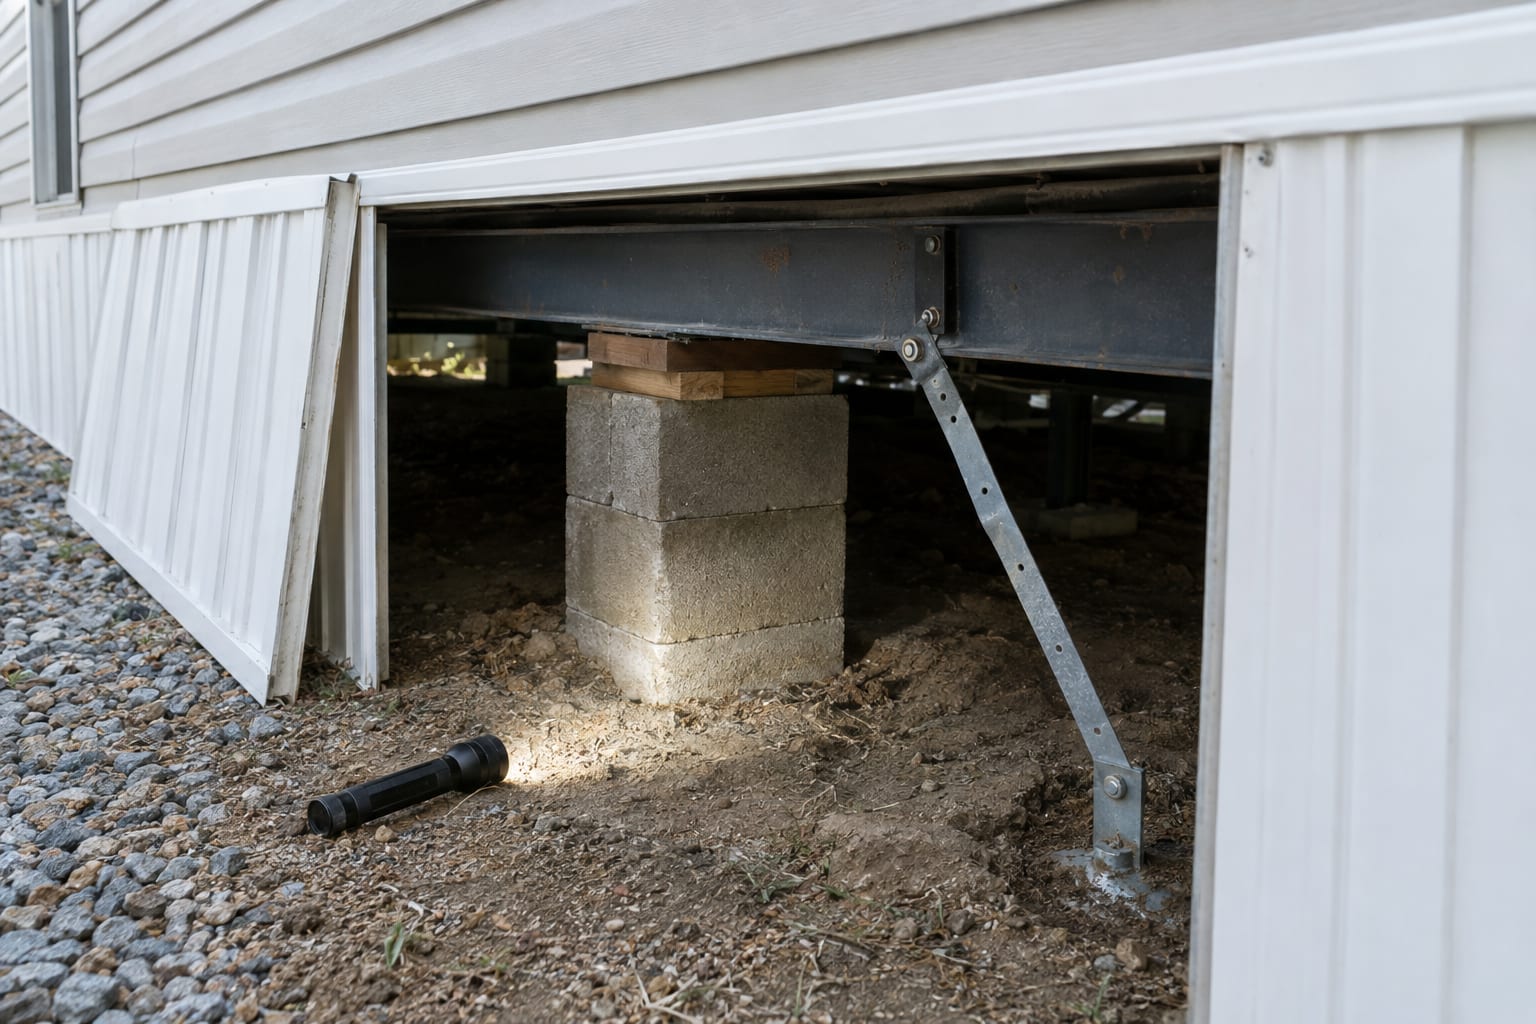
Before you hire an inspector, ask how many manufactured homes they have inspected and whether going under the home is included. Arizona certifies home inspectors through its State Board of Technical Registration, which publishes general information on home inspections.
While the inspector is there, find the home’s data plate and HUD labels and photograph them. HUD label, data plate and serial number shows where to look, and the before-you-shop checklist has a line for each.
What an appraisal or value review covers
An appraisal is an independent opinion of what the home, or the home and land, is worth. For a home on land you are buying, the appraisal covers the home and the land together. For a home in a land-lease community, where you own the home and rent the space, the review looks at the home itself and is usually built on comparable sales of similar homes.
An appraiser does note the home’s overall condition and anything obvious that affects value, and a lender may ask for a problem to be fixed before closing. But the appraiser does not take off a skirting panel, test the outlets or run the water. A clean appraisal says nothing about the supports. If you own the home and it is about to be appraised, preparing a home for an appraisal covers what an appraiser looks at.
When there are few sales to compare
Value is supported by recent sales of similar homes, and in a small community only a handful of homes may have sold. The ones that did may differ from yours in ways that change the price.
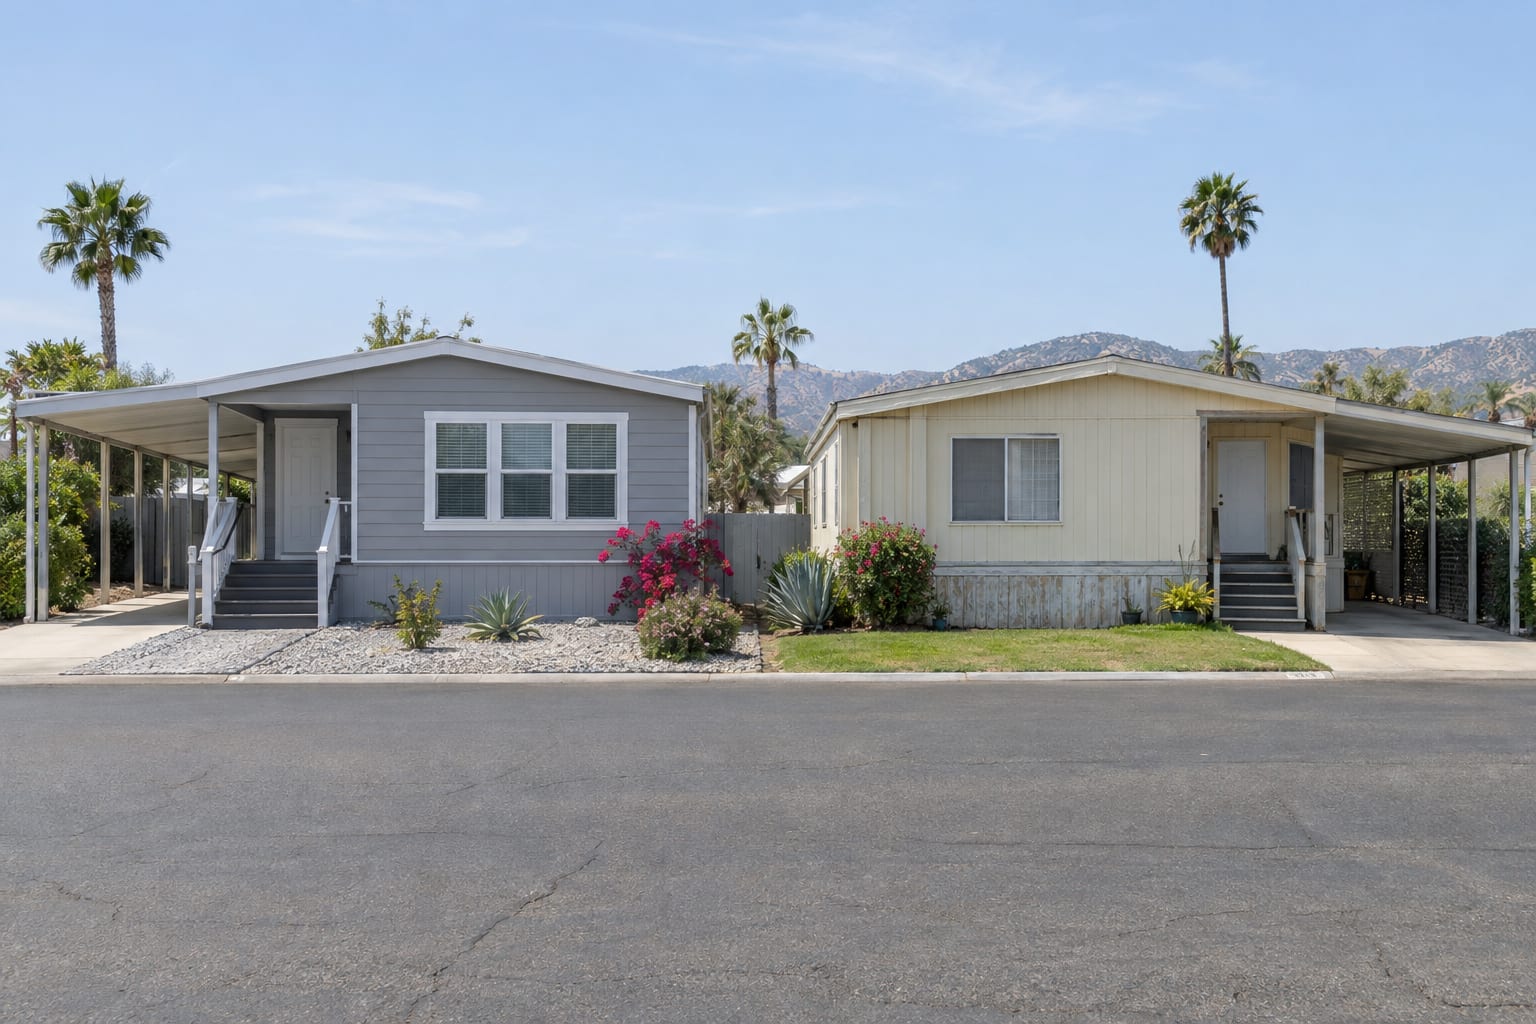
A useful comparison looks past the sale price to the home’s year, manufacturer and size, its condition and improvements, where it sits in the community, and the date and terms of the sale. Differences in space rent between communities also affect what buyers will pay.
Santiago Financial, Inc. offers comparable sales reports for California parks and communities, which list reported sales in a selected park. A report is a starting point for judging a price before you make an offer. It is not an appraisal, and a lender may still require its own appraisal or value review.
What to do with the results
Each report leaves you with a decision, and the options are different for each.
If the inspection finds problems
You have three choices: accept the home as it is, ask the seller to make a repair or adjust the price, or step back from the purchase if your agreement allows it. That last choice exists only if the agreement gives you time to inspect, so ask for that before you sign. In a private sale you and the seller write the agreement yourselves, as the steps for a private-seller purchase explain.
Tell your loan specialist about anything serious as well. The home is the collateral for the loan, and a significant defect is better raised early than discovered late.
If the value comes in below the price
The loan is measured against the supported value, not the price you agreed with the seller.
If you believe the value missed relevant sales, ask your lender how to submit additional comparable sales for review. The lender decides what happens with them. If no arrangement works, your purchase agreement decides whether you can cancel.
If both come back clean
Keep the reports with your home records. The inspection doubles as a maintenance list for your first year, and the same items are worth rechecking every year with a spring inspection checklist.