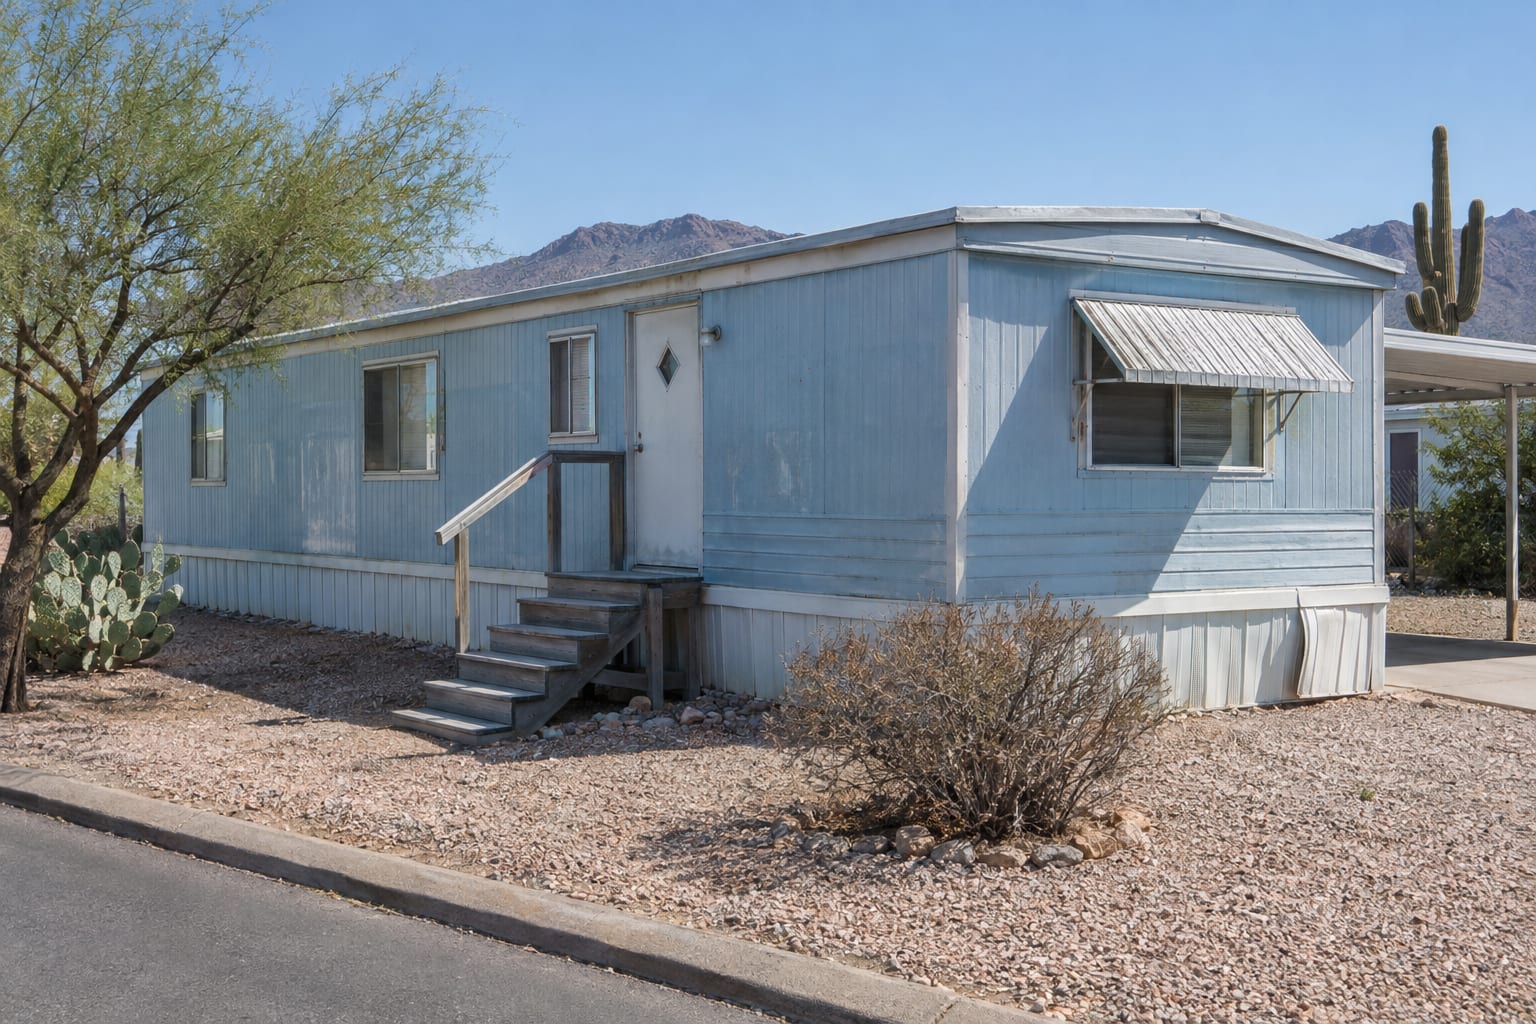
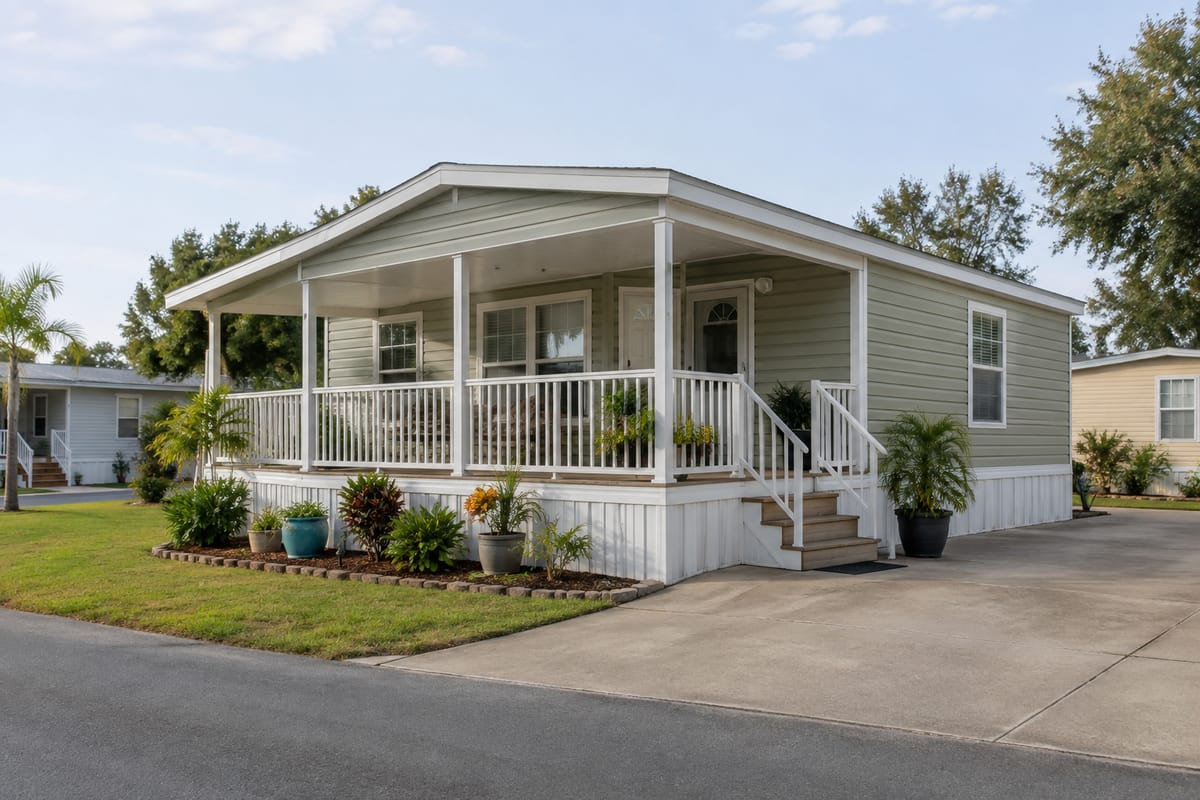
Fixer-Upper vs Turnkey Manufactured Homes: Which Is the Smarter Buy?

A fixer-upper is the smarter buy only when its price plus the full cost of finishing it comes in clearly below a comparable move-in-ready home, and you have the cash to do the work. The second condition decides most cases, because repairs are generally paid for from savings, not from the purchase loan. If the totals are close, or the repair money would come out of the same savings as your down payment, the turnkey home is usually the safer choice.
Compare the cost to finish, not the asking price
A lower asking price is only the first line of the sum. Fill in every line below for the fixer-upper before you compare it with the turnkey home’s price.
Cost-to-finish worksheet
| Line | Where the number comes from |
|---|---|
| Purchase price | The price you expect to agree, not the list price |
| Repairs before you can move in | Written quotes for the roof, floors, plumbing, electrical, heating and cooling |
| Repairs due soon after | Items the inspection report says are near the end of their life |
| Permits and inspections | The permitting agency’s fees and your contractor’s quote |
| Housing costs during the work | Space rent on the new home plus what you pay where you live now |
| Contingency | A cushion you set for what opening up floors and walls reveals |
| Total cost to finish | The sum of the lines above |
Repair prices vary widely by home, region and contractor, which is why no typical figures appear here. Only a written quote for the specific home tells you anything.
How the two compare beyond price
Fixer-upper and turnkey side by side
| What differs | Fixer-upper | Turnkey |
|---|---|---|
| Price | Lower, reflecting the condition | Higher |
| Cash beyond the down payment | Repairs, permits and housing costs during the work | Moving costs and small fixes |
| Move-in | After the essential repairs | Once the purchase closes |
| Unknowns | More: hidden damage, quotes that grow | Fewer, though an inspection still matters |
| Loan review | Condition problems may have to be corrected before closing | Fewer condition questions |
| Resale | Depends on the quality of the work and its permit record | Depends on upkeep, the community and the location |
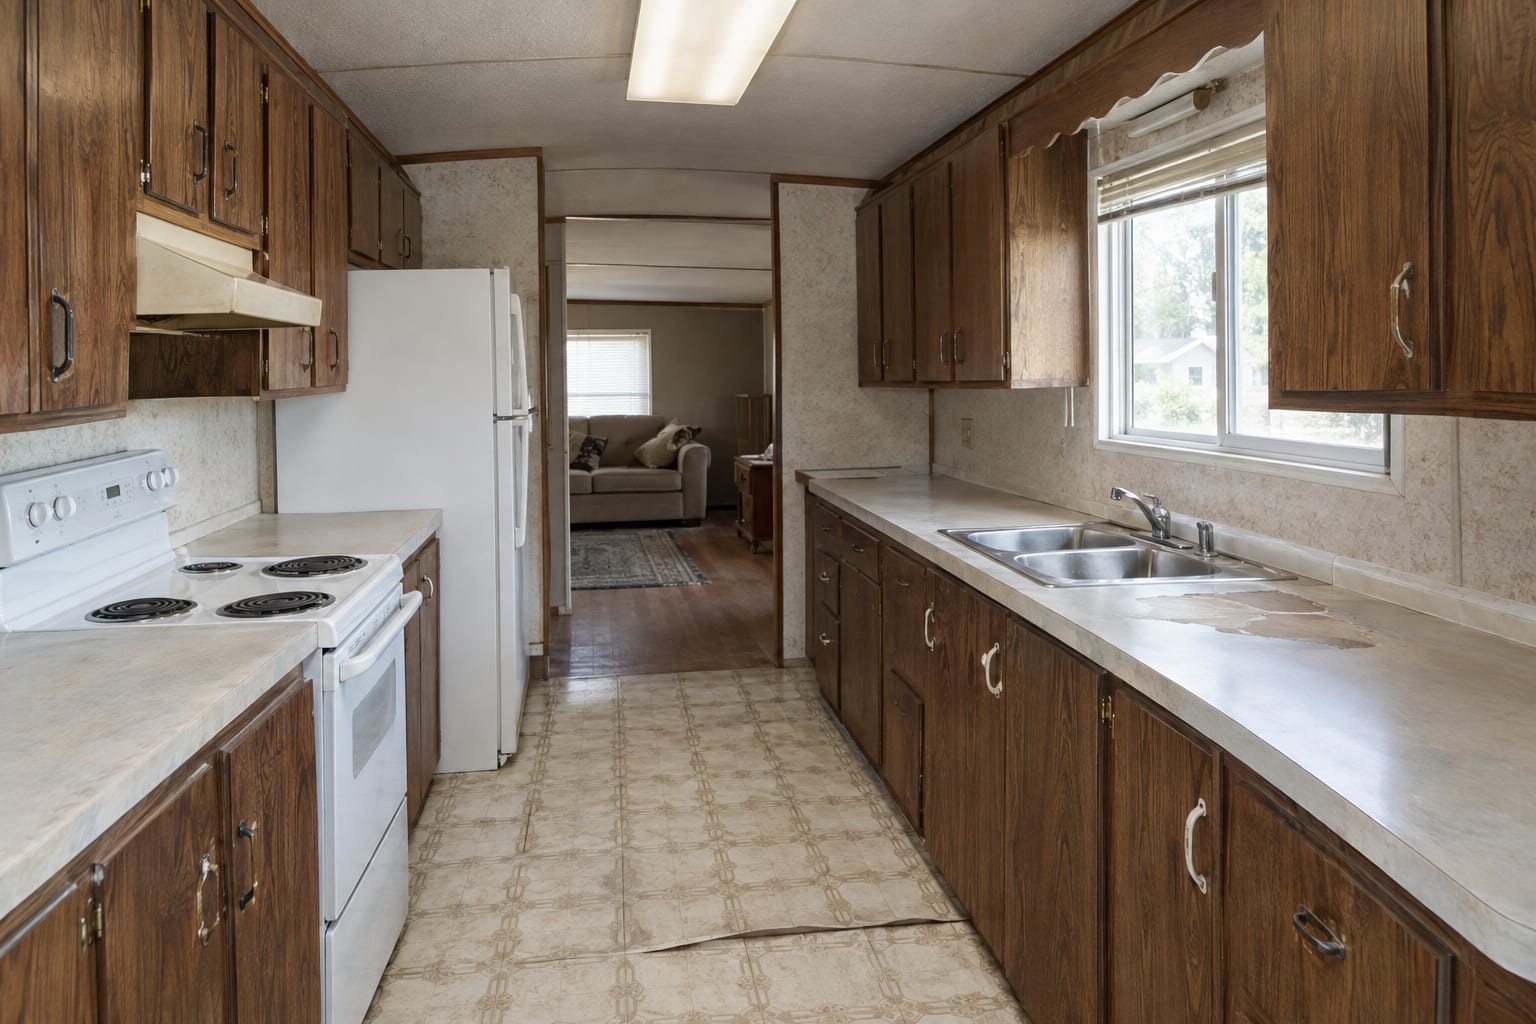
Whether a home that needs work can be financed at all, and which repairs have to happen before closing, is covered in loan options for a fixer-upper.
Red flags that turn a bargain into a problem
Dated finishes are cheap to live with. The items below are not, and several of them affect whether the home can be insured or financed.
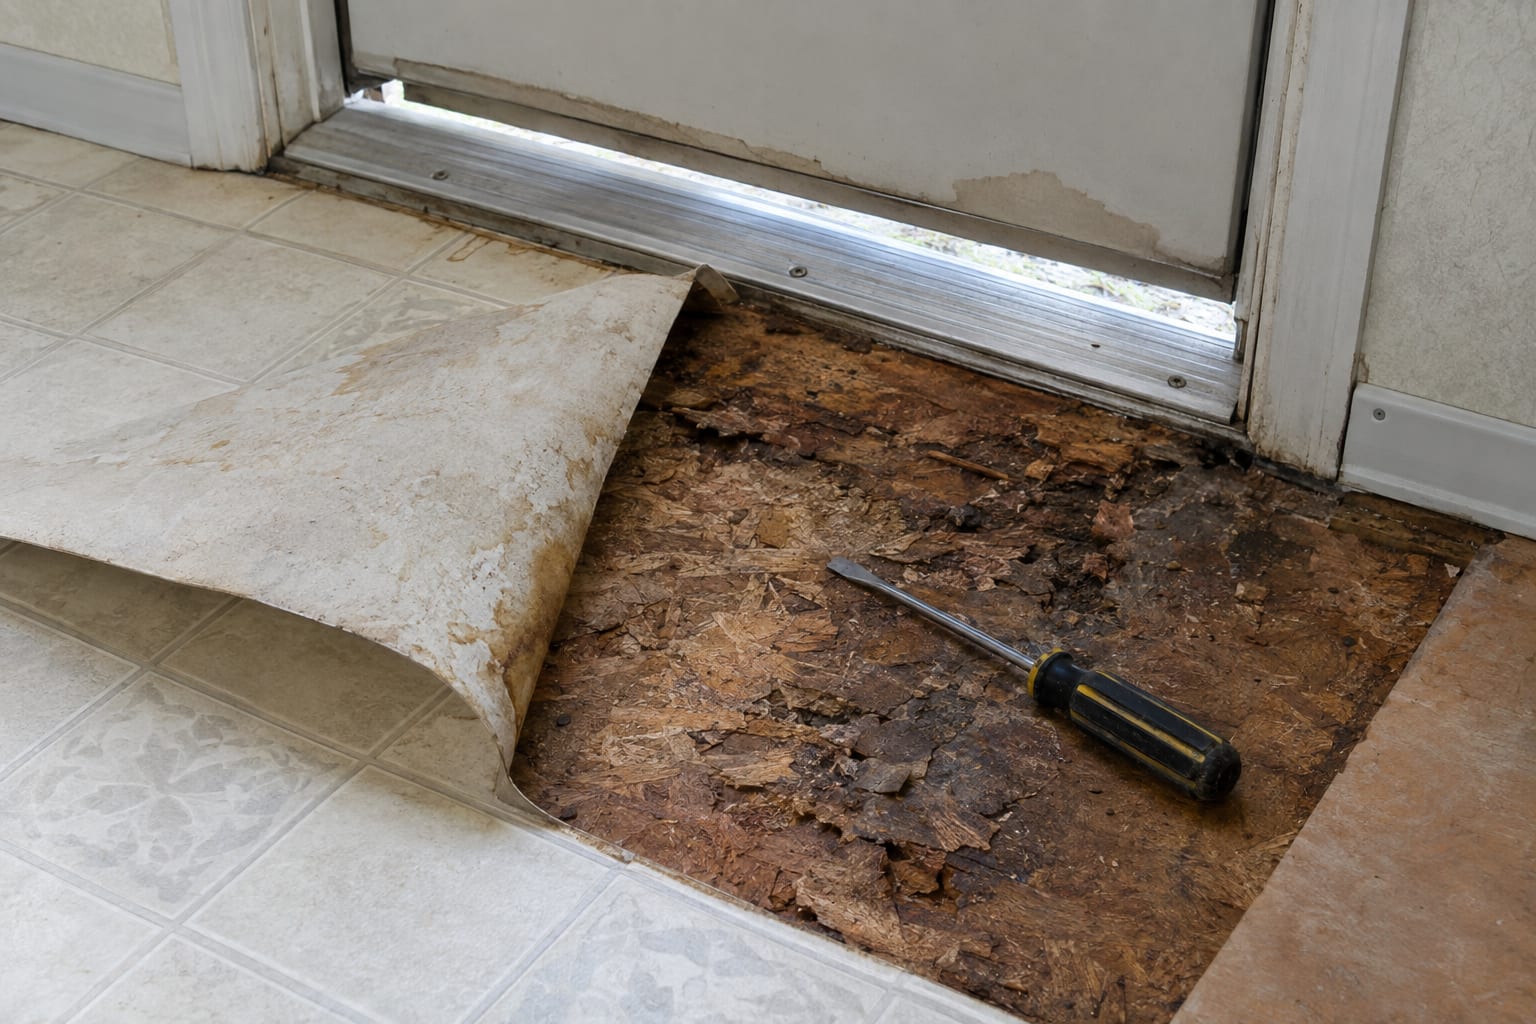
One of these does not always end a purchase. Two or three on the same home usually mean the discount is smaller than the bill.
Who a fixer-upper suits
A fixer-upper tends to work for a buyer who has cash set aside beyond the down payment, who has the skills or a contractor experienced with manufactured homes, and who can live somewhere else until the essential work is done. It also helps to plan on staying, since you get the benefit of the work over the years you live there.
A turnkey home tends to suit a buyer whose savings are mostly committed to the down payment and closing costs, who needs to move in when the purchase closes, or who is buying a first home and does not want a project. Paying more for a finished home is a reasonable trade for knowing what it will cost.
Where the home sits matters too. In a community you pay space rent from the day you own the home, whether or not you can live in it, and the community may have rules about exterior work. Ask the office before you buy. On your own land you set the pace, though permits still apply.
Get an inspection and written quotes before you commit
Three steps turn a guess into a decision:
- Inspection. An inspector who knows manufactured homes will look at the roof, the floors and under the home. Inspection vs. appraisal explains why the lender’s value review does not replace it.
- Written quotes and permits. Ask each contractor which permits the job needs. In California, alterations to a home’s structural, fire safety, plumbing, mechanical or electrical systems generally require a permit from HCD. In Arizona, ask the Arizona Department of Housing.
- A check on finished value. For homes in California communities, comparable sales reports show what homes in the same park have sold for. They are sales data, not appraisals, and they do not predict what your home will be worth.
To compare the monthly cost of each option with space rent included, use the payment calculator. Its results are educational estimates, not a loan offer. If you buy the fixer-upper, remodeling ideas on a budget covers the lower-cost improvements to make once the essential repairs are done.