
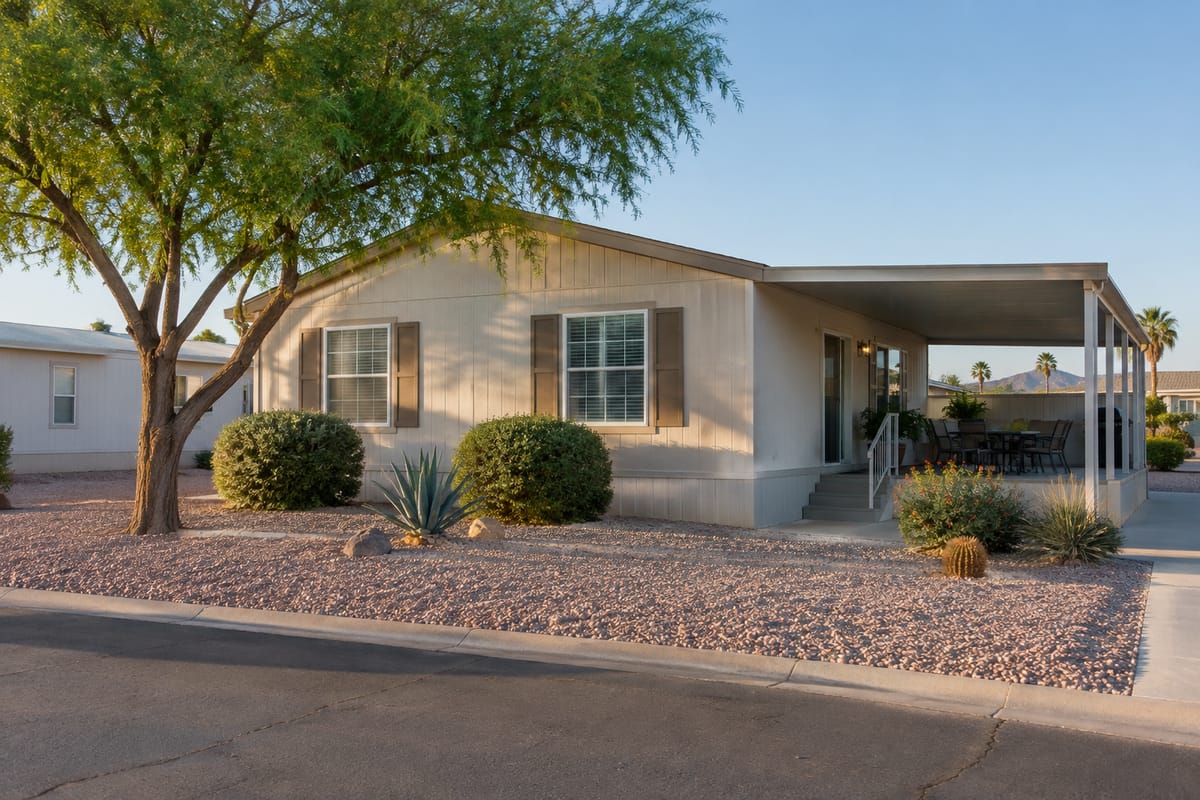
Chandler has a modest supply of manufactured homes. The U.S. Census Bureau’s 2020 to 2024 estimates count about 2,300 mobile homes among roughly 113,000 housing units, about one in fifty. (The survey counts manufactured homes under “mobile home”.) That is roughly nine times Gilbert’s count and a small fraction of Mesa’s. Homes come up for sale one at a time, and the first question about any listing is whether it sits on a rented space or comes with its lot.
Just south of the city line is Sun Lakes, an unincorporated community that the Census Bureau counts separately, with about 700 mobile homes among 10,200 units. A Chandler buyer who looks at both is comparing two kinds of purchase.
In a Chandler community you own the home, rent the space and finance the home on its own as personal property with a home-only (chattel) loan. In Sun Lakes the manufactured homes generally sit on lots the owners hold title to, so the loan can cover home and land, and association dues and property taxes take the place of space rent. The Arizona hub page explains both structures; this page covers what is specific to Chandler.
What changes between a Chandler community and a Sun Lakes lot
Two purchases a Chandler buyer may compare
| Question | Home in a Chandler land-lease community | Home sold with its lot, as in Sun Lakes |
|---|---|---|
| What you own | The home | The home and the lot |
| What you pay besides the loan | Space rent, utilities, insurance | Property taxes, insurance, association dues |
| How it is financed | Home-only loan on the home as personal property | Home and land together, if the home is recorded as real property |
| Who else reviews you | The community’s resident approval, separately from the loan | The homeowners association, under its recorded rules |
| Records | MVD title per section; Maricopa County Assessor’s personal-property roll | Deed to the lot; Affidavit of Affixture recorded with the Maricopa County Recorder |
Ask the seller or agent which one a listing is before you compare prices, because the loan, the documents and the monthly cost all follow from it. Sun Lakes is age-restricted, so ask for the written age policy as well. Buying a manufactured home in Sun Lakes explains the owned-lot side, and buying on leased land covers the questions to ask a Chandler community.
Title, taxes and records for a Chandler home
The MVD issues the titles, generally one per section (mobile home ownership). A home on a rented space is on the Maricopa County Assessor’s personal-property roll, and the Assessor requires a 504 property-tax clearance before a home is moved from one location to another.
For a Sun Lakes-style purchase, the record to look for is the Affidavit of Affixture, filed with the County Recorder after the title is surrendered, which makes the home real property; the Arizona affixture guide covers what it changes for the loan. Confirm current procedures with the agencies; this is general information, not legal or tax advice.
Heat, monsoon and the county’s flood maps
The Flood Control District of Maricopa County handles floodplain regulation for Chandler, so the district’s floodplain information page, with a map viewer and a request form, is where to check a Chandler address before you make an offer and where to learn whether flood insurance will be required.
Summer in Chandler is low-desert summer: the National Weather Service’s July climate summary puts the 1991 to 2020 normal July high at Phoenix Sky Harbor at 106.5°F. Get a year of electric bills from the seller and have the air conditioner, ducts and insulation inspected. The monsoon’s dust storms, thunderstorm winds and flash floods are the reason to look hard at the carport, awnings, roof and tie-downs.
Questions to settle before you make an offer in Chandler
Nearby areas
Gilbert borders Chandler to the east and has far fewer manufactured homes; Tempe is to the north and Mesa, with the East Valley’s largest supply, to the northeast. If nothing fits, Apache Junction and, to the south in Pinal County, Casa Grande have more manufactured homes than Chandler.
Each application is reviewed on its own, and all financing is subject to credit approval. Confirm agency procedures and community rules before you rely on them, because they change.