
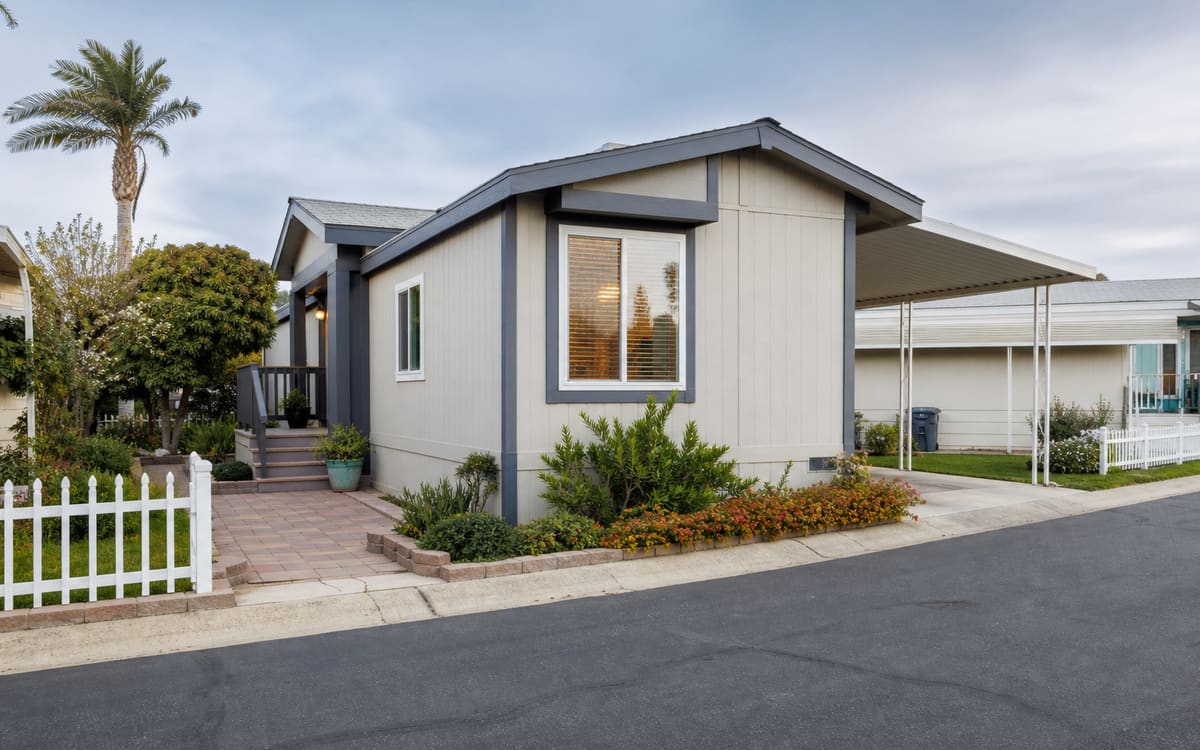
A manufactured home in Gardena usually means a home in a mobilehome park: you buy the home, lease the space under it, and pay space rent every month on top of the loan payment. That makes a Gardena purchase a total-monthly-cost decision, and it makes the city’s rent rules part of what the home will cost you to own.
The loan itself follows the statewide pattern the California hub describes: the home is financed on its own as personal property with a chattel loan, HCD holds the title, and the park’s resident approval is a separate review from the lender’s.
What this page adds is the Gardena-specific part: a city ordinance that reaches park spaces, the county records that must be clean before HCD will transfer the title, and the arithmetic of comparing two parks. Santiago Financial, Inc. finances homes in parks like these and reviews every application individually.
Gardena has its own rent mediation ordinance, and it covers park spaces
Gardena is one of the South Bay cities with a local rent rule that applies to mobile home park spaces. The City of Gardena’s Rent Mediation Board ordinance sets notice requirements for rent increases and a mediation and hearing process for increases above a threshold, and the city’s page states the notice period that applies to mobile home park tenants. Read that page yourself rather than relying on a summary; this is general information, not legal advice.
State law sits underneath it. California’s Mobilehome Residency Law applies in every park, and HCD runs a Mobilehome Residency Law Protection Program for certain disputes between homeowners and management.
One caution on geography. Gardena’s eastern neighbour is the City of Los Angeles’s Harbor Gateway corridor, where the Los Angeles Housing Department applies the city’s Rent Stabilization Ordinance to park spaces, and Los Angeles County’s mobilehome rent ordinance covers unincorporated county land only. A park with a Gardena mailing address can sit in any of the three, so ask the park’s management which jurisdiction it is in before you compare rent histories.
The records that must be clean before HCD will transfer the title
Who holds which record for a Gardena park home
| Record | Who holds it | What to confirm |
|---|---|---|
| Title or registration | HCD Registration and Titling | The seller’s name is on it and there are no unreleased liens |
| Property tax status | Los Angeles County Treasurer and Tax Collector | Whether the home is on local property tax and needs a tax clearance certificate |
| HUD label and data plate | The home itself | A construction date on or after June 15, 1976, and a data plate that matches the home |
| Space lease and rent history | The park’s office | Current rent, what it includes, the increase history and the lease term |
The tax row depends on the home’s age. A home first sold new on or after July 1, 1980 is on local property tax, as the State Board of Equalization explains, and HCD will not transfer its title until the county issues a certificate confirming the taxes are current. Older homes may still pay HCD’s annual fees instead. California HCD title basics covers what a clean transfer looks like.
Comparing two Gardena parks on the full monthly cost
Space rent is not part of the loan, but it is part of the monthly housing cost a lender compares with your income, so it is verified during the review. Two homes at the same price in different parks can cost very different amounts to own, and the difference compounds every year you stay.
For the loan side of the figure, enter your own numbers in the payment calculator; the results are educational estimates, not a loan offer. How space rent affects what you can afford walks through the comparison in more detail.
Nearby areas
Nearby guides cover Torrance, where the question of which jurisdiction a park sits in gets its own table, and Long Beach. Hawthorne, Lawndale and Carson are served without a page of their own; we finance manufactured homes throughout California.
If you are weighing two parks, ask a specialist how each one’s space rent would figure in the loan review before you choose: talk with a specialist. Pre-qualification is not final approval, and not all applicants or properties qualify.