Can Land You Already Own Help With a Manufactured Home Down Payment?
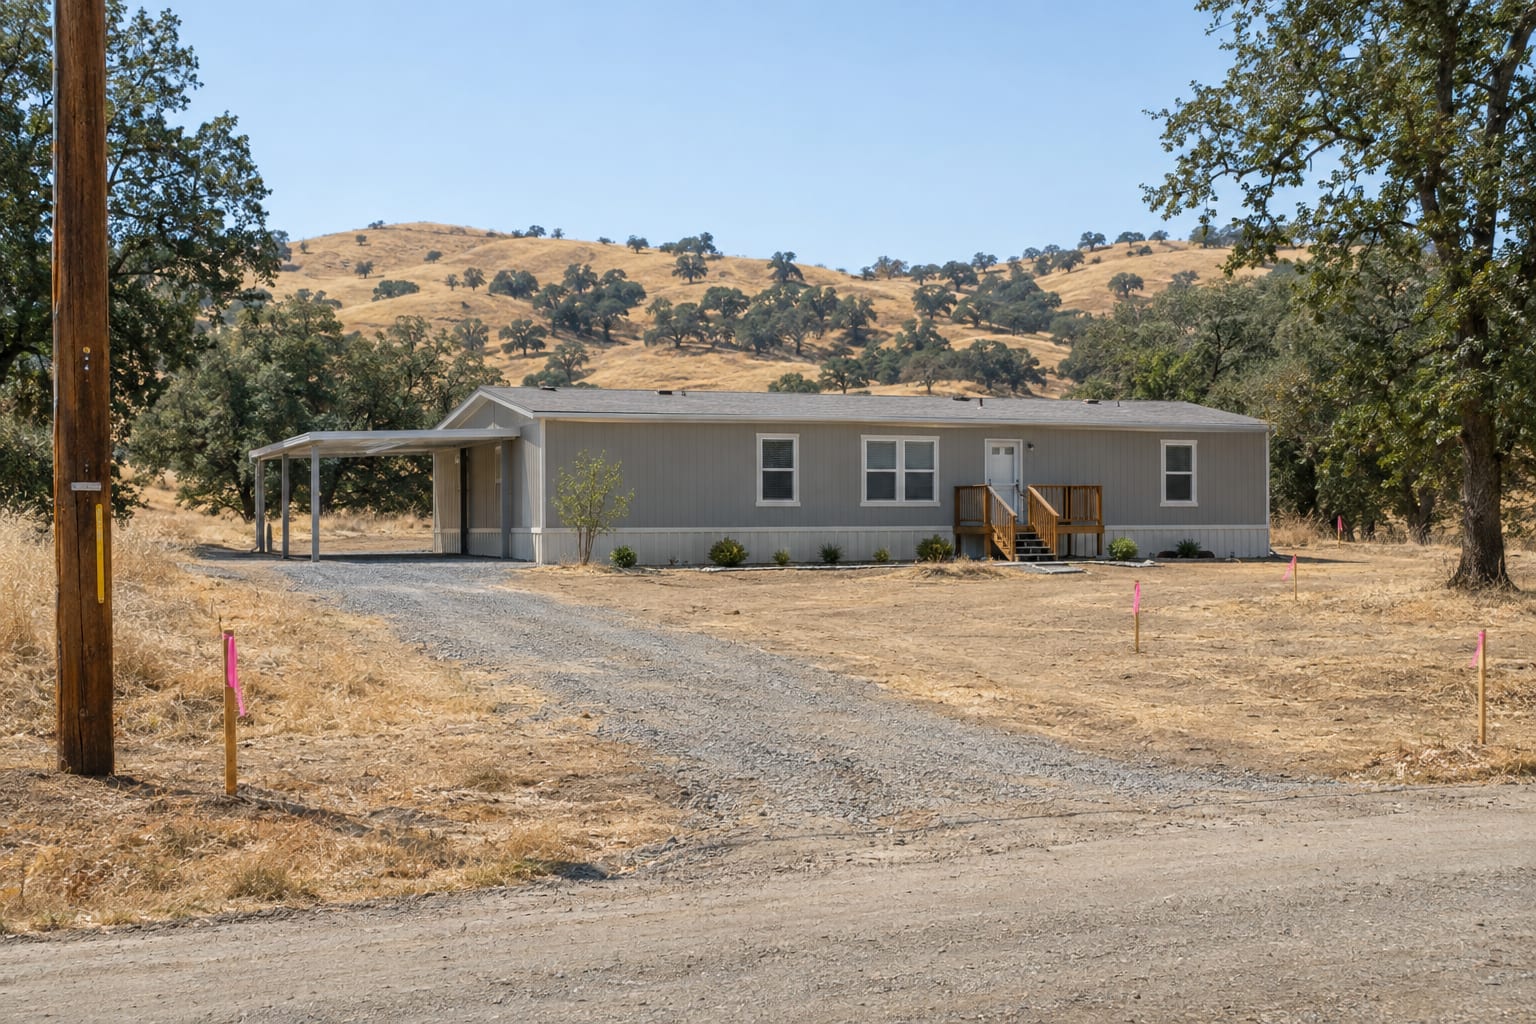
If you own the land a manufactured home will sit on, the equity in that land may be able to stand in for some or all of a cash down payment, with the home and land financed together as a land-and-home loan. Lenders call this land in lieu. Whether it is available for your project depends on the program, on what the land is worth against what you owe on it, and on the same review of you and the home as any loan.
The useful first step is to know the questions and bring the documents that answer them.
Getting a parcel ready for a home, from zoning to utilities to the foundation, is covered in buying a home on owned land. This article is about the land as a financial contribution.
What land in lieu means, and what it does not
In a conventional purchase you bring cash as a down payment and the lender finances the rest. With land in lieu, the value of land you already own is counted as your contribution to a loan that covers both the home and the land. The land becomes part of the collateral, and the home is permanently attached to it so the two can be financed as real property.
Two things it does not mean. It does not mean no cash: closing costs, prepaid items, the home’s delivery and setup, permits and site work all still have to be paid for, some before the loan funds. And it does not mean the land’s value is whatever you believe it to be; the lender’s appraisal sets the figure.
The four questions that decide it
What the lender looks at when land stands in for cash
| Question | Why it matters | What answers it |
|---|---|---|
| Do you own the land, in your name? | Only your own equity can be your contribution | The recorded deed |
| What is it worth? | The loan is based on the appraised value of home and land together | The lender’s appraisal, not your purchase price |
| What do you owe on it? | Equity is value less debt; a land loan has to be paid off or agreed to | The land loan statement, or a title report showing no lien |
| Can a manufactured home be placed on it? | The value assumes the project can be built | Zoning, permits, access and utilities for the parcel |
A loan on the land does not end the conversation, but it changes it. Depending on the program, the land loan may be paid off through the new loan, which reduces the equity available, or may need to stay in place with that lender’s agreement.
What to bring to the first conversation
The home side of the file is the same as any purchase; the complete list is in what to gather before you apply.
How the value is set
The lender orders an appraisal that values the home and the land together as one property, as the project will stand when it is finished. The land’s contribution is the appraised value of the land less anything owed on it. What you paid years ago, or what a neighbour’s parcel sold for, is context the appraiser may consider, but the figure the loan is based on is the appraisal.
Improvements count, and so do their records. A well with a drilling log, a septic system with its permit, a graded pad with its inspection: each is more readily credited than one with no paperwork. Site work you have not done yet is part of the project’s cost rather than the land’s value.
The cash the land does not cover
Even when land equity covers the down payment, a land-and-home project has costs that are paid in cash, several of them before the loan funds.
- Site work and permits, where the program does not finance them or finances them only in stages.
- Delivery and setup of the home, including the foundation system, utility connections and the installation permit.
- Closing costs and prepaid items: loan fees, title and escrow fees, the first insurance premium and interest to the first payment, covered in closing costs beyond the down payment.
- A land loan payoff, if the program requires the land to be free of other liens.
Ask your specialist for a written estimate of the cash the whole project will take, with land equity counted. Nothing here promises a result that needs no cash from you, and whether land in lieu is available for your scenario is a question for the program. Land-and-home financing describes how Santiago Financial, Inc. approaches home-and-land projects. All financing is subject to credit approval, and not all applicants or properties qualify.