
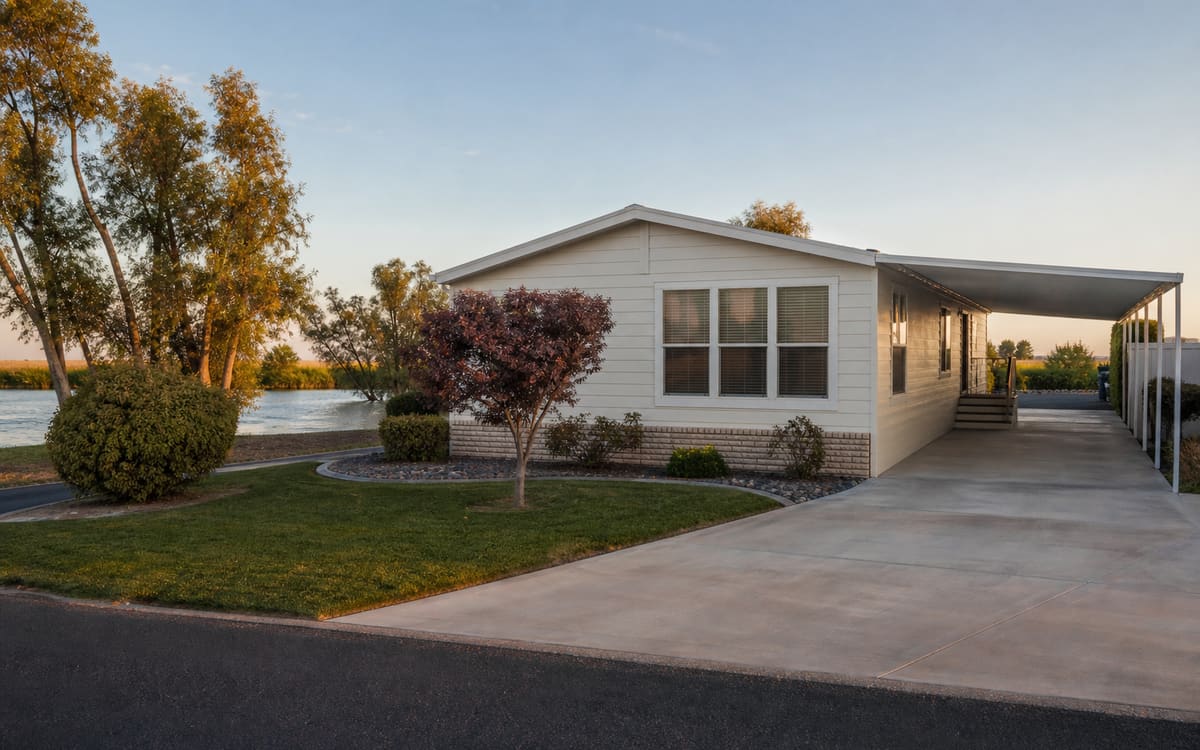
Stockton sits where the San Joaquin Valley meets the Delta — an inland port city with a thousand miles of waterway at its back door and the Bay Area an hour west. For a generation of households priced out of the Bay, San Joaquin County has been the answer, and manufactured homes are among the most attainable answers within it.
Santiago Financial, Inc. brings more than 50 years of manufactured housing specialization to the northern valley.
Who buys here, and why it shapes the file
Stockton’s manufactured home buyers tend to fall into a few recognizable groups, and each has a slightly different conversation with us:
Bay Area commuters. Priced out west, buying east. Their financing works exactly like anyone else’s — but their budget needs a commute line. Fuel, tolls, vehicle wear, and hours are real costs, and a community twenty minutes closer to I-205 can be worth more than a lower sticker price.
Longtime valley families buying their first home or moving up within a community they already know.
Retirees trading a maintained house for a manageable one, often in an age-qualified community.
Owned-land buyers in the county’s smaller towns and rural edges, where a land/home loan may fit.
We can’t tell you which group you’re in — but naming it early is what makes the budget conversation useful instead of generic.
Delta considerations worth raising early
San Joaquin County’s waterways are part of the region’s character and, occasionally, part of the paperwork. Properties in or near mapped flood zones carry specific insurance requirements. That is a cost and a documentation item, not a barrier — homes in these areas are bought and financed routinely. What causes delays is discovering the designation late. Give us the address early and we’ll tell you what applies, and our insurance services team can help arrange coverage suited to a manufactured home.
Community or owned land
In a community, the home is typically financed as personal property, the land is leased, space rent joins your monthly budget, and the community runs its own resident approval alongside the lender’s review.
On owned land — more common toward Lodi, Linden, and the county’s rural stretches — the questions become how the home is titled, whether it’s affixed as real property, and whether home and land transfer together. Wells, septic systems, and access roads are ordinary out there and simply need documenting.
Buying, step by step
- Apply online or call.
- Individual application review — income, ID, financials.
- Property documentation matched to community or land.
- Program review against current guidelines.
- Value support via appraisal or comparable sales.
- Conditions and escrow.
- Closing.
Refinancing in San Joaquin County
Owners revisit financing to review a payment, adjust a term, consolidate an eligible payoff, or update a loan after an ownership change. What’s possible depends on eligibility, the property, and current program guidelines — contact us for current program details.
Stockton and the Delta
The Port of Stockton runs ocean vessels seventy-five miles inland; the Delta’s sloughs draw boaters all summer; the University of the Pacific’s campus anchors the north side of town. Summers are hot and dry, winters bring the valley’s low tule fog, and the agricultural calendar still sets the region’s rhythm. For manufactured home buyers, San Joaquin County offers Northern California proximity at Central Valley prices — a trade a great many households have decided is worth making.
Nearby areas we serve
We finance manufactured homes throughout California, so your city doesn’t need a page here. Nearby guides include Modesto, Sacramento, and San Jose, plus Lodi, Manteca, Tracy, and Ripon. Browse all California service areas.
Put real numbers on the move
Estimate a payment — educational estimates, not offers — then apply or talk with a specialist.
Available programs and terms depend on borrower qualifications, property characteristics, loan amount, home location, land ownership, and lender guidelines. All financing is subject to credit approval.