Dealer vs. Private Party Manufactured Home Purchases: What Changes With Financing?
The loan review covers the same things on both paths: your credit and income, the home, its value, and where it sits. What changes is who prepares the paperwork around the sale. A dealer, a business licensed to sell manufactured homes, writes the purchase document and usually coordinates title, delivery and set-up. In a private-party sale, where you buy directly from the home’s current owner, those jobs fall to you, the seller and escrow, so the title and any loan the seller still owes get a closer look.
Neither path is the better one for financing. Each has jobs that someone has to do, and the useful questions are who does them and what you should ask to see.
Who handles what on each path
Dealer purchase compared with private-party purchase
| Part of the purchase | Buying from a dealer | Buying from the owner |
|---|---|---|
| Purchase document | The dealer writes a purchase order or sales contract | You and the seller write and sign a purchase agreement |
| Price | Dealer’s price, plus options, delivery and set-up | Negotiated; recent comparable sales help you judge it |
| Title or registration | New home: the first one is issued after the sale. Used home: the dealer coordinates the transfer | The seller’s current title is verified, then transferred to you |
| A loan the seller still owes | Uncommon on a new home | Paid off through escrow from the sale proceeds |
| Delivery and set-up | Arranged through the dealer when a home is ordered or moved | Usually none; the home stays on its space or lot |
| Condition | Ask what written warranty comes with a new home | Sold as it sits; an inspection tells you what you are buying |
| Community approval | You apply to the community | You apply to the community |
The last row is the same on purpose. If the home is in a land-lease community, where you own the home and rent the space under it, the community reviews you as a resident whoever the seller is. That review is separate from the loan, and a closing needs both.
What a dealer purchase adds
In California, manufactured home dealers and their salespeople are licensed by HCD (the Department of Housing and Community Development), and you can look one up in HCD’s occupational license search. In Arizona, dealers are licensed through the Arizona Department of Housing. Looking up the license is worth doing before you leave a deposit.
The purchase order defines what you are buying
The purchase order is the dealer’s main document, and the lender will ask for a copy. Read every line before you sign, because the price on it may or may not be the price of a finished home on its space.
In California, state law requires a dealer to give you a signed purchase document and to place any deposit or down payment in an escrow account (Health and Safety Code section 18035). Escrow is a neutral third party that holds funds and documents until every condition of the sale is met. In Arizona, ask the dealer where your deposit will be held. This is general information, not legal advice.
A new home has to be built, delivered and set up
A home ordered from the factory has stages that a home already in place does not: the build, transport to the site, installation on its supports, utility connections, and an inspection of the installation under the permit. Each stage has its own party and its own schedule, so timing depends on all of them. Ask the dealer which stages are in the purchase order, who hires the installer, and what has to be finished before you can move in.
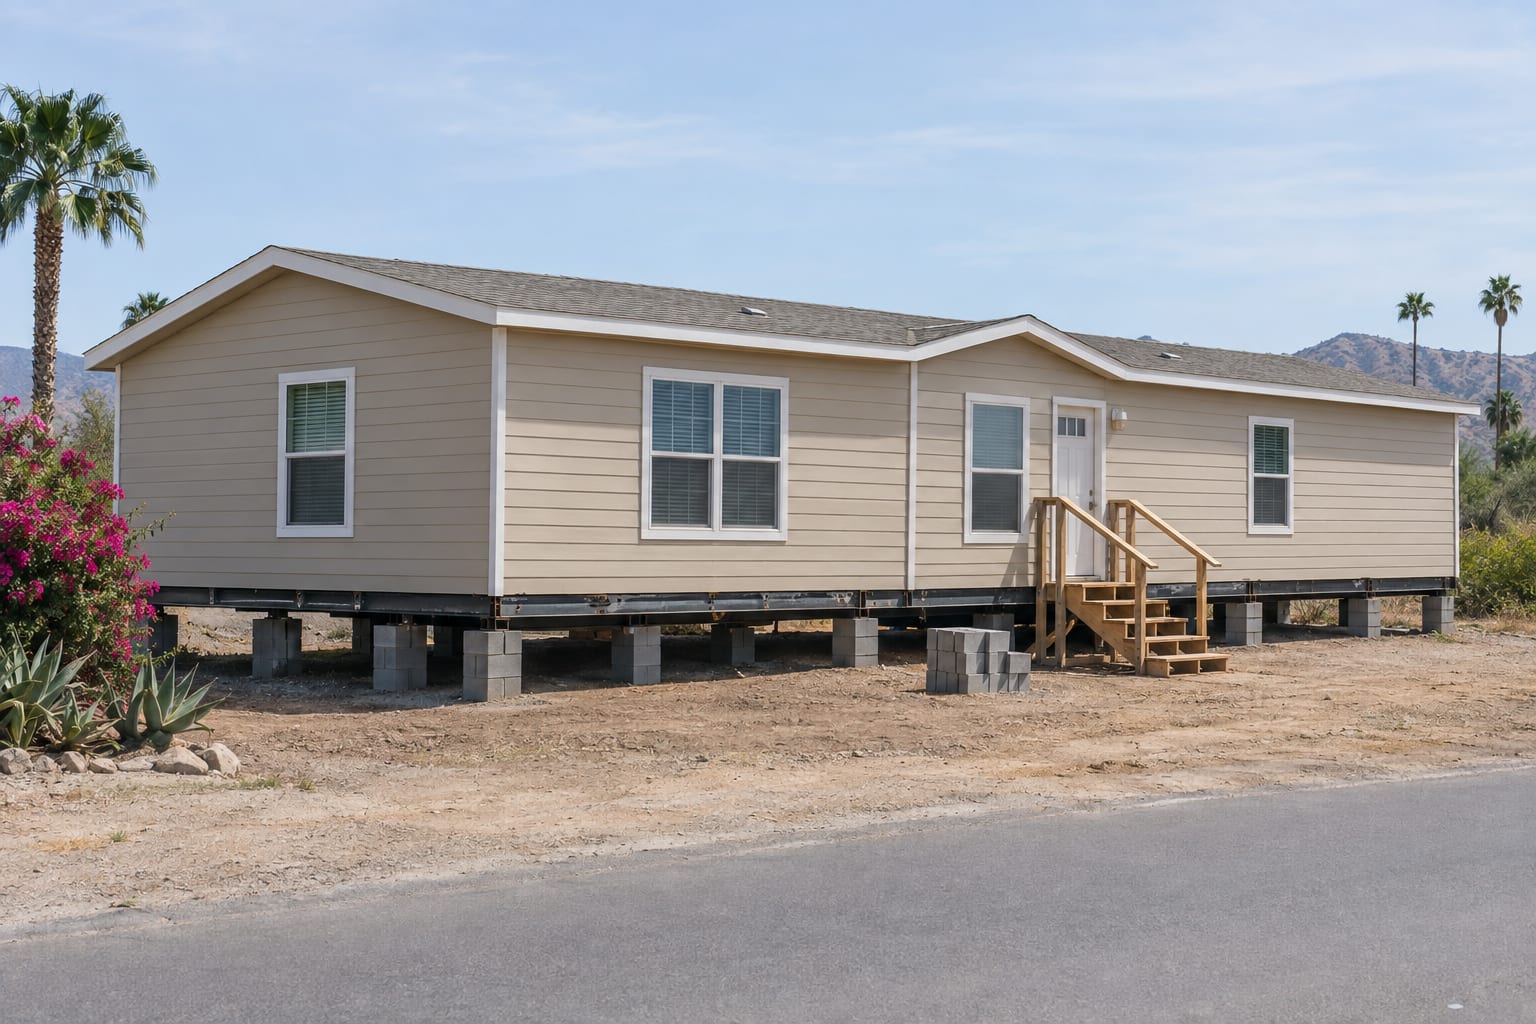
The home also needs somewhere to go. A space in a community has to be confirmed with the community, which often has its own standards for the homes it accepts. Land you own may need site work, utilities and a foundation, which makes it a land-and-home financing project instead of a home-only purchase.
Title starts fresh on a new home
A new home has no ownership history. Its first title or registration is issued after the sale, from the manufacturer’s paperwork that the dealer supplies. A used home on a dealer’s lot, or one a dealer is selling for its owner, has a title history like any resale, so the current title and any lienholder on it are still verified.
Whether a new or a pre-owned home is the better fit for your budget is a separate question, covered in new vs. pre-owned manufactured homes.
What a private-party purchase leaves to you and the seller
A private seller is not in the business of selling homes. They have a title or registration, perhaps a loan, and a price in mind. Everything a dealer would prepare has to come from the two of you:
- A written purchase agreement. It names the buyer and the seller as they appear on the title, identifies the home by serial number, and states the price, the deposit and what stays with the home.
- The title, in the seller’s name. Every owner shown on it has to be available to sign.
- Payoff details. If the seller still owes on the home, escrow needs the lender’s name to request a payoff figure.
- Support for the price. No price sheet exists, so recent sales of similar homes are the reference.
The order these happen in, and what the buyer and the seller each do, is laid out in the steps for financing a private-seller purchase. If the seller is a relative, the same steps apply with a few additions, covered in buying a manufactured home from a family member.
A private sale also means buying the home as it sits, with repairs and upkeep you know little about. An independent inspection tells you its condition, and an appraisal or comparable sales support its value. They are two different reports: see inspection vs. appraisal.
Where the two paths rejoin
Once a home is identified and a purchase document is signed, both paths run through the same stages.
From a signed purchase document to closing
- Application and review You apply, and the application is reviewed against current program guidelines. Pre-qualification before this point is not final approval.
- Documents and conditions You send income, asset and identification documents. The dealer or the seller supplies the purchase document and the home’s details.
- Community approval If the home is on leased land, the community reviews you as a resident. Its decision is separate from the lender’s.
- Value, title and insurance The home’s value is supported, its title or registration is verified, and you arrange a homeowners policy.
- Signing and funding You sign loan documents through escrow, the loan funds, and the title is issued or transferred to you.
Each stage, with who is involved and what you do, is described in how the loan process works. Timing depends on the transaction and the third parties involved, and all financing is subject to credit approval.