
Buying and Financing Mobile and Manufactured Homes

Top 10 Mobile Home Loan Questions Buyers Ask (Answered Clearly)

An older single-section mobile home with white lattice panels, a striped window awning, flower pots and a carport beside a lawn

These are the ten questions buyers ask most often in a first conversation about financing a manufactured home. Each has a short answer here and a link to the page that covers it properly. Fuller answers are in the questions section at the end of this page.

You won’t find a rate, a credit score or a down payment percentage below. Those depend on the program, your credit, the home, and whether the land is leased or owned, so for several of these questions the honest short answer is what the answer depends on.

Whether a manufactured home can be financed

Four of the ten questions are versions of “is this even possible?” It is, subject to credit approval, and the land decides how.

QuestionShort answer
Can I get a loan on a mobile or manufactured home?Yes. The kind of loan depends on whether the land is leased or owned. Compare loan programs.
Can I finance a home in a park?Yes. The home is financed on its own and you rent the space. See what a chattel loan is and when it is used.
Do manufactured homes qualify for FHA or VA loans?Those programs exist, each with its own eligibility, property and foundation rules. Ask whether one fits your situation.
Why use a manufactured housing lender instead of a bank?Many lenders finance only homes on owned land. Read what a specialist lender does differently.

A home in a community also needs the community’s own resident approval. That is a separate review from the lender’s, and a closing needs both.

What it costs

Nobody can quote these three in general terms. What a specialist can do is tell you what applies once the home, the land and your details are known.

QuestionShort answer
What credit score do I need?There is no single number. Credit requirements vary by program and investor. Start with preparing your credit for an application.
How much down payment is required?There is no single down payment. It depends on the program, your credit, the home and the land. See how down payments work.
Are rates higher than on a regular mortgage?Home-only loans generally run shorter and are priced to reflect the different collateral. Your own rate depends on the program, your credit, the home and the loan amount.

For a sense of the monthly figure, enter your own numbers in the payment calculator, and remember that space rent is paid on top of the loan payment. The results are educational estimates, not a loan offer.

The home itself

One question is about the home, not the loan, and it changes the answers to most of the others: is it a mobile home or a manufactured home?

Mobile home compared with manufactured home

Mobile homeManufactured home
BuiltBefore June 15, 1976On or after June 15, 1976
Building standardPre-dates the federal HUD CodeBuilt to the HUD Code
HUD labelNoneOne on each section
FinancingTreated differently by lenders, so ask before you make an offerDepends on the program, your credit, the home and the land

The date is when HUD’s manufactured home standards took effect. People call both kinds mobile homes, and that’s fine in conversation, but a lender will ask for the year. HUD label, data plate and serial number shows where to find it on the home.
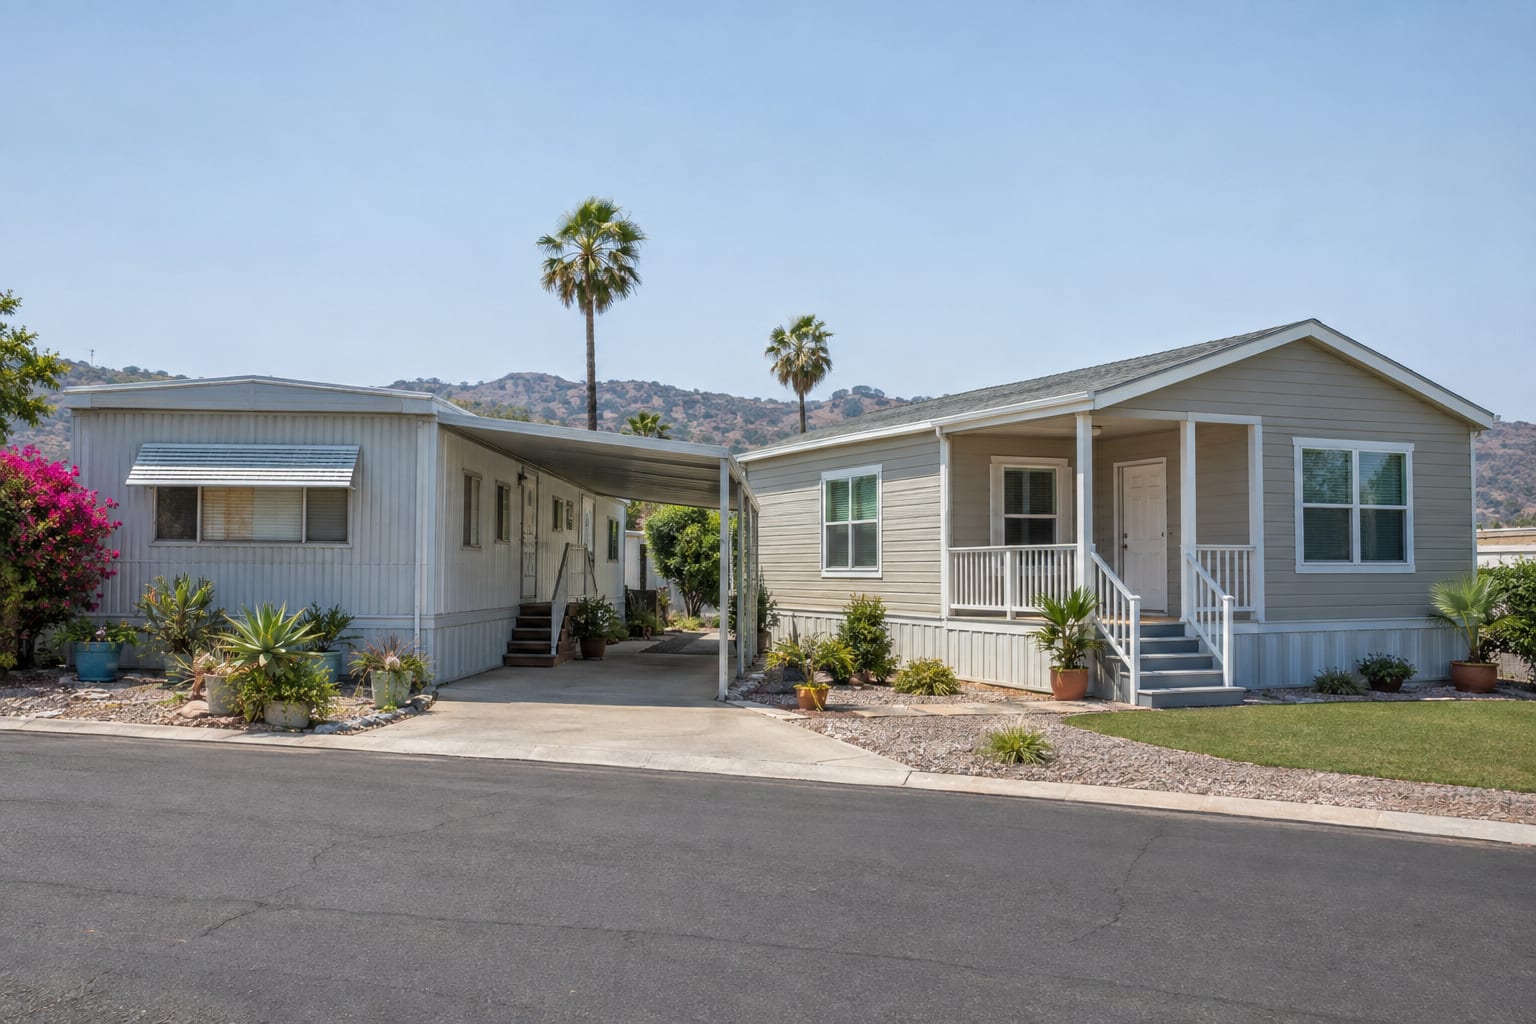
An older flat-roofed single-wide mobile home with aluminum siding next to a newer double-wide manufactured home with a pitched shingle roof
Style gives a hint, but the build date on the data plate is what a lender goes by.

The process and what comes after

The last two questions are about time: how long the loan takes, and whether you can change it later.

QuestionShort answer
How long does the loan process take?Timelines vary with each transaction. Appraisal scheduling, community approval, title questions and missing documents are the usual waits. See how the loan process works.
Can I refinance a manufactured home later?Refinancing may be available depending on the home, land status and current guidelines. See when and how to refinance.

Before any of this, it helps to get pre-qualified, which is an early estimate and not final approval. Pre-qualification compared with pre-approval explains the difference. If this is your first purchase, the first-time buyer’s order of events puts all ten answers in sequence.

FAQ

Frequently asked questions

Can you get a loan on a mobile or manufactured home?

Yes. A home in a land-lease community is usually financed on its own as personal property with a home-only (chattel) loan. A home permanently attached to land you own can often be financed together with the land as real property. Which one applies depends on the home, the land and the title. All financing is subject to credit approval, and not all applicants or homes qualify.

What credit score do I need for a mobile home loan?

There is no single score. Credit requirements vary by program and investor, and every application is reviewed individually, with your payment history, debts and income considered alongside the home itself. Check your free credit reports at annualcreditreport.com before you apply, dispute any errors, and then ask a specialist what applies to your scenario.

How much down payment is required for a manufactured home?

There is no single down payment. It depends on the program, your credit, the home, and whether the land is leased or owned. If you already own the land, its equity may be able to count toward the down payment on a land-and-home loan, depending on the land's value, any liens and the program. Plan for closing costs and the first insurance premium as well.

Are interest rates higher on mobile home loans than on regular mortgages?

It depends on the kind of loan. Compared with real-property financing, home-only (chattel) loans generally run shorter and are priced to reflect the different collateral. A manufactured home recorded as real property with its land is generally financed more like a site-built house. Your own rate depends on the program, your credit, the home, and the loan amount.

Can I finance a mobile home in a park?

Yes. A home in a land-lease community is financed with a home-only (chattel) loan: the loan covers the home, and you rent the space from the community. Space rent is paid on top of the loan payment and counts as part of your monthly housing cost when a lender reviews your income. The community also runs its own resident approval, and a closing needs both approvals.

What is the difference between a mobile home and a manufactured home?

The build date. A manufactured home is a factory-built home constructed on or after June 15, 1976 to the federal HUD Code, and each section carries a HUD label. A factory-built home from before that date is, technically, a mobile home. People use the two terms interchangeably, but lenders treat pre-1976 homes differently, so confirm the year before you make an offer.

Can I refinance my manufactured home?

Refinancing may be available depending on the home, land status, and current guidelines. A lender looks at the home's age, condition and value, the title, your credit and income, and whether the home sits on leased or owned land. Ask whether a refinance could lower your monthly payment or shorten your loan term, and weigh the costs of the new loan against what it would change.

How long does the mobile home loan process take?

Timelines vary with each transaction. The stages are application, review and decision, documents and conditions, community approval for a home on leased land, a value review, title and escrow, signing, and funding. Having your documents ready early is the part you control. Appraisal scheduling, community approval and title questions are the most common reasons a file waits.

Do mobile homes qualify for FHA or VA loans?

Government-backed programs such as FHA, VA and USDA exist, and each has its own eligibility, property, foundation and fee rules. Whether one fits depends on the home, the land and your own circumstances, and programs change. Ask whether a government-insured program fits your situation before you choose a home, because the home and its foundation are part of the answer.

Why use a manufactured housing lender instead of a bank?

Many lenders finance only homes on owned land, and a home in a community is personal property with a state-agency title and a separate community approval. A specialist checks the title, the registration and any existing lien early, and coordinates the community's review with the loan. Manufactured and mobile homes are the only thing Santiago Financial, Inc. finances, in California and Arizona only.

Free Tool

Estimate your monthly payment

Try our manufactured & mobile home loan calculator — adjust price, down payment, term, taxes, and space rent to see an estimated monthly payment. Estimates are for educational purposes; all financing is subject to credit approval.

Ready to finance your manufactured home?

Start online, by phone, or with a printable application. A specialist reviews the home, where it sits, and your situation together, then tells you what is needed next. No obligation; subject to credit approval.

Results update as you type. Use the up and down arrow keys to move through results, Enter to open one.

See all results