Common Myths vs. Facts About Mobile Home Financing
Much of what gets repeated about financing a manufactured home is out of date, or true of only one kind of loan. Seven claims come up again and again: that the terms are always poor, that an older home means paying cash, that every loan is a chattel loan, that you can’t refinance, that the fees are hidden, that pre-qualified means approved, and that the lender’s approval is the only one you need. None holds up as stated.
The table gives the short version, and the sections after it explain what each answer depends on. For beliefs about the homes themselves, such as build quality, value and whether you must own land, see manufactured home myths for buyers who haven’t started shopping.
Seven financing myths and what is true
| Myth | Fact |
|---|---|
| The terms are always worse than a house loan | Terms depend on the program, your credit, the home and the land |
| An older home has to be bought with cash | A pre-owned home can be financed; the build date and condition affect what is available |
| Every manufactured home loan is a chattel loan | A home attached to land you own can often be financed with the land as real property |
| You can’t refinance a manufactured home | Refinancing may be available depending on the home, land status and current guidelines |
| The fees are hidden | The cost of a loan has to be disclosed in writing before you sign |
| Pre-qualified means approved | Pre-qualification is not final approval |
| Once the lender approves, you’re done | A home in a community also needs the community’s approval |
Terms depend on the home and the land
This belief has a real source. A home in a land-lease community is financed on its own as personal property with a home-only loan, usually called a chattel loan. Compared with real-property financing, chattel loans generally run shorter and are priced to reflect the different collateral. What a chattel loan is and when it is used explains the structure.
That is a difference between two kinds of loan, not a verdict on every offer. Your rate depends on the program, your credit, the home, and the loan amount. Available terms also depend on the home’s age and type and on whether the land is owned. Judge the offer in front of you on its own figures.
A pre-owned home is not automatically a cash purchase
Age matters, but the line is not where most people put it. The date lenders care about is June 15, 1976, when the federal HUD Code took effect. A home built on or after that date is a manufactured home and carries a HUD label on each section. Whether it can be financed then depends on the program, the home’s condition and value, the title, and your own application.
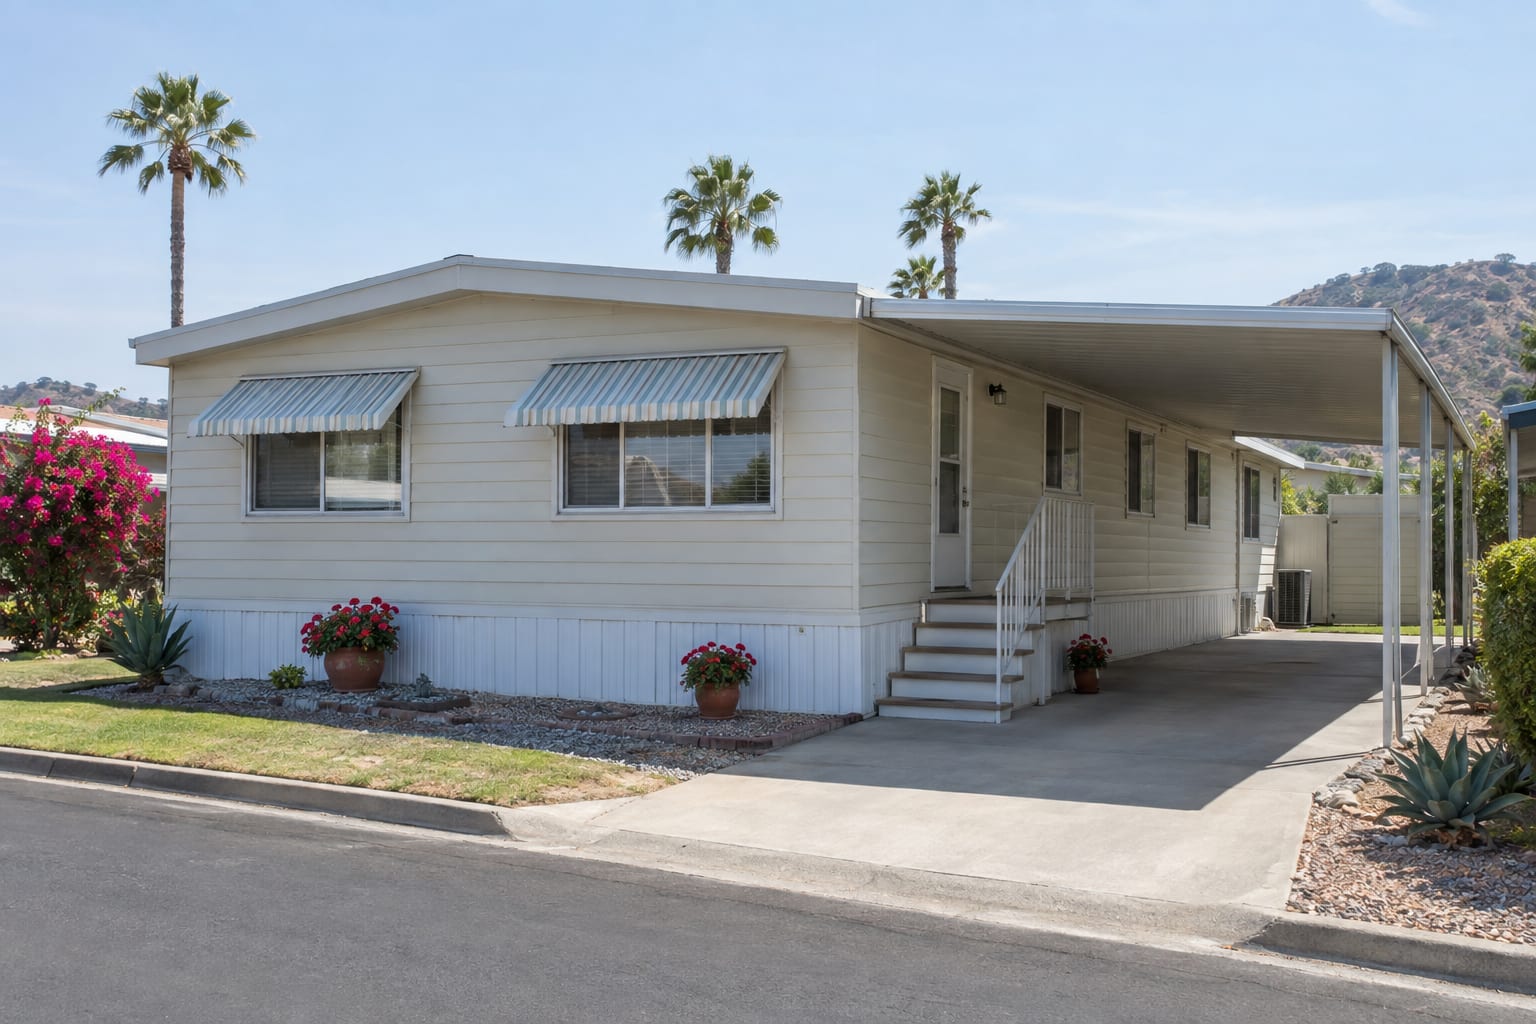
A home built before that date is, technically, a mobile home, and lenders treat those homes differently. If you’re looking at one, ask whether financing is available for that specific home before you make an offer. Financing options for pre-owned manufactured homes goes into the details.
Not every loan is a chattel loan
Chattel loans are the standard structure for homes on leased land, which is why people assume they are the only kind. When a home is permanently attached to land you own or are buying, the home and land can often be financed together as real property.
The property record is what makes the difference. In California, HCD Form 433A is used to report the installation of a manufactured home on a foundation system and is recorded with the county when applicable. In Arizona, the Affidavit of Affixture process generally involves surrendering the MVD title and recording the affidavit with the county.
Neither record by itself guarantees financing, and foundation requirements depend on the program. This is general information, not legal or tax advice, so confirm current procedures with the agency.
Refinancing is possible for some homes
Refinancing may be available depending on the home, land status, and current guidelines. A lender reviews much the same things as on a purchase: the home’s age, condition and value, the title, and your credit and income.
What a refinance will do for you can’t be assumed in advance. Ask whether a refinance could lower your monthly payment or shorten your loan term, then set the costs of the new loan against what it would change. Refinance options covers what is reviewed.
The cost of a loan has to be disclosed in writing
A manufactured home loan has costs beyond the payment. Depending on the transaction they can include an appraisal or value report, escrow, title and registration transfer fees, and the first insurance premium. None of them should come as a surprise.
A lender must give you the cost of the loan in writing before you sign. For a mortgage secured by real estate, that arrives as a standard Loan Estimate. For a manufactured home loan that is not secured by real estate, the Consumer Financial Protection Bureau says to expect Truth-in-Lending disclosures instead.
Whichever form you receive, ask for an itemized list of every charge, who it is paid to, and which figures are estimates. Then budget separately for the costs that sit outside the loan: space rent, insurance, and taxes or registration fees on the home.
Pre-qualification is not approval
Pre-qualification is an early, informal estimate of the financing range that may be realistic, based on information you provide. It is not a loan approval and not a commitment. Final approval requires verification of your income and credit, an acceptable home, value and title work, and every condition being met.
Treat a pre-qualification as a price range to shop in. Don’t give notice on your current place, or put down a deposit you can’t get back, on the strength of one. Pre-qualification compared with pre-approval sets out what each stage does and does not promise.
The lender’s approval is not the only one you need
If the home sits on leased land, the community runs its own resident application with its own criteria. Community approval and lender approval are separate reviews by separate parties, and a closing needs both.
Passing community resident approval explains how that review works.