The Difference Between Chattel Loans and Mortgage Loans for Mobile Homes
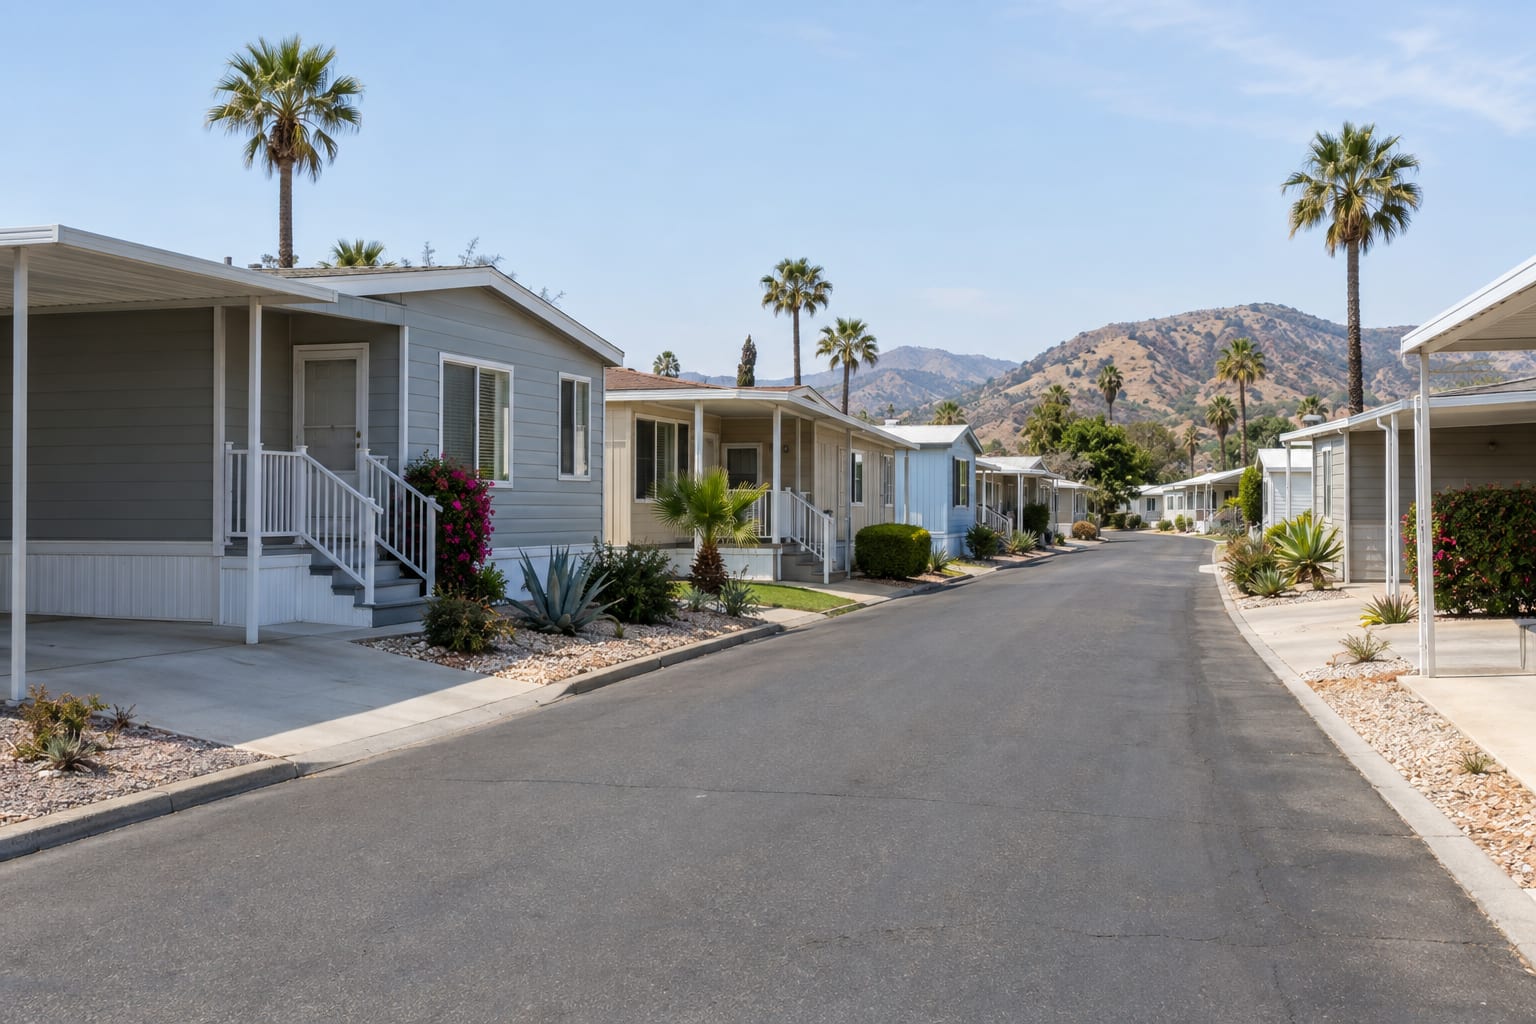
A chattel loan is secured by the manufactured home alone. A mortgage is secured by the home and the land together, which is only possible when you own the land and the home has been recorded as part of it. So the property usually makes the choice for you: a home on a rented space in a community is financed home-only, and a home recorded with its own lot can be financed as real estate.
What is worth comparing is how the two differ once you know which one you are dealing with: what backs the loan, where it is recorded, what your monthly cost includes, how value is set, who is involved at closing, and what happens when you sell.
The two loans in brief
A chattel loan, or home-only loan, finances the home itself as personal property, without any land. It is the standard structure for homes in land-lease communities, where you own the home and rent the space. The full definition is in what a chattel loan is and when it is used.
A mortgage on a manufactured home is usually called a land-and-home loan. It finances the home and the real property together in one transaction, so the home has to be permanently attached to land you own or are buying, and recorded with that land. Land-and-home financing covers how Santiago Financial, Inc. handles those transactions.
How the two loans compare
Home-only (chattel) loan and land-and-home mortgage, side by side
| How they differ | Home-only (chattel) loan | Land-and-home mortgage |
|---|---|---|
| What secures the loan | The home | The home and the land together |
| How the home is classified | Personal property | Real property |
| Where ownership and the lien are recorded | The state title record: HCD in California, the MVD in Arizona | The county recorder, with the land |
| What your monthly housing cost includes | Loan payment, space rent, insurance, and taxes or registration fees on the home | Loan payment, plus property taxes and insurance on home and land. No space rent |
| How value is supported | Often comparable sales of similar homes | An appraisal of home and land together |
| Who is involved besides you and the lender | Seller or dealer, escrow, the state title agency, the community, an insurer | Seller, escrow, an appraiser, land title work, the county recorder, an insurer |
| What you build equity in | The home | The home and the land |
| When you sell | The home changes hands on its title, and the buyer needs community approval | Home and land are sold together as real estate |
The table leaves out rate and term on purpose. Both depend on the program, your credit, the home and the loan amount, so a single figure for either column would mislead. The general pattern is that chattel loans run shorter than real-property loans and are priced to reflect the different collateral. A shorter term means a higher payment for the same amount borrowed.
Two purchases, two different files
The same buyer, with the same income and credit, would go through a different process depending on which home they chose. Two made-up purchases show how.
A home on a rented space in Southern California
What stands out here is the second approval. Community approval and lender approval are separate reviews, and the purchase cannot close until both are in place.
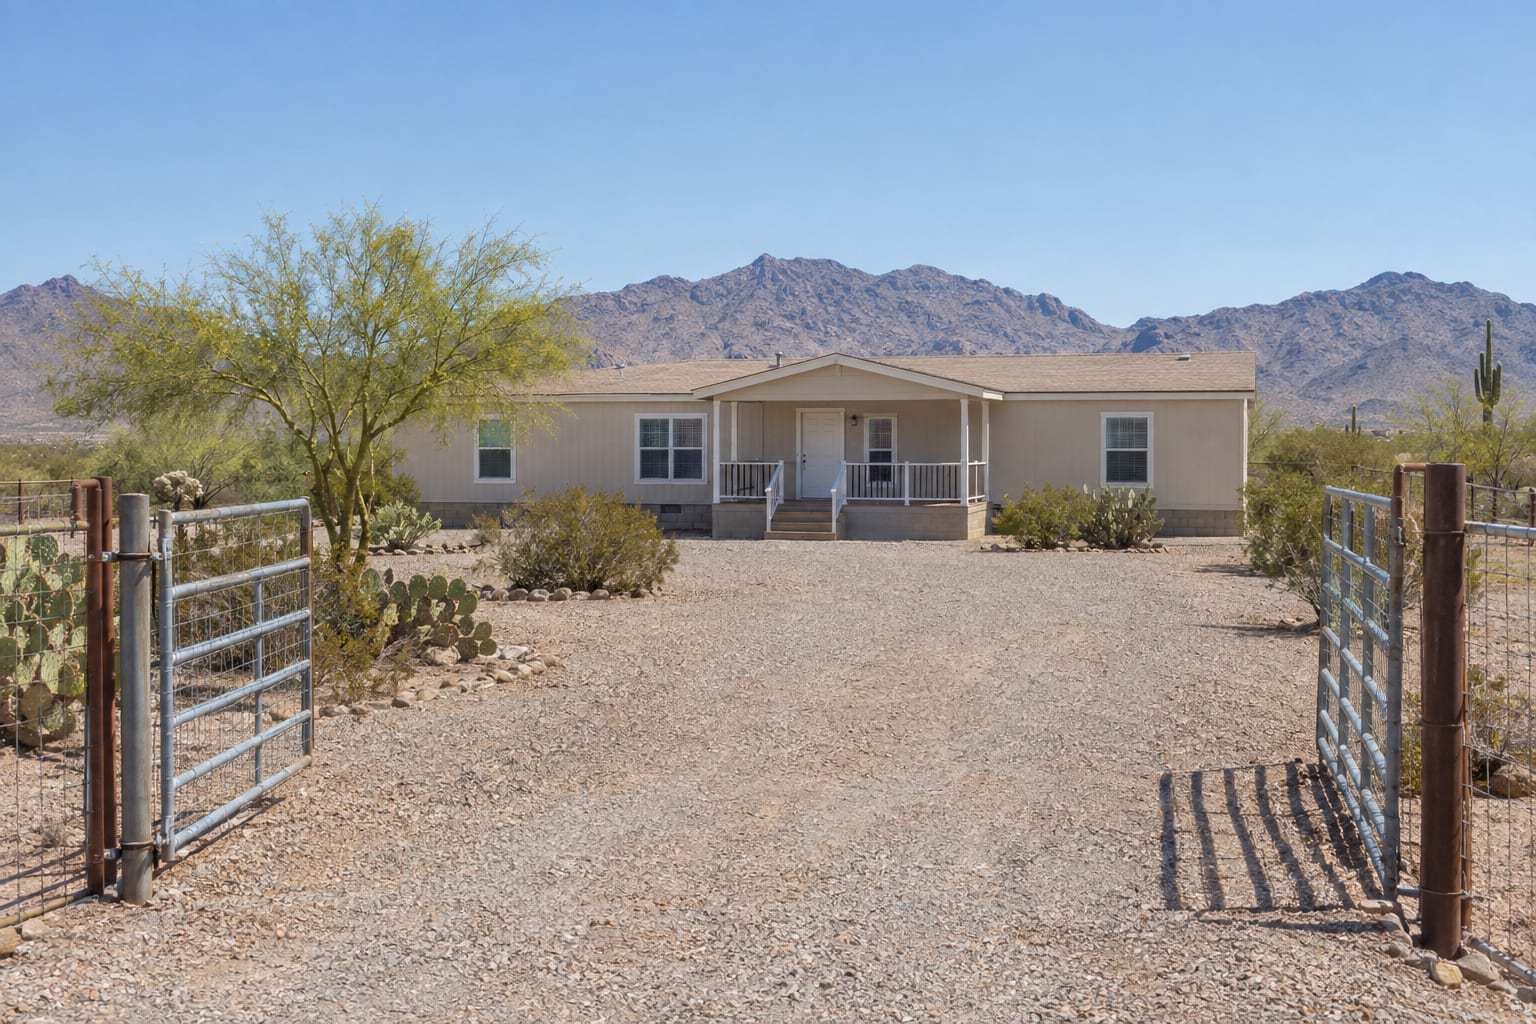
A home on its own lot in rural Arizona
Here there is no community and no space rent, but there is more to verify about the property itself: the land title, the foundation, the recorded documents, and on a rural parcel the well, the septic system and the access road.
What each loan means while you own the home
With a home-only loan you have two monthly housing bills: the loan payment and the space rent. The rent is set by the community and can change over time, so get the current amount and the recent increase history in writing before you buy.
With a land-and-home mortgage there is no space rent. Instead, you pay property taxes on the land as well as the home, and everything on the parcel is yours to maintain.
What you are paying down differs too. A home-only loan pays down a home. The land stays with the community, and a future buyer will need the community’s approval and will look closely at the space rent. A land-and-home mortgage pays down a home and a parcel together, and the property is later sold as real estate.
For the cost side in more detail, see the long-term cost comparison of a park and owned land.
Which loan applies to your purchase
If you will rent the space, the loan is home-only. If you will own the land and the home is already recorded with it, a land-and-home mortgage is the usual route.
The middle case, owned land with a home that still has its own title, is the one to raise before you make an offer. Converting the home is what moves it from one column of the table to the other. The guide to personal property vs. real property explains how a home’s status is checked.
In California the conversion record is HCD Form 433A, which is used to report the installation of a manufactured home on a foundation system and is recorded with the county when applicable. In Arizona it is the Affidavit of Affixture, which generally involves surrendering the MVD title and recording the affidavit with the county. Either one is an important property record, but it does not by itself guarantee financing.
The same applies after you buy. An owner who converts may be able to refinance home and land together, depending on the home, the land and current guidelines.
The official sources are HCD registration and titling for California and ADOT MVD mobile home ownership for Arizona. Confirm current procedures with the agency; this is general information, not legal or tax advice.
If the home you want is on land, read the financing questions to ask about owned land next. If you are not sure which case is yours, find your financing path asks three short questions and points you to the one to read about.